

|
시장보고서
상품코드
2123362
항공기 페어링 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Aircraft Fairings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
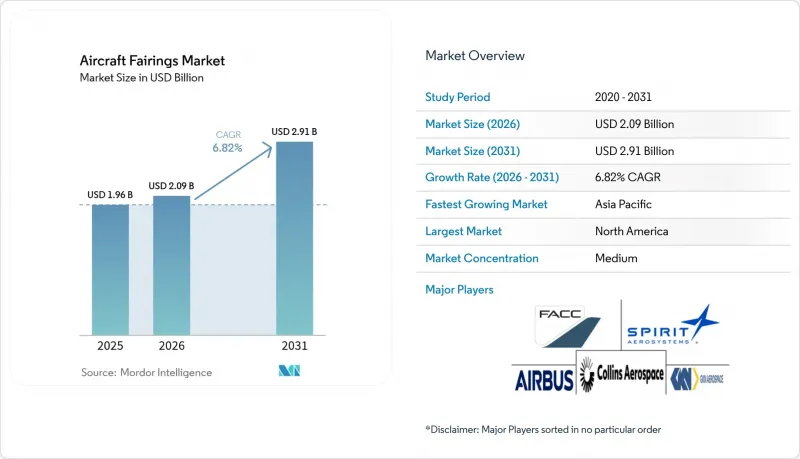
에 의하면, 항공기 페어링 시장 규모는 2025년에 19억 6,000만 달러로 평가되었고 2026년 20억 9,000만 달러에서 2031년까지 29억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.82%를 나타낼 전망입니다.
본 보고서는 용도(동체, 착륙장치, 주익, 조종면, 엔진), 소재(유리섬유 복합재, 금속 합금, 열가소성 복합재 등), 항공기 유형(민간기, 군용기 등), 판매 채널(OEM 생산, 애프터마켓 MRO),지역(북미, 유럽, 아시아태평양 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 항공기 페어링 시장 동향 및 인사이트
연료 효율 목표 달성을 위한 복합재료 채택 급증
심각한 연료비 압박에 직면한 항공사들은 알루미늄 페어링에서 CFRP 페어링으로의 전환을 추진하고 있으며, 차세대 항공기에서 복합재료의 채택률은 기존 A330의 13%에서 현재 50% 이상으로 상승했습니다. 에어버스(Airbus)의 다기능 동체 시연기(Multifunctional Fuselage Demonstrator)는 열가소성 수지 재질의 외판이 10%의 추가 경량화를 실현할 수 있을 뿐만 아니라,월100대라는 생산 속도의 자동 용접에도 대응할 수 있음을 보여주고 있습니다. 경제적 이점은 여전히 매력적입니다. 복합재 페어링을 장착할 경우, 전체 수명 주기 동안의 연료비 절감 효과는 항공기 구매 가격의 15-20%를 상쇄할 가능성이 있습니다. 그러나 이러한 전환에는 오토클레이브, 로봇 적층 셀, 전문 기술자에 대한 막대한 설비 투자가 필요하며, 진입 장벽이 높아짐에 따라 OEM 각사는 성숙한 복합재 생태계를 보유한 파트너를 우선적으로 선택하고 있습니다.
노후화된 항공기 기단 전체에 걸친 급속한 갱신
매년 700대 이상의 제트기가 퇴역하고 있으며, 이로 인해 부품 회수 및 개조 수요가 발생하여 개조 시장이 확대되고 있습니다. 와이드바디 항공기의 페어링은 장거리 운항이 반복되면서 마모가 심해지기 때문에 납기 지연이 계속되는 가운데 항공사들은 신규 발주보다는 공기역학적 성능 향상 키트의 도입을 선호하는 추세입니다. Sumitomo와 Werner Aero의 제휴에서 볼 수 있듯이, 복합재 페어링을 2차 시장을 위해 회수하는 순환형 경제 프로그램은 탄력을 받고 있지만, CFRP 재활용에는 한계가 있고 비용도 많이 든다는 엄중한 현실에 직면해 있습니다.
탄소섬유, 에폭시, 고온용 수지의 가격 급등 및 변동이 공급업체의 이익률을 압박
항공우주 분야의 탄소섬유 수요는 연평균 17%의 성장이 예상되지만, 생산 능력 확충에는 고액이며 장기간에 걸친 투자가 필요합니다. 지정학적 긴장과 관세 위험으로 인해 가격 예측이 어려워지면서 공급업체들은 원가 가산 계약을 채택할 수밖에 없게 되었으나, 그 결과 중소기업들은 견디기 힘든 운전자금 부족에 내몰리고 있습니다.
부문 분석
동체 페어링은 복잡한 날개와 동체 접합부의 형상 및 OEM에 의한 통합의 장벽이 높기 때문에 2025년에는 항공기 페어링 시장 규모의 32.84%를 차지했습니다. 설계 변경 시마다 공기역학 시험을 전면적으로 다시 수행해야 하기 때문에 수요는 견조한 추세를 보이고 있으며, 기존 공급업체를 대체하기는 어렵습니다. 착륙 장치 페어링은 공항 소음 규제의 강화와 수납식 스트럿을 요구하는 eVTOL 프로그램 수요에 힘입어 연평균 성장률(CAGR) 6.94%로 확대되고 있습니다. 날개·동체 및 조종면 페어링은 주류 생산 속도에 맞추어 추세를 이어가고 있는 반면, 엔진 페어링은 냉각 기능이 있는 페어링 쉘을 필수로 하는 하이브리드 전기식 실증기로 인해 점진적인 성장을 보이고 있습니다.
신흥 모빌리티 플랫폼에서는 설계 요건이 신속한 제조로 전환되고 있습니다. 위치타 주립대학교의 조사에 따르면, UAV 운영사는 몇 주가 아닌 며칠 만에 제조 가능한 프린트 가능한 모듈식 페어링을 선호하는 것으로 나타났습니다. Deutsche Aircraft의 D328eco 계약에서는 동체 도어와 랜딩 기어 도어가 단일 계약으로 통합되어 있어, OEM이 통합된 공급업체 패키지로 전환하고 있음을 보여줍니다. 이러한 일괄 계약은 광범위한 설계 툴셋과 시험기 제조 능력을 갖춘 공급업체에 유리하게 작용합니다.
CFRP의 점유율이 62.78%에 달한다는 사실은 와이드바디기, 나로우바디기, 나아가 회전익기 프로그램에 이르기까지 그 입지가 확고함을 보여줍니다. 그러나 연간 8.86%의 성장률을 보이는 열가소성 복합재료와 적층 조성을 통한 폴리머는 오토클레이브로 인한 병목 현상을 해소하고, 부품 수를 줄임으로써 조립 작업의 노동력을 대폭 절감할 수 있게 해줍니다. 경량 UAV 페어링의 경우, 비용상의 제약으로 인해 유리 섬유가 여전히 유력한 선택지로 남아 있지만, 손상 허용성이 요구되는 중요한 부위(동체 하부의 친 패널 등)에서는 여전히 알루미늄·리튬 합금이 채택되고 있습니다.
Hexcel의 HexAM PEKK 레이저 소결 플랫폼은 기존의 기계 가공으로는 불가능했던 복잡한 페어링 브래킷을 성형하여, 스크랩 감소와 경량화를 동시에 실현하고 있습니다. EU가 자금을 지원하는 DOMMINIO 프로젝트에서는 열가소성 수지제 페어링에 구조 건전성 센서를 내장함으로써 이 디지털 스레드를 확장하고, 생산 라인의 장착 공정에서 직접 예측 보수를 통한 건전성 모니터링을 실현하고 있습니다. 향후에는 적층 CFRP 외피와 3D 프린팅된 열가소성 수지 리브를 결합한 복합재료 구조가 항공기 페어링 시장을 주도할 가능성이 있습니다.
지역별 분석
2025년, 북미는 항공기 페어링 시장 점유율의 36.24%를 차지했습니다. 이는 보잉(Boeing)의 생산 회복에 더해, 미국 내 여러 주에서 복합재 생산 능력을 강화하기 위한 GE Aerospace의 10억 달러 규모의 제조 투자가 뒷받침한 결과입니다. 워싱턴주와 사우스캐롤라이나주에 오랫동안 존재해 온 클러스터는 공급업체에 성숙한 생태계를 제공하고 있지만, 관세 정책과 숙련된 인력 부족이 계속해서 비용 구조에 압박을 가하고 있습니다. RTX의 20억 달러 규모 시설 확장은 단기적인 사업 환경이 인플레이션 경향을 보이고 있음에도 불구하고, OEM이 지속적인 수요를 확신하고 있음을 보여줍니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 2031년까지 연평균 성장률(CAGR) 8.51%를 기록할 전망입니다. 중국의 C919나 인도의 HTT-40과 같은 국산화 프로그램으로 인해 현지화 요건이 강화되면서, 유럽과 미국의 1차 공급업체들이 합작 공장 진출을 강요받고 있습니다. Strata Manufacturing은 생산량을 38% 늘려 에어버스와 보잉의 각 기종용 구조 부품을 11,774개 수출하고 있으며, 이는 걸프 국가들이 복합재의 주요 생산지가 되기를 목표로 하고 있음을 보여줍니다. 한화항공우주가 GE 및 롤스로이스용 부품 생산을 위해 베트남에 신설한 10만 m² 규모의 공장도 이러한 변화를 뒷받침합니다.
유럽은 에어버스의 생산 속도에 힘입어 친환경 소재에 주력하고 있습니다. 에어버스가 헬리콥터 페어링용으로 실시하고 있는 바이오 탄소섬유의 실용성 시험은 탄소 중립 공급망을 향한 초기 노력이라고 할 수 있습니다. 일본은 고품질 탄소섬유 공급처로서 틈새 시장을 유지하고 있으며, 미쓰비시 케미칼은 향후 모빌리티 프로그램에서 복합재료 매출을 12% 늘리는 것을 목표로 하고 있습니다. 한편, 중동 및 아프리카 시장은 자유무역지대 및 장거리 노선과의 근접성을 활용해 OEM으로부터 오프셋 프로젝트를 수주하고 있습니다. 그러나 유럽 및 미국의 동종 업계 경쟁사와 동등한 인증 기준을 달성하는 것은 여전히 지속적인 과제로 남아 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the aircraft fairings market size was valued at USD 1.96 billion in 2025 and estimated to grow from USD 2.09 billion in 2026 to reach USD 2.91 billion by 2031, at a CAGR of 6.82% during the forecast period (2026-2031).
This report is Segmented by Application (Fuselage, Landing Gear, Wings, Control Surfaces, and Engine), Material (Glass-Fiber Composites, Metal Alloys, Thermoplastic Composites, and More), Aircraft Type (Commercial, Military, and More), Sales Channel (OEM Production and Aftermarket MRO), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Aircraft Fairings Market Trends and Insights
Surging Composite Adoption to Meet Fuel-Efficiency Targets
Airlines under acute fuel-cost pressure are switching from aluminum to CFRP fairings, lifting composite content on next-generation aircraft from 13% on legacy A330s to more than 50% today. Airbus' Multifunctional Fuselage Demonstrator shows that thermoplastic skins can cut a further 10% weight while supporting automated welding for 100-per-month build rates. Economic benefits remain compelling: lifetime fuel savings can offset 15-20% of an aircraft's purchase price when installed composite fairings. Yet this transition demands heavy capital outlays for autoclaves, robotic lay-up cells, and specialized labor, heightening entry barriers and prompting OEMs to favor partners owning mature composite ecosystems
Rapid Fleet-Wide Replacement of Aging Aircraft
More than 700 jets retire yearly, triggering component harvesting and refurbishment demand that enlarges the retrofit market. Wide-body fairings see sharper wear from long-haul cycles, pushing operators toward aerodynamic upgrade kits rather than new-build orders amid delivery delays. Circular-economy programs that reclaim composite fairings for secondary markets, exemplified by Sumitomo's tie-up with Werner Aero, are gaining traction but face the hard reality that CFRP recycling is limited and cost-intensive.
High and Volatile Prices of Carbon-Fiber, Epoxy, and High-Temperature Resins Compress Supplier Margins
Carbon-fiber demand in aerospace is projected to grow 17% annually, but capacity additions require expensive, long-cycle investments. Geopolitical tension and tariff exposure complicate price forecasting, prompting suppliers to adopt cost-plus contracts yet forcing smaller firms into untenable working-capital positions.
Other drivers and restraints analyzed in the detailed report include:
- Hybrid-Electric Aircraft Programs Spur New Fairing Designs
- Record Commercial Single-Aisle Backlog Underpins Production Visibility
- Stringent Certification Cycles Delaying New Fairing Technologies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fuselage fairings generated 32.84% of the aircraft fairings market size in 2025, thanks to their complex wing-body junction geometries and high OEM integration hurdles. Demand remains sticky because any design change obliges full aerodynamic retesting, making incumbent suppliers difficult to displace. Landing-gear fairings are accelerating at 6.94% CAGR, propelled by tighter airport noise limits and eVTOL program requirements for retractable struts. Wing-body and control-surface fairings stay aligned with mainstream build rates, whereas engine fairings pick up incremental growth from hybrid-electric demonstrators that mandate cooled fairing shells.
Emerging mobility platforms skew design briefings toward rapid manufacturing. Wichita State University's research shows UAV operators prefer printable modular fairings in days, not weeks. Deutsche Aircraft's D328eco contract bundling fuselage and landing-gear doors into a single award underlines OEM moves toward integrated supplier packages. Such bundling favors vendors with broad design toolsets and test-article capacity.
CFRP's 62.78% share underscores its entrenched status across wide-body, narrow-body, and even rotorcraft programs. Yet thermoplastic composites and additively manufactured polymers-growing 8.86% annually-remove autoclave bottlenecks and enable part-count consolidation that slashes assembly labor. For lightweight UAV fairings, cost sensitivity keeps glass fiber viable, while critical damage-tolerant locations (such as lower fuselage chine panels) still rely on aluminum-lithium alloys.
Hexcel's HexAM PEKK-laser-sintering platform prints complex fairing brackets that are impossible to machine conventionally, cutting scrap and weight simultaneously. EU-funded DOMMINIO efforts extend this digital thread by embedding structural-health sensors into thermoplastic fairings, bringing predictive integrity monitoring directly to line-fit installations. Over time, blended material stacks that mate laminated CFRP skins to printed thermoplastic ribs could dominate the aircraft fairings market.
Complete Report Scope:
- By Application
- Fuselage
- Landing Gear
- Wings
- Control Surfaces
- Engine
- By Material
- Carbon-Fiber Reinforced Polymer (CFRP)
- Glass-Fiber Composites
- Metal Alloys
- Thermoplastic Composites
- Additively-Manufactured Thermoplastics
- By Aircraft Type
- Commercial
- Narrow-Body Commercial Aircraft
- Wide-Body Commercial Aircraft
- Military
- Combat
- Non-Combat
- General Aviation
- Unmanned Systems
- Commercial
- By Sales Channel
- OEM Production
- Aftermarket MRO
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America captured 36.24% of the aircraft fairings market share in 2025, supported by Boeing's production recovery and a USD 1 billion GE Aerospace manufacturing commitment that boosts composite capacity in multiple US states. Long-established clusters in Washington and South Carolina give suppliers a mature ecosystem, although tariff policies and skilled-labor gaps continue to strain cost bases. RTX's USD 2 billion facilities expansion highlights OEM faith in sustained demand even as the near-term operating environment remains inflationary.
Asia-Pacific is the fastest-growing region, showing 8.51% CAGR to 2031. Indigenous programs such as China's C919 or India's HTT-40 intensify localization mandates, drawing Western tier-1s into joint-venture factories. Strata Manufacturing recorded 38% output growth, exporting 11,774 structures across Airbus and Boeing models, signaling the Gulf's ambition to become a composites powerhouse. Hanwha Aerospace's new 100,000 m2 Vietnam site for GE and Rolls-Royce components further validates the shift.
Europe benefits from Airbus' production tempo and focuses on green materials. Airbus' bio-based carbon-fiber feasibility trials for helicopter fairings mark early steps toward carbon-neutral supply chains. Japan preserves a niche as a high-grade carbon-fiber supplier, with Mitsubishi Chemical targeting 12% composite growth on future mobility programs. Meanwhile, Middle East and Africa markets leverage free-trade zones and proximity to long-haul routes to win offset work from OEMs. However, achieving certification parity with Western peers remains an ongoing task.
- Airbus Aerostructures (Airbus SE)
- Boeing Aerostructures Australia (The Boeing Company)
- Collins Aerospace (RTX Corporation)
- FACC AG
- GKN Aerospace
- Spirit AeroSystems, Inc.
- Saab AB
- Strata Manufacturing PJSC
- LATECOERE S.A
- Kaman Corporation
- CTRM Sdn. Bhd.
- ShinMaywa Industries, Ltd.
- Royal Engineered Composites
- FDC Composites Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging composite adoption to meet fuel-efficiency targets
- 4.2.2 Rapid fleet-wide replacement of aging aircraft
- 4.2.3 Proliferation of UAV, advanced air mobility, and eVTOL platforms
- 4.2.4 Growth of aftermarket MRO expenditure on replacement fairings
- 4.2.5 Hybrid-electric aircraft programs spur new fairing designs
- 4.2.6 Record commercial single-aisle backlog underpins production visibility
- 4.3 Market Restraints
- 4.3.1 High and volatile prices of carbon fiber, epoxy, and high-temperature resins
- 4.3.2 Stringent certification cycles delaying new fairing technologies
- 4.3.3 Supply-chain consolidation reducing sourcing optionality and compressing margins
- 4.3.4 Geopolitical trade tensions and tariffs inflating raw-material costs
- 4.4 Value Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Fuselage
- 5.1.2 Landing Gear
- 5.1.3 Wings
- 5.1.4 Control Surfaces
- 5.1.5 Engine
- 5.2 By Material
- 5.2.1 Carbon-Fiber Reinforced Polymer (CFRP)
- 5.2.2 Glass-Fiber Composites
- 5.2.3 Metal Alloys
- 5.2.4 Thermoplastic Composites
- 5.2.5 Additively-Manufactured Thermoplastics
- 5.3 By Aircraft Type
- 5.3.1 Commercial
- 5.3.1.1 Narrow-Body Commercial Aircraft
- 5.3.1.2 Wide-Body Commercial Aircraft
- 5.3.2 Military
- 5.3.2.1 Combat
- 5.3.2.2 Non-Combat
- 5.3.3 General Aviation
- 5.3.4 Unmanned Systems
- 5.3.1 Commercial
- 5.4 By Sales Channel
- 5.4.1 OEM Production
- 5.4.2 Aftermarket MRO
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Airbus Aerostructures (Airbus SE)
- 6.4.2 Boeing Aerostructures Australia (The Boeing Company)
- 6.4.3 Collins Aerospace (RTX Corporation)
- 6.4.4 FACC AG
- 6.4.5 GKN Aerospace
- 6.4.6 Spirit AeroSystems, Inc.
- 6.4.7 Saab AB
- 6.4.8 Strata Manufacturing PJSC
- 6.4.9 LATECOERE S.A
- 6.4.10 Kaman Corporation
- 6.4.11 CTRM Sdn. Bhd.
- 6.4.12 ShinMaywa Industries, Ltd.
- 6.4.13 Royal Engineered Composites
- 6.4.14 FDC Composites Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


