

|
시장보고서
상품코드
2123417
항공기 전기 시스템 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Aircraft Electrical Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
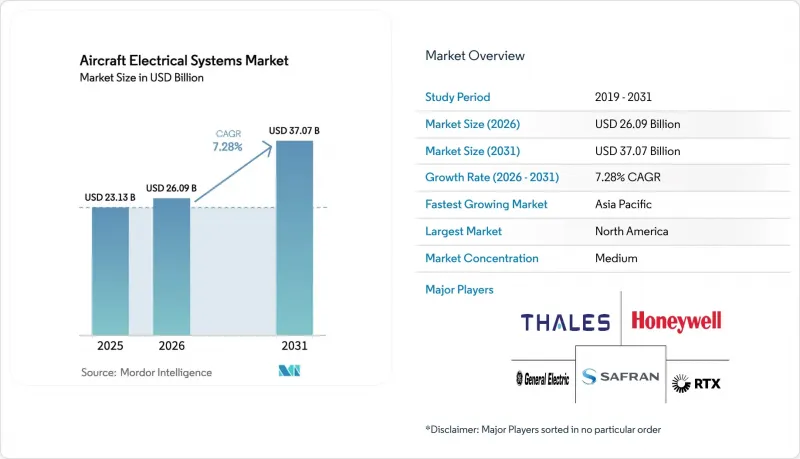
에 의하면, 항공기 전기 시스템 시장 규모는 2025년 231억 3,000만 달러에서 2026년에는 260억 9,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 7.28%로 성장을 지속하여, 2031년까지 370억 7,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 시스템별(발전, 배전 등), 구성품별(발전기 및 스타터 제너레이터, 컨버터 등), 플랫폼별(민간 항공, 군용 항공 등), 용도별(발전 관리, 객실 시스템 등), 지역별(북미, 유럽 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 항공기 전기 시스템 시장 동향 및 인사이트
MEA 아키텍처 채택 확대
각 항공사는 MEA 레이아웃을 선호하고 있습니다. 이는 가압 및 제빙을 위해 엔진의 블리드 에어를 사용할 필요가 없어짐으로써, 20년간의 기체 수명 주기 전체에 걸쳐 트윈 아일 노선의 연료 소비량을 3-5% 절감할 수 있기 때문입니다. B787 및 A350이 길을 열었으며, 다음 단계에서는 중앙 집중식 유압 시스템을 완전히 배제하는 전기 기계식 주 비행 제어 액추에이터의 실현을 목표로 하고 있습니다. 콜린스 에어로스페이스(Collins Aerospace)의 HECATE 프로그램은 2024년에 500kW급 하이브리드 전기 시스템의 실증에 성공하여, 분산형 전기 모터가 상승 시에는 터보팬 엔진을 보조하고, 하강 시에는 전력을 회수할 수 있음을 입증했습니다. 이러한 아키텍처에는 250kVA를 초과하는 스타터-제너레이터와 200°C 이상의 온도에서 작동 가능한 SiC MOSFET을 이용한 솔리드 스테이트 전력 컨트롤러가 필요합니다. MEA를 통한 개조는 기존 업그레이드에 비해 자본 비용을 15-20% 증가시키지만, 유압작동유의 오염 위험을 줄임으로써 전체 수명 주기 동안 순비용 절감을 실현합니다. 절연 및 굽힘 반경에 관한 SAE AS50881 표준을 준수함으로써, 고전압 하네스가 기존 구조와의 호환성을 유지함을 보장합니다.
증가하는 항공기 생산 대수와 기존 수주 잔고
에어버스는 2024년 말 기준으로 8,658대의 미인도 주문을 보유하고 있으며, 이는 약 11년 치 생산량에 해당합니다. 이에 따라 발전기, 배전 장치 및 협폭기 1대당 180킬로미터에 달하는 배선에 대한 지속적인 수요가 보장되고 있습니다. 보잉은 2024년에 B737 MAX의 생산량을월38대까지 늘리고, 2026년 중반까지 42대에 도달하는 것을 목표로 하고 있으며, 각 기체에는 15-20개의 배전 모듈이 필요합니다. COMAC은 2028년까지 연간 150대의 C919를 인도하는 것을 목표로 하고 있으며, 이미 핍박하고 있는 세계 공급 기반 속에서 아시아태평양의 전기 시스템 수요를 더욱 끌어올릴 전망입니다. 인도 바도다라에 위치한 타타 에어버스(Tata Airbus)의 C295 생산 라인은 MIL-STD-704F 규격을 준수하는 군용 등급의 발전 기능을 갖추고 있습니다. 반도체 패키징의 병목 현상으로 리드 타임이 길어지고 있지만, 각 OEM 업체들은 현재 최종 조립 지연을 방지하기 위해 발전기 하우징과 SiC 디바이스를 듀얼 소스화하고 있습니다.
시스템 전압 수준 상승에 따른 열 관리 및 배선 복잡화라는 과제
270V를 초과하는 HVDC 버스에서는 SiC 소자가 1암페어당 2-3와트의 열을 방출하는 국부적인 핫스팟이 발생하기 때문에 관리 전력 1kW당 최대 12Kg에 달하는 견고한 방열판이 필요합니다. 액체 냉각 루프는 열 성능을 향상시키지만, 누출 위험이 발생할 뿐만 아니라 FAA Part 25 규정을 준수하는 단일 고장 허용성을 유지하기 위해 펌프를 이중화해야 합니다. HVDC 배선용의 더 두꺼운 가교 폴리에틸렌 절연체로 인해 케이블 다발의 직경이 20-25% 증가하여, 당초 115볼트 케이블용으로 설계된 스퍼를 통과하는 배선 경로가 복잡해집니다. 고주파 스위칭 노이즈를 해결하기 위해 차폐된 트위스트 페어 케이블과 페라이트 필터를 사용해야 하며, 그 결과 전기 베이당 3-5kg의 무게가 증가합니다. 그래핀으로 강화된 인터페이스 패드는 열전도성을 향상시키지만, 진동으로 인해 열화되므로 5,000 비행 시간마다 교체해야 하며, 그 결과 수명 주기 비용이 증가합니다. SAE AS5692에 규정된 아크 고장 차단기는 배선 화재를 방지하지만, 여전히 오작동이 발생하고 있어 가동률이 높은 항공사에게는 용납할 수 없는 빈도로 운항 신뢰성을 저하시키고 있습니다.
부문 분석
에너지 저장 시스템은 2031년까지 연평균 성장률(CAGR) 9.44%를 나타낼 것으로 예측되며, 이는 항공기 전기 시스템 시장 내 시스템 카테고리 중 가장 높은 성장률입니다. 이러한 성장 가속화는 Joby사의 에어 택시나 Lilium사의 전기 제트기 등 eVTOL 신규 진출기업들 덕분입니다. 이들 모두 AC 20-184의 격리 규정을 준수하는 대형 리튬 이온 배터리 팩을 탑재하고 있으며, 시제품 단계에서 양산 단계로 전환되고 있습니다. 2025년 시점에서 전력 분배는 34.41%의 점유율을 유지하고 있으며, 이는 협폭기 및 광폭기 기단에 내결함성 버스가 도입되고 있는 실태를 반영합니다. 구형 항공기의 개조 기회가 감소함에 따라 성장은 둔화되겠지만, 예비 부품 및 업그레이드 수요로 인해 전력 분배와 관련된 항공기 전기 시스템 시장 규모는 여전히 크고 있습니다.
고정 주파수 및 가변 주파수 발전기를 포함한 발전 모듈은 계속해서 기본 부하를 처리하고 있지만, 택싱 중에 배터리 팩을 활용하는 하이브리드 아키텍처로 대체되고 있습니다. 전력 변환 장치는 HVDC 1차 버스와 28볼트 2차 항공전자 레일 간의 전압 변환을 가능하게 하며, 항공우주 규격을 준수하는 컨버터는 현재 1kW/in3의 전력 밀도에서 95%의 효율을 달성하고 있습니다. 하강 시 에너지를 회수하는 양방향 컨버터는 NASA의 X-57 및 에어버스의 E-Fan X에서 시험되고 있는 분산형 추진 개념을 뒷받침하고 있습니다. SAE ARP4754B에 기반한 인증 체계가 성숙해짐에 따라, 에너지 저장 및 전력 변환 부문은 항공기 전기 시스템 시장에서 지속적인 시장 점유율 확대가 예상됩니다.
배터리 팩과 BMS는 eVTOL의 인증 이정표와 높은 신뢰성의 에너지 저장이 필요한 하이브리드 전기식 실증기를 견인하는 역할을 하며, 연평균 성장률(CAGR) 8.24%로 확대될 것으로 예측됩니다. 발전기 및 스타터 제너레이터는 노후화된 터보팬 항공기군의 교체 수요에 힘입어 2025년에도 23.22%의 점유율을 유지했습니다. 그러나 항공사들이 지상 운영에 전력을 공급하고 연료 소비를 줄이기 위해 보조 배터리 유닛을 선호하는 경향이 있어 성장이 정체되고 있습니다.
SiC 솔리드 스테이트 접촉기를 포함한 배전 장치에는 고장 발생 500시간 전에 마모를 예측하는 예측 유지보수 모니터링 기능이 통합되어 있습니다. 컨버터는 회생 모드를 위해 양방향 전력 흐름을 제공하며, 알루미늄 배선은 구리 피복 단자를 통해 전도성을 유지하면서 하네스의 질량을 30% 줄입니다. 5만 회 결합 사이클을 지원하는 커넥터는 고주파수로 운용되는 시험기에서도 신뢰성을 확보하며, 전력 분배 소프트웨어에는 사이버 보안 표준 DO-326A를 준수하는 펌웨어가 기본으로 탑재되어 있습니다. 이러한 동향들이 맞물려 항공기 전기 시스템 시장 내 부품의 다양화를 촉진하고 있습니다.
지역별 분석
아시아태평양은 COMAC의 C919 양산 확대, 에어버스의 톈진 A320 생산 라인, 그리고 인도의 타타-에어버스 C295 프로그램에 힘입어 2031년까지 연평균 성장률(CAGR) 8.01%를 기록할 전망이며, 이는 항공기 전기 시스템 시장에서 지역별 가장 높은 성장률입니다. 북미는 2025년 기준 42.22%의 점유율을 유지하고 있으며, 보잉의 에버렛 및 렌턴 거점, 록히드 마틴의 F-35 시설, 그리고 시애틀, 위치타, 피닉스에 걸쳐 형성된 밀집된 Tier 1 생태계를 활용하는 형태를 띠고 있습니다. 유럽은 함부르크와 툴루즈에 위치한 에어버스 허브 기지의 혜택을 받고 있으며, 와이드바디 기단 개조에 대한 수요가 견조하게 유지되고 있습니다.
중동의 항공사들은 최신형 와이드바디 기종을 중심으로 기단을 운영하고 있으며, 고출력 기내 연결 시스템 업그레이드를 구매함으로써 지역 내 전기 시스템 관련 수익을 끌어올리고 있습니다. 남미 시장은 엠브라에르의 E2 시리즈가 주를 이루며, 여전히 규모는 작지만 구형 ERJ-145 기단에 대한 애프터마켓 개조가 꾸준한 수요를 이끌고 있습니다. 아프리카 시장은 규모는 작지만 성장을 지속하고 있으며, 에티오피아 항공은 ICAO 부속서 6의 전기 안전 요건을 준수하기 위해 혼합 기단의 현대화를 추진하고 있습니다. OEM 오프셋 및 현지 생산이 아시아와 중동으로 확대됨에 따라, 지리적 분산화를 통해 항공기 전기 시스템 시장의 세계 공급망 회복력이 강화되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the aircraft electrical systems market size is expected to grow from USD 23.13 billion in 2025 to USD 26.09 billion in 2026 and is forecasted to reach USD 37.07 billion by 2031 at a 7.28% CAGR over 2026-2031.
This report is Segmented by System (Power Generation, Power Distribution, and More), Component (Generators and Starter-Generators, Converters, and More), Platform (Commercial Aviation, Military Aviation, and More), Application (Power Generation Management, Cabin Systems, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Aircraft Electrical Systems Market Trends and Insights
Increasing Adoption of MEA Architecture
Airlines favor MEA layouts because eliminating engine-bleed air for pressurization and ice protection trims fuel burn by 3-5% on twin-aisle routes across each twenty-year airframe lifecycle. The B787 and A350 paved the way, and the next step targets electromechanical primary flight-control actuators that remove centralized hydraulics altogether. Collins Aerospace's HECATE program validated a 500-kilowatt hybrid-electric system in 2024, proving that distributed electric motors can assist turbofans during climb and regenerate power during descent. Such architectures require starter-generators exceeding 250 kVA and solid-state power controllers utilizing SiC MOSFETs that can operate at temperatures exceeding 200 °C. Although MEA retrofits increase capital costs by 15-20% over conventional upgrades, they deliver net lifecycle savings by mitigating hydraulic-fluid contamination risk. Compliance with SAE AS50881 on insulation and bend radii ensures that high-voltage harnesses remain compatible with legacy structures.
Rising Aircraft Production Volume and Existing Aircraft Production Backlog
Airbus closed 2024 with 8,658 aircraft on order, equivalent to approximately eleven years of production, guaranteeing recurring demand for generators, power-distribution units, and 180 kilometers of wiring per narrowbody airframe. Boeing plans to increase B737 MAX production to 38 jets per month in 2024 and aims to reach 42 by mid-2026, with each aircraft requiring 15-20 power-distribution modules. COMAC aims to deliver 150 C919s per year by 2028, adding to Asia-Pacific electrical-system demand on an already tight global supply base. India's Tata-Airbus C295 line in Vadodara features military-grade power-generation capabilities that meet MIL-STD-704F specifications. Although semiconductor packaging bottlenecks lengthen lead times, OEMs now dual-source generator housings and SiC devices to prevent delays in final assembly.
Challenges in managing heat and wiring complexity as system voltage levels increase
HVDC buses above 270 volts create localized hotspots where SiC devices dissipate 2-3 W per ampere, requiring robust heat sinks that add up to 12 kg per kilowatt of managed power. Liquid-cooling loops enhance thermal performance but introduce leak risks and duplicate pumps to maintain single-failure tolerance in accordance with FAA Part 25 rules. Thicker cross-linked polyethylene insulation for HVDC wiring increases the bundle diameter by 20-25%, complicating routing through spars that were initially sized for 115-volt cabling. High-frequency switching noise necessitates the use of shielded twisted pairs and ferrite filters, resulting in an additional 3-5 kg per electrical bay. Graphene-enhanced interface pads improve heat transfer but degrade under vibration and must be replaced every 5,000 flight hours, thereby increasing the life-cycle cost. Arc-fault interrupters, as specified in SAE AS5692, prevent wiring fires; however, false trips still disrupt dispatch reliability at rates unacceptable to high-utilization carriers.
Other drivers and restraints analyzed in the detailed report include:
- Implementation of HVDC Distribution Systems
- Growing Need for Lightweight and Compact Electrical Systems for Unmanned Aerial Platforms
- High certification costs associated with advanced aerospace battery technologies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Energy storage systems are expected to grow at a 9.44% CAGR through 2031, the fastest rate among system categories in the aircraft electrical systems market. The acceleration comes from eVTOL entrants such as Joby's air taxi and Lilium's electric jet, both of which are transitioning from prototype to production with large Li-ion packs that comply with AC 20-184 containment rules. Power distribution retained a 34.41% share in 2025, reflecting an installed base of fault-tolerant buses on narrowbody and widebody fleets. Growth moderates as retrofit opportunities on legacy aircraft taper, yet the aircraft electrical systems market size attached to power distribution remains significant for spares and upgrades.
Power generation modules, including constant-frequency and variable-frequency generators, continue to serve baseline loads but are being displaced by hybrid architectures that leverage battery packs during taxi. Power conversion units enable voltage translation between HVDC primary buses and 28-volt secondary avionics rails, with aerospace-qualified converters now achieving 95% efficiency at a power density of 1 kW/in3. Bidirectional converters that recuperate energy during descent support distributed-propulsion concepts being tested on NASA's X-57 and Airbus's E-Fan X. As certification frameworks under SAE ARP4754B mature, energy storage and power conversion segments look set for sustained share gains within the aircraft electrical systems market.
Battery packs and BMS are forecast to expand at an 8.24% CAGR, driven by eVTOL certification milestones and hybrid-electric demonstrators that demand high-reliability energy storage. Generators and starter-generators maintained a 23.22% share in 2025, underpinned by replacement demand in aging turbofan fleets. Yet growth plateaus as airlines favor auxiliary battery units that power ground operations and reduce fuel burn.
Power distribution units, including SiC solid-state contactors, integrate prognostic health monitoring that predicts wear 500 hours ahead of failure. Converters provide bidirectional power flow for regenerative modes, and aluminum wiring reduces harness mass by 30% while maintaining conductivity via copper-clad terminations. Connectors rated for 50,000 mating cycles ensure reliability on high-frequency test vehicles, and DO-326A cyber-secure firmware is standard in power-distribution software. Together, these trends reinforce component diversification inside the aircraft electrical systems market.
Complete Report Scope:
- By System
- Power Generation
- Power Distribution
- Power Conversion
- Energy Storage
- By Component
- Generators and Starter-Generators
- Power Distribution Units
- Converters
- Battery Packs and Battery Management System (BMS)
- Wiring and Cables
- Connectors and Contactors
- Power-distribution Software
- By Platform
- Commercial Aviation
- Narrowbody
- Widebody
- Regional Jets
- Freighters
- Military Aviation
- Combat Aircraft
- Transport Aircraft
- Unmanned Aerial Vehicles (UAVs)
- Trainer Aircraft
- General Aviation
- Business Jets
- Helicopters
- Electric Vertical Take-Off and Landing (eVTOL)/Advanced Air Mobility (AAM)
- Commercial Aviation
- By Application
- Power Generation Management
- Flight Control and Operation
- Cabin System
- Configuration Management
- Air Pressurization and Conditioning
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific is poised to post an 8.01% CAGR through 2031, the highest regional rate in the aircraft electrical systems market, supported by COMAC's C919 ramp, Airbus's Tianjin A320 line, and India's Tata-Airbus C295 program. North America retained a 42.22% share in 2025, leveraging Boeing's Everett and Renton centers, Lockheed Martin's F-35 facility, and a dense Tier-1 ecosystem across Seattle, Wichita, and Phoenix. Europe benefits from Airbus hubs in Hamburg and Toulouse, and sees consistent demand for retrofits of its widebody fleets.
Middle East carriers operate young, widebody heavy fleets, purchasing high-power cabin connectivity upgrades that boost regional electrical system revenues. South America remains modest, anchored by Embraer's E2 line, but aftermarket retrofits on older ERJ-145 fleets add steady pull. Africa's market is small yet growing, as Ethiopian Airlines modernizes its mixed fleets to comply with ICAO Annex 6 electrical safety mandates. As OEM offsets and localized manufacturing spread across Asia and the Middle East, geographic diversification strengthens global supply chain resilience within the aircraft electrical systems market.
- RTX Corporation
- Honeywell International Inc.
- General Electric Company
- Safran S.A.
- Thales Group
- Amphenol Aerospace
- Astronics
- Crane Aerospace and Electronics
- AMETEK Inc.
- Nabtesco Corporation
- Hartzell Engine Tech LLC
- PBS AEROSPACE Inc.
- Acme Aerospace Inc. & Avionic Instruments, LLC
- BAE Systems plc
- Moog Inc.
- Parker-Hannifin Corporation
- Rolls-Royce plc
- Vicor Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing adoption of More-Electric Aircraft (MEA) architectures to reduce mechanical complexity and improve efficiency
- 4.2.2 Rising aircraft production volumes and sustained order backlogs driving demand for advanced electrical systems
- 4.2.3 Implementation of high-voltage direct current (HVDC) distribution systems to support next-generation power architectures
- 4.2.4 Growing need for lightweight and compact electrical systems tailored to unmanned aerial platforms
- 4.2.5 Silicon-carbide (SiC) power electronics enable higher temperature limits
- 4.2.6 Retrofit-driven upgrades focused on cabin electrification, including in-seat power and galley modernization
- 4.3 Market Restraints
- 4.3.1 Challenges in managing heat and wiring complexity as system voltage levels increase
- 4.3.2 High certification costs associated with advanced aerospace battery technologies
- 4.3.3 Limited availability of qualified semiconductors meeting aerospace-grade performance and reliability standards
- 4.3.4 Delays in regulatory approvals for software-driven power distribution units due to cybersecurity concerns
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By System
- 5.1.1 Power Generation
- 5.1.2 Power Distribution
- 5.1.3 Power Conversion
- 5.1.4 Energy Storage
- 5.2 By Component
- 5.2.1 Generators and Starter-Generators
- 5.2.2 Power Distribution Units
- 5.2.3 Converters
- 5.2.4 Battery Packs and Battery Management System (BMS)
- 5.2.5 Wiring and Cables
- 5.2.6 Connectors and Contactors
- 5.2.7 Power-distribution Software
- 5.3 By Platform
- 5.3.1 Commercial Aviation
- 5.3.1.1 Narrowbody
- 5.3.1.2 Widebody
- 5.3.1.3 Regional Jets
- 5.3.1.4 Freighters
- 5.3.2 Military Aviation
- 5.3.2.1 Combat Aircraft
- 5.3.2.2 Transport Aircraft
- 5.3.2.3 Unmanned Aerial Vehicles (UAVs)
- 5.3.2.4 Trainer Aircraft
- 5.3.3 General Aviation
- 5.3.3.1 Business Jets
- 5.3.3.2 Helicopters
- 5.3.3.3 Electric Vertical Take-Off and Landing (eVTOL)/Advanced Air Mobility (AAM)
- 5.3.1 Commercial Aviation
- 5.4 By Application
- 5.4.1 Power Generation Management
- 5.4.2 Flight Control and Operation
- 5.4.3 Cabin System
- 5.4.4 Configuration Management
- 5.4.5 Air Pressurization and Conditioning
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 France
- 5.5.2.3 Germany
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 RTX Corporation
- 6.4.2 Honeywell International Inc.
- 6.4.3 General Electric Company
- 6.4.4 Safran S.A.
- 6.4.5 Thales Group
- 6.4.6 Amphenol Aerospace
- 6.4.7 Astronics
- 6.4.8 Crane Aerospace and Electronics
- 6.4.9 AMETEK Inc.
- 6.4.10 Nabtesco Corporation
- 6.4.11 Hartzell Engine Tech LLC
- 6.4.12 PBS AEROSPACE Inc.
- 6.4.13 Acme Aerospace Inc. & Avionic Instruments, LLC
- 6.4.14 BAE Systems plc
- 6.4.15 Moog Inc.
- 6.4.16 Parker-Hannifin Corporation
- 6.4.17 Rolls-Royce plc
- 6.4.18 Vicor Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


