|
시장보고서
상품코드
2123547
생명과학 시약 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Life Science Reagents - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
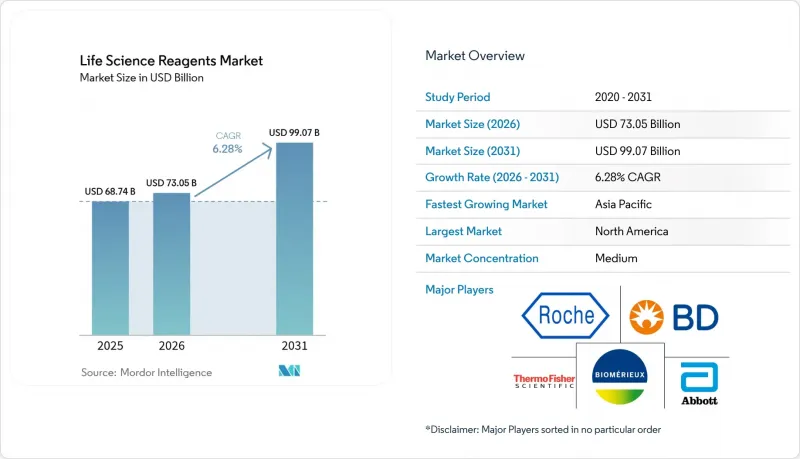
에 의하면, 생명과학 시약 시장 규모는 2025년에 687억 4,000만 달러로 평가되었고, 2026년 730억 5,000만 달러에서 2031년까지 990억 7,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.28%를 나타낼 전망입니다.
본 보고서는 제품 유형별(세포·조직 배양 시약, 크로마토그래피 시약 등), 최종 사용자별(병원 및 진단실험실 등), 용도별(임상 진단, 신약 개발·의약품 개발 등), 형태별(액체 시약, 동결건조 시약, 기타), 지역별(북미 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 생명과학 시약 시장 동향 및 인사이트
감염병으로 인한 막대한 부담
세계적인 감염병 유행으로 인해 분자진단 및 면역 측정용 시약 수요는 높은 수준을 유지하고 있습니다. FDA의 유연한 긴급 사용 지침에 따라 검증된 신속 대응 키트 시장 진입이 가속화되고 있으며, 이는 즉시 생산 규모를 확대할 수 있는 플랫폼을 보유한 공급업체에 우위를 가져다주고 있습니다. 자원이 제한된 지역에서 포인트 오브 케어 시스템이 도입됨에 따라 접근성은 확대되고 있지만, 물류 및 가격 책정과 관련된 과제는 여전히 남아 있습니다. 시약을 소형 검출 장치와 세트로 판매할 수 있는 제조업체는 현장 도입을 간소화함으로써 시장 점유율을 확대되고 있습니다. 항생제 내성에 대한 지속적인 모니터링으로 인해, 새로운 병원체 검출에 적합한 고처리량 PCR 마스터믹스 및 선택적 배양 배지에 대한 수요가 증가하고 있습니다.
유전체학 및 단백체학 분야의 기술적 진보
단일 세포 시퀀싱과 공간 단백질체학는 시약 성능에 있어 새로운 기준을 확립해 가고 있습니다. 일루미나(Illumina)의 풀렌트 바이오사이언스(Fluent Biosciences) 인수는 확장 가능한 멀티오믹스 워크플로우에 대한 전략적 투자를 강조하는 것이며, 공급업체들에게 로트 간 반응 속도가 안정적인 초저투여량 효소를 제공하도록 요구하고 있습니다. 자율형 실험실과 통합 가능한 자동화 대응 버퍼 시스템을 통해 연구개발 주기가 500일 이상 단축되고, 시약 낭비가 감소하는 동시에 프리미엄 SKU의 매출이 향상되었습니다. 장비 제조업체와 공동으로 키트를 개발할 수 있는 공급업체는 확대되는 도입 기반에서 우선 공급업체로서의 입지를 확고히 하고 있습니다.
특수 시약의 높은 비용과 가격 압박
GMP 등급의 CRISPR 구성 요소는 연구용 제품에 비해 5-10배의 비용이 들 수 있어, 예산 제약이 있는 바이오테크 기업의 도입을 저해하고 있습니다. Casgevy 요법의 220만 달러라는 가격 책정은 시약비가 최종 치료비에 어떻게 반영되는지를 여실히 보여줍니다. 로터스에서 플라토로 이어지는 가격 변동 추세는 일괄 구매를 촉진하지만, 효소 및 항체 공급업체 간의 통합으로 인해 소규모 구매자의 협상력은 약화되고 있습니다. 인간 혈소판 용해액의 90%를 대체하는 신흥 식물 유래 세포 배양 보충제는 비용 절감의 길을 제시하고 있으나, 보다 광범위한 검증이 필요합니다.
부문 분석
2025년, 세포 및 조직 배양 시약은 생명과학 시약 시장 점유율의 29.68%를 차지했으며, 바이오 제조 워크플로우에서 필수적이라는 점에 힘입어 선두 위치를 유지했습니다. 이 부문은 변동성과 면역원성을 억제하는 화학적으로 정의된 이종 유래 성분을 포함하지 않는 배지로의 지속적인 전환의 혜택을 받고 있습니다. 로트제약 등의 기업은 제품 간 편차를 최소화하는 무혈청 줄기세포 배지를 개발하여, 재생의학 파이프라인에서 고가대의 정가를 실현하고 있습니다. 크로마토그래피 시약은 항체 정제 수요에 힘입어 안정적인 수익을 올리고 있는 반면, 임상화학 패널은 검사실 자동화로 인해 판매량이 증가하고 있습니다. 분자진단 시약은 연평균 성장률(CAGR) 7.05%가 예상되며, 액체 생검, NGS 라이브러리 준비, 마이크로RNA 검출 프로토콜의 확대에 따라 다른 분야를 능가하는 성장을 이루고 있습니다.
분자진단의 급속한 성장은 정밀 종양학이 시약의 복잡성을 얼마나 높이고 있는지를 보여줍니다. 시퀀싱 비용의 하락으로 인해 소규모 병원 및 검사 기관이 새로운 고객으로 진입하고 있습니다. 단일 튜브 라이브러리 구축용 복합 효소 혼합물은 작업 시간을 대폭 단축하고 오류율을 낮춤으로써 브랜드 차별화를 강화하고 있습니다. 신흥 CRISPR, 마이크로바이옴, 공간 생물학 키트는 ‘기타 제품 유형’ 카테고리를 차지하고 있으며, 이는 생명과학 시약 업계에서 급속한 연구 개발이 기존의 카탈로그 구조를 어떻게 뛰어넘고 있는지를 보여줍니다.
2025년에는 병원과 진단 검사 기관이 생명과학 시약 시장 규모의 54.05%를 차지했으나, 2026-2031년 제약 회사 및 생명공학 기업이 7.12%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. 바이오의약품 파이프라인이 활성화됨에 따라 기업들은 그동안 외부에 위탁하던 분석 업무를 사내에서 처리하게 되었으며, 이로 인해 고순도 성장 인자, 수지 세트, 동반 진단 키트의 구매가 촉진되고 있습니다. 애브비(AbbVie)사의 2,177억 4,000만 달러 규모의 연구개발(R&D) 예산은 업스트림 공정 시약에 대한 투자가 치료법 개발에 대한 의지와 병행되고 있음을 여실히 보여줍니다. 자동화가 진행된 병원 검사실에서는 조달과 품질 관리를 통합할 수 있는 시약 및 장비 통합 패키지가 선호되고 있습니다.
학술 기관은 국가 보조금의 지원을 받아 계속해서 신뢰할 수 있는 고객입니다. NIH(미국 국립보건원)의 연간 410억 달러 지출은 신약 개발 등급의 프라이머, 항체, 리포터 염료에 대한 기초적인 수요를 유지하며, 제품 카탈로그의 폭을 넓혀주고 있습니다. ‘기타’ 범주에 속하는 위탁 연구 기관은 유연한 로트 규모와 짧은 리드타임을 요구함으로써 대상 판매량을 확대하고 있으며, 이는 기동적인 재고 관리 알고리즘을 갖춘 유통업체에 이익을 가져다주고 있습니다.
지역별 분석
북미는 대형 제약사, 최상위권 연구 대학, 벤처 캐피털의 지원을 받는 스타트업이 밀집해 있는 것을 배경으로, 2025년에는 38.74%의 점유율로 생명과학 시약 시장 규모를 주도했습니다. ElevateBio의 13억 달러 자금 조달로 대표되는 대규모 시리즈 C 라운드를 통해, 거시경제의 변동 속에서도 세포 치료 시설에 대한 시약 공급량은 유지되고 있습니다. FDA의 규제 예측 가능성과 강력한 지적 재산권 집행 덕분에 다국적 공급업체들은 계속해서 이 지역을 대량 생산 거점으로 유지하고 있습니다.
아시아태평양은 가장 빠르게 성장하고 있으며, 중국, 일본, 한국의 각국 생명공학 기본 계획에 힘입어 연평균 성장률(CAGR) 7.29%로 확대되고 있습니다. 넉넉한 세액 공제와 파크 수준의 인프라는 현지에서 대량의 배양액과 정제 수지를 조달하는 위탁 개발 및 제조 기관(CDMO)을 유치하고 있습니다. ICH 지침과의 조화를 통해 이 지역에서 제조된 시약의 유럽 및 미국 고객에 대한 수출이 원활해졌으며, 기존에 존재하던 품질에 대한 인식의 격차가 해소되고 있습니다.
유럽에서는 ‘호라이즌 유럽’의 보조금을 통해 첨단 오믹스 및 그린 케미스트리 시약 연구에 자금이 투입되어 한 자릿수 중반대의 성장세를 유지하고 있습니다. 그러나 체외진단용 의료기기 규정(IVDR)에 따른 추가적인 규정 준수 요건으로 인해 소규모 연구소의 예산이逼迫하고 있으며, 구매 결정은 CE 및 FDA 요건을 동시에 충족하는 이중 인증 제품으로 쏠리고 있습니다.
중동 및 아프리카에서는 각국 정부가 새로운 임상 유전체학 센터를 구축함에 따라 수주가 증가하고 있는 반면, 라틴아메리카에서는 브라질의 바이오시밀러 시장 확대에 따라 GMP 등급 배지 및 크로마토그래피 솔루션에 대한 수요가 높아지고 있습니다. 신흥 지역 전체에서는 온도 편차를 견딜 수 있는 동결건조 키트가 보급되고 있어, 생명과학 시약 시장 내 제품 형태의 다양화 추세가 두드러지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the life science reagents market size was valued at USD 68.74 billion in 2025 and estimated to grow from USD 73.05 billion in 2026 to reach USD 99.07 billion by 2031, at a CAGR of 6.28% during the forecast period (2026-2031).
This report is Segmented by Product Type (Cell and Tissue Culture Reagents, Chromatography Reagents, and More), End User (Hospitals and Diagnostic Laboratories, and More), Application (Clinical Diagnostics, Drug Discovery and Development, and More), Form (Liquid Reagents, Lyophilized Reagents, Others), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Life Science Reagents Market Trends and Insights
High Burden of Infectious Diseases
Global outbreaks keep molecular and immunoassay reagent volumes elevated. The FDA's flexible emergency-use guidance accelerates market entry for validated rapid-response kits, giving an edge to suppliers with ready-to-scale production platforms . Uptake of point-of-care systems in resource-limited regions is widening access, yet logistics and pricing hurdles persist. Manufacturers able to bundle reagents with compact detection devices gain share by simplifying field deployment. Continuing antimicrobial-resistance surveillance furthers demand for high-throughput PCR mastermixes and selective culture media suited to novel pathogen detection.
Technological Advancements in Genomics & Proteomics
Single-cell sequencing and spatial proteomics are setting new reagent performance benchmarks. Illumina's acquisition of Fluent BioSciences underscores strategic bets on scalable multiomics workflows, pushing suppliers to deliver ultra-low-input enzymes with consistent lot-to-lot kinetics . Automation-ready buffer systems that integrate with self-driving labs have shortened R&D cycles by more than 500 days, cutting reagent wastage and elevating premium SKUs. Vendors able to co-develop kits with instrument makers enjoy preferred-supplier status in expanding install bases.
High Cost & Pricing Pressure of Specialty Reagents
GMP-grade CRISPR components can cost 5-10 times their research-use equivalents, constraining adoption in budget-limited biotechs. Casgevy therapy's USD 2.2 million price tag demonstrates how reagent expenses cascade into final treatment costs. Lotus-to-plateau pricing dynamics encourage bulk purchasing, but consolidation among enzyme and antibody vendors narrows bargaining power for smaller buyers. Emerging plant-based cell-culture supplements that replace 90% of human platelet lysate hint at cost-relief pathways yet need broader validation.
Other drivers and restraints analyzed in the detailed report include:
- Rising R&D Funding & Public-Private Partnerships
- Growing Demand for Precision Diagnostics & Personalised Medicine
- Stringent Multi-Regional Regulatory Compliance
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cell and tissue culture reagents retained 29.68% of the life science reagents market share in 2025, a lead anchored in their indispensability to biomanufacturing workflows. The segment benefits from continuous upgrades toward chemically defined, xeno-free media that curb variability and immunogenicity. Companies such as Rohto Pharmaceutical are advancing serum-free stem-cell media that minimise product-to-product drift, commanding premium list prices in regenerative-medicine pipelines. Chromatography reagents post steady revenue underpinned by antibody purification demand, while clinical chemistry panels gain volume through laboratory automation. Molecular diagnostic reagents, projecting a 7.05% CAGR, outpace peers as liquid biopsy, NGS library prep, and microRNA detection protocols scale.
The molecular diagnostics surge illustrates how precision oncology elevates reagent complexity. Declining sequencing costs unlock smaller hospitals and reference labs as new customers. Coupled enzyme mixes for single-tube library construction slash hands-on time and shrink error rates, amplifying brand differentiation. Emerging CRISPR, microbiome and spatial biology kits populate the "other product types" bracket, showcasing how rapid R&D outpaces traditional catalog structures in the life science reagents industry.
While hospitals and diagnostic laboratories consumed 54.05% of the life science reagents market size in 2025, pharmaceutical and biotechnology companies will register the fastest 7.12% CAGR over 2026-2031. Intensifying biologics pipelines spur firms to internalise previously outsourced analytics, driving purchases of high-purity growth factors, resin sets and companion-diagnostic kits. AbbVie's USD 217.74 billion R&D allocation underscores how upstream reagent commitments parallel therapeutic ambitions. Automation-heavy hospital labs favour integrated reagent-instrument bundles that consolidate procurement and quality monitoring.
Academic institutes remain reliable customers backed by national grants. NIH's yearly USD 41 billion spend maintains baseline demand for discovery-grade primers, antibodies and reporter dyes, ensuring catalogue breadth retention. Contract research organisations within the "others" cohort widen addressable volumes by requesting flexible lot sizes and fast lead times, rewarding distributors with agile stocking algorithms.
Complete Report Scope:
- By Product Type
- Cell and Tissue Culture Reagents
- Chromatography Reagents
- Clinical Chemistry Reagents
- Immunoassay Reagents
- Molecular Diagnostic Reagents
- Microbiology Reagents
- Proteomics and Protein Analysis Reagents
- Next-Generation Sequencing (NGS) Reagents
- Other Product Types
- By End User
- Hospitals and Diagnostic Laboratories
- Academic and Research Institutes
- Pharmaceutical and Biotechnology Companies
- Others
- By Application
- Clinical Diagnostics
- Drug Discovery and Development
- Precision and Personalized Medicine
- Forensic and Security Testing
- Others
- By Form
- Liquid Reagents
- Lyophilized Reagents
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led the life science reagents market size with a 38.74% share in 2025, fuelled by a dense cluster of pharma majors, top-tier research universities and venture-backed start-ups. Substantial Series C rounds, exemplified by ElevateBio's USD 1.3 billion raise, maintain reagent throughput in cell-therapy suites even amid macroeconomic fluctuations. Regulatory predictability under the FDA and strong IP enforcement keep multinational suppliers anchoring bulk production here.
Asia-Pacific is the fastest mover, expanding at a 7.29% CAGR on the back of national biotech blueprints in China, Japan and South Korea. Generous tax credits and park-level infrastructure attract contract development-and-manufacturing organisations that source large-volume media and purification resins locally. Harmonisation with ICH guidelines eases export of region-made reagents to Western clients, closing historical quality-perception gaps.
Europe sustains mid-single-digit growth as Horizon Europe grants channel funds into advanced omics and green-chemistry reagent research. However, incremental compliance layers under the In Vitro Diagnostic Regulation stretch smaller laboratory budgets, nudging purchasing decisions toward dual-certified products that satisfy CE and FDA expectations simultaneously.
Middle East & Africa register rising orders as governments equip new clinical genomics centres, while Latin America benefits from Brazil's biosimilar expansion that raises demand for GMP-grade media and chromatography solutions. Across emerging regions, lyophilised kits capable of withstanding temperature excursions gain traction, underlining format diversification trends in the life science reagents market.
- Roche
- Thermo Fisher Scientific
- Beckton Dickinson
- Abbott Laboratories
- bioMerieux
- Merck
- Danaher
- Siemens Healthineers
- DiaSorin
- Sysmex
- Bio-Rad Laboratories
- Promega
- Agilent Technologies
- QIAGEN
- Illumina
- New England Biolabs
- PerkinElmer
- Lonza Group
- Genscript
- Takara Bio
- Waters Corporation
- Bruker
- Corning
- Charles River
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 High burden of infectious diseases
- 4.2.2 Technological advancements in genomics & proteomics
- 4.2.3 Rising R&D funding & public-private partnerships
- 4.2.4 Growing demand for precision diagnostics & personalized medicine
- 4.2.5 AI-enabled reagent e-commerce & on-demand synthesis
- 4.2.6 Microfluidic cartridge-based decentralized reagent manufacturing
- 4.3 Market Restraints
- 4.3.1 High cost & pricing pressure of specialty reagents
- 4.3.2 Stringent multi-regional regulatory compliance
- 4.3.3 Upstream supply-chain volatility for critical enzymes & buffers
- 4.3.4 Sustainability push toward PFAS-free formulations increases cost & complexity
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Cell and Tissue Culture Reagents
- 5.1.2 Chromatography Reagents
- 5.1.3 Clinical Chemistry Reagents
- 5.1.4 Immunoassay Reagents
- 5.1.5 Molecular Diagnostic Reagents
- 5.1.6 Microbiology Reagents
- 5.1.7 Proteomics and Protein Analysis Reagents
- 5.1.8 Next-Generation Sequencing (NGS) Reagents
- 5.1.9 Other Product Types
- 5.2 By End User
- 5.2.1 Hospitals and Diagnostic Laboratories
- 5.2.2 Academic and Research Institutes
- 5.2.3 Pharmaceutical and Biotechnology Companies
- 5.2.4 Others
- 5.3 By Application
- 5.3.1 Clinical Diagnostics
- 5.3.2 Drug Discovery and Development
- 5.3.3 Precision and Personalized Medicine
- 5.3.4 Forensic and Security Testing
- 5.3.5 Others
- 5.4 By Form
- 5.4.1 Liquid Reagents
- 5.4.2 Lyophilized Reagents
- 5.4.3 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 F. Hoffmann-La Roche Ltd
- 6.3.2 Thermo Fisher Scientific Inc.
- 6.3.3 Becton, Dickinson and Company
- 6.3.4 Abbott Laboratories
- 6.3.5 bioMerieux SA
- 6.3.6 Merck KGaA
- 6.3.7 Danaher Corporation
- 6.3.8 Siemens Healthineers
- 6.3.9 DiaSorin SpA
- 6.3.10 Sysmex Corporation
- 6.3.11 Bio-Rad Laboratories
- 6.3.12 Promega Corporation
- 6.3.13 Agilent Technologies Inc.
- 6.3.14 QIAGEN N.V.
- 6.3.15 Illumina Inc.
- 6.3.16 New England Biolabs
- 6.3.17 PerkinElmer Inc.
- 6.3.18 Lonza Group AG
- 6.3.19 GenScript Biotech Corporation
- 6.3.20 Takara Bio Inc.
- 6.3.21 Waters Corporation
- 6.3.22 Bruker Corporation
- 6.3.23 Corning Incorporated
- 6.3.24 Charles River Laboratories
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment