|
시장보고서
상품코드
2123614
종이 염료 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Paper Dyes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
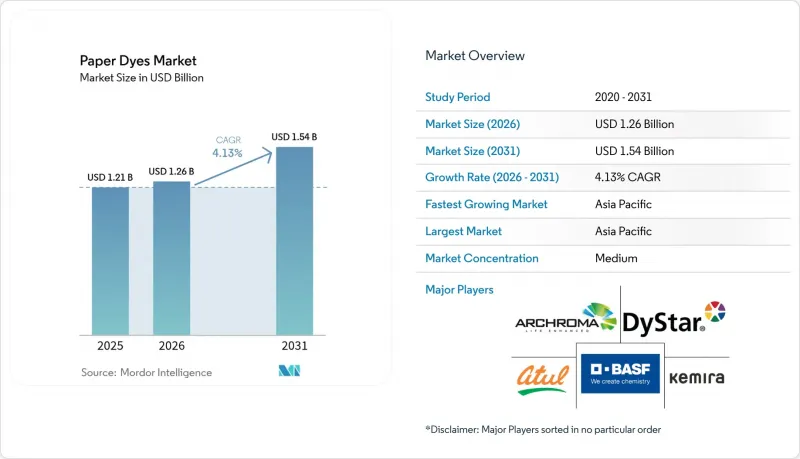
에 의하면, 종이 염료 시장 규모는 2025년에 12억 1,000만 달러로 평가되었고, 2026년 12억 6,000만 달러에서 2031년까지 15억 4,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.13%를 나타낼 전망입니다.
본 보고서에서는 산업을 형태별(분말 및 액체), 유형별(산성, 염기성, 기타), 원료별(유기 및 합성), 용도별(인쇄·필기, 포장, 특수 용도, 기타), 지역별(아시아태평양, 북미, 기타)로 분류하고 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 종이 염료 시장 동향 및 인사이트
플라스틱에서 종이 기반 포장으로의 전환
각 소매 브랜드 기업들은 일회용 플라스틱 금지 조치에 부응하고, 종이를 선호하는 소비자의 기호에 부응하기 위해 석유 유래 기판에서 재활용 가능한 섬유 기반 소재로의 전환을 추진하고 있습니다. 네슬레, 유니레버를 비롯한 다국적 기업들은 현재 특정 SKU에서 플라스틱 사용량을 최대 97%까지 줄이고 있으며, 이에 따라 여러 차례의 재활용 과정을 거치더라도 색조가 안정적인 고성능 염료에 대한 주문이 가속화되고 있습니다. 유럽연합(EU)의 ‘일회용 플라스틱 지침’으로 인해 규제의 확실성이 생기면서, 식품 접촉 적합성이 보장되고 이온 이동 위험이 없는 착색제가 필요한 가공업체들의 설비 투자가 촉진되고 있습니다. 지속 가능한 포장에 대해 소비자들이 다소 높은 가격을 지불하려는 의향이 꾸준히 유지되고 있어, 이에 따라 염료 제조업체들은 재생 섬유 시스템에서 알칼리성 탈잉크 처리 및 산화 표백을 견디는 내광성이 뛰어난 신규 배합 제품의 가격을 유지할 수 있게 되었습니다.
이커머스에 힘입은 골판지 및 우편용 포장 수요 급증
온라인 주문의 80% 이상이 골판지 포장으로 출하되고 있으며, 소포 처리량은 특히 아시아태평양 및 북미에서 지속적으로 증가하고 있습니다. 이에 따라 개봉 시 경험을 향상시키는 선명한 그래픽에 대한 수요가 집중되고 있습니다. 풀필먼트 센터에서는 유지보수 부담이 적은 프린트 헤드를 위해 설계된 액체 염료를 사용하는 단기 납기 잉크젯 라인이 필요하며, 이를 통해 대규모 당일 맞춤화가 가능해집니다. 2024년 포장 공장용 건물 임대 계약은 지난 20년 평균보다 45% 증가했습니다. 이는 예측 기간 동안 종이용 염료 시장을 뒷받침할 구조적인 생산 능력 확대의 분명한 신호입니다.
종이 없는 사무실과 디지털 문서의 보급
기업 및 교육 기관 사용자들이 디지털 워크플로우를 가속화한 결과, 그래픽 용지 수요는 급격히 감소했습니다. 유럽 제지 산업 연맹(CEPI)의 기록에 따르면, 2023년 종이 및 판지 생산량은 13% 감소했으며, 그래픽 용지만으로도 28% 감소했습니다. 인쇄량을 50-70% 줄이도록 하는 재택근무 지침이 여전히 시행되고 있으며, 전자 서명 플랫폼의 보급으로 인해 종이 매체의 필요성도 감소하고 있습니다. 포장용 염료가 일부 손실을 상쇄하고 있지만, 그래픽 용지 수요의 축소가 특히 성숙한 지역에서 전체 생산량 증가를 억제하고 있습니다.
부문별 분석
액체 제품은 2025년 매출의 51.38%를 차지한 것으로 평가되었으며, 연평균 성장률(CAGR) 6.31%로 확대될 것으로 전망되어, 버전 관리가 되는 전자상거래용 포장을 뒷받침하는 고속 잉크젯 라인에서 그 매우 중요한 역할을 더욱 강화하고 있습니다. 분말 등급은 대량 운송이 용이하지만, 분진 노출에 관한 규제나 분산 시간이 길다는 등의 과제를 해결해야 합니다. 나노캡슐화된 액체 시스템을 통해 프린트 헤드의 가동 주기가 1,000시간을 초과할 수 있게 되어, 유지보수로 인한 가동 중단을 최소화하고 컨버터의 OEE(종합 설비 가동률)를 향상시키고 있습니다. 온도 변동에 영향을 받지 않는 안정적인 점도는 자동 급액을 지원하며, 적시 생산(JIT) 목표에 부합합니다.
미니 에멀젼 및 미세 유체 캡슐화 기술의 지속적인 발전으로 인해 보존 기간이 연장되어, 25°C에서 보관할 경우 표준 배합의 경우 6개월인 데 비해 12개월 이상 색상의 선명도를 유지할 수 있습니다. 그 결과, 컨버터는 유통기한이 지난 재고로 인한 손실을 줄일 수 있습니다. 분말 공급업체들은 압축 기술과 분진 억제 기술로 대응하고 있지만, 디지털화된 공장에서는 여전히 액상계 경쟁 제품에 뒤처져 있습니다.
비용 효율이 뛰어난 배액 공정을 통해 선호되는 직접 염료는 2025년 매출의 28.02%를 차지했으며, 대량 생산을 하는 라이너보드 공장에서 우위를 유지하고 있습니다. 그러나 반응성 염료 부문은 뛰어난 내세탁성이라는 강점을 바탕으로 연평균 성장률(CAGR) 5.78%로 성장하고 있습니다. 이 특성은 재활용 후에도 그래픽이 유지되기를 요구하는 고급 접이식 골판지 사용자들로부터 높은 평가를 받고 있습니다. 섬유에 대한 검사 결과, 면 섬유가 풍부한 특수 등급의 경우 반응성 염료를 사용했을 때의 염료 흡수율이 41.45%인 반면, 다른 화학계 염료의 경우 35.68%에 그치는 것으로 나타났습니다.
각 공급업체는 고정성을 저해하지 않으면서 반응욕의 표준 온도를 90°C에서 60°C로 낮추고 있으며, 이를 통해 에너지 부하를 줄이는 동시에 탈탄소화 목표의 제약을 받는 제지 공장에서의 채택을 확대되고 있습니다. 직접 염료는 중성 pH 조건에서 쉽게 부착되기 때문에 여전히 주력 제품이지만, 그 시장 점유율은 순환형 경제의 요건에 부합하는 고부가가치 화학제품에 서서히 잠식당하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 44.25%를 차지했으며, 계속해서 주도적인 위치를 유지하고 있고, 2031년까지 연평균 성장률(CAGR) 5.56%로 확대될 것으로 예측됩니다. 이는 해당 지역이 세계의 제조 거점이며, 급속히 확대되는 소비 시장임을 반영합니다. 중국 화학 산업을 주도하는 헨리, 완파 등 대기업들은 정부의 지원책을 활용하여 정밀 화학 프로젝트에 투자함으로써 지역의 자급률 향상에 기여하고 있습니다. 또한, 7,500개의 섬유 기업이 있으며 430만 명의 근로자를 고용하고 있는 베트남에서는 골판지 및 특수 용지의 지역 소비가 확대되고 있으며, 이는 현지 염료 사용량 증가로 이어지고 있습니다.
북미는 전자상거래 주문 처리 수요의 확대와 식음료 다국적 기업들의 적극적인 플라스틱 감축 공약에 힘입어 금액 기준 2위를 차지하고 있습니다. 알크로마의 사우스캐롤라이나 주 거점과 솔레니스의 버지니아 주 복합 시설이 현지 공급을 담당하는 한편, PFAS에 관한 규제가 명확해짐에 따라 가공업체들은 규정을 준수하는 수성 시스템의 도입을 강요받고 있습니다. 그래픽 용지 시장의 축소가 총 취급량을 억제하고 있지만, 친환경 염료를 우선시하는 고급 등급의 수주가 인플레이션율을 상회하는 가격 실현을 뒷받침하고 있습니다.
유럽에서는 엄격한 REACH 개정과 펄프 가격 변동(2024년 4월 북부 표백 침엽수 크라프트 펄프(NBSK)가 1,380유로/톤에 도달했습니다)에 직면하여 영업이익률에 압박이 가해지고 있습니다. 그러나 순환형 경제 규제에 있어 이 지역의 리더십과 리그닌 유래 착색제에 대한 연구 개발 자금 투입 덕분에 현지 공급업체들은 고부가가치 친환경 제품의 최전선에 서 있습니다. 가공업체들은 폐수 배출 허가 기준을 충족하기 위해 폐쇄형 수처리 시스템에 투자하고 있으며, 이로 인해 폐수 무방류 목표에 부합하는 저염도·고회수율 염료에 대한 수요가 증가하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the paper dyes market size was valued at USD 1.21 billion in 2025 and estimated to grow from USD 1.26 billion in 2026 to reach USD 1.54 billion by 2031, at a CAGR of 4.13% during the forecast period (2026-2031).
This report Segments the Industry by Form (Powder and Liquid), Type (Acidic, Basic, and More), Origin (Organic and Synthetic), Application (Printing and Writing, Packaging, Specialty, and More), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Paper Dyes Market Trends and Insights
Shift from Plastic to Paper-Based Packaging
Retail brands continue to replace petroleum-based substrates with recyclable, fiber-based formats to comply with single-use plastic bans and to meet consumer preference for paper. Nestle, Unilever, and other multinationals now eliminate up to 97% of plastic from certain SKUs, accelerating orders for high-performance dyes that remain stable through multiple recycling loops. Regulatory certainty created by the European Union's Single-Use Plastics Directive supports capital investment in converters that require food-contact-compliant, migration-safe colorants. Consumer willingness to pay premiums for sustainable packaging has held steady, allowing dye producers to defend pricing for novel, colorfast formulations that tolerate alkaline de-inking and oxidative bleaching in recovered-fiber systems.
E-commerce-Fueled Boom in Corrugated & Mailer Demand
Over 80% of online orders ship in corrugated formats, and parcel volumes continue to rise-particularly in Asia-Pacific and North America-creating concentrated demand for vivid graphics that elevate the unboxing experience. Fulfillment centers require rapid-turn inkjet lines that run on liquid dyes engineered for low-maintenance printheads, enabling same-day personalization at scale. Building leases for packaging plants rose 45% above the 20-year average in 2024, a clear signal of structural capacity expansion that will sustain the paper dyes market over the forecast horizon.
Paperless Office & Digital Documents Adoption
Graphic-paper demand contracted sharply after corporate and educational users accelerated digital workflows. The Confederation of European Paper Industries recorded a 13% fall in paper and board production in 2023, with graphic grades alone down 28%. Remote-work protocols that cut printing volumes by 50-70% remain in force, while e-signature platforms reduce the need for hard copies. Although packaging dyes offset some losses, graphic-paper contraction limits overall tonnage growth, particularly in mature regions.
Other drivers and restraints analyzed in the detailed report include:
- Capacity Expansions by Major Dye Manufacturers
- Breakthroughs in Bio-Based Lignin-Compatible Dyes
- Toxic Amines & Rising REACH Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Liquid offerings held 51.38% of 2025 revenue and are projected to expand at a 6.31% CAGR, reinforcing their pivotal role in high-speed inkjet lines that power versioned e-commerce packaging. Powder grades, although easier to transport in bulk, must contend with dust-exposure rules and slower dispersion times. Nano-encapsulated liquid systems now enable print-head duty cycles exceeding 1,000 hours, minimizing maintenance shutdowns and improving OEE for converters. Stable viscosity across temperature swings supports automated dosing, aligning with just-in-time production targets.
Ongoing advances in mini-emulsion and microfluidic encapsulation increase shelf life, preserving hue intensity for over 12 months when stored at 25 °C, compared with six months for standard formulations. As a result, converters see reduced write-offs from expired stocks. Powder suppliers respond with compaction and dust-suppressant technologies but still trail liquid rivals in digitally enabled plants.
Direct dyes, favored for cost-efficient exhaust processes, commanded 28.02% of 2025 sales, maintaining dominance in high-volume linerboard mills. Yet the reactive segment is advancing at a 5.78% CAGR on the strength of superior wash-fastness, an attribute prized by premium folding-carton users who require graphics to survive recycling. According to fiber-specific trials, cotton-fiber-rich specialty grades register dye uptake of 41.45% with reactivatives versus 35.68% for other chemistries.
Suppliers reduce typical reactive-bath temperatures from 90 °C to 60 °C without sacrificing fixation, lowering energy loads, and broadening adoption in mills constrained by decarbonization targets. Direct dyes remain a staple because they attach readily under neutral pH, but their market share is gradually ceded to higher-value chemistries that align with circular-economy mandates.
Complete Report Scope:
- By Form
- Powder
- Liquid
- By Type
- Acidic
- Basic
- Direct
- By Origin
- Organic
- Synthetic
- By Application
- Printing and Writing
- Packaging
- Specialty
- Others (Tissue and Hygiene)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific retained leadership with 44.25% of 2025 revenue and is forecast to rise at a 5.56% CAGR to 2031, reflecting its status as a global manufacturing nucleus and fast-expanding consumer market. China's chemical champions-Hengli, Wanhua, and peers-channel government incentives into fine-chemical projects that lift regional self-sufficiency. Vietnam, hosting 7,500 textile enterprises employing 4.3 million workers, boosts regional consumption of corrugated and specialty papers, translating into higher local dye usage.
North America ranks second by value, propelled by e-commerce fulfillment growth and aggressive plastic-reduction pledges from food and beverage multinationals. Archroma's South Carolina site and Solenis's Virginia complex provide localized supply, while regulatory clarity on PFAS pushes converters to adopt compliant, water-based systems. Although graphic-paper contraction tempers total tonnage, premium-grade orders that favor environmentally optimized dyes support above-inflation price realization.
Europe grapples with stringent REACH amendments and pulp-price volatility-Northern Bleached Softwood Kraft touched EUR 1,380 / t in April 2024-pressuring operating margins. Yet the bloc's leadership in circular-economy regulation and R&D funding for lignin-derived colorants positions local suppliers at the forefront of high-value, eco-optimized offerings. Converters invest in closed-loop water treatment to meet discharge permits, raising demand for low-salt, high-exhaustion dyes that align with zero-liquid-discharge ambitions.
- Archroma
- Ashok Alco-chem
- Atul Ltd.
- BASF
- Celanese Corporation
- ChromaScape
- DyStar Singapore Pte Ltd
- Kemira Oyj
- Kiri Industries Limited
- Lonza
- Merck KGaA
- Milliken
- Nitin Dye Chem Pvt. Ltd
- Setas Kimya
- Standard Colors, Inc.
- Steiner-Axyntis
- Sudarshan Chemical Industries Limited.
- Synthesia, a.s.
- Thermax Limited
- Vipul Organics Ltd.
- Zhejiang Longsheng
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shift from plastic to paper-based packaging
- 4.2.2 E-commerce-fuelled boom in corrugated & mailer demand
- 4.2.3 Capacity expansions by major dye manufacturers
- 4.2.4 Breakthroughs in bio-based lignin-compatible dyes
- 4.2.5 Nano-encapsulated dyes enabling digital inkjet printing on paper
- 4.3 Market Restraints
- 4.3.1 Paperless office & digital documents adoption
- 4.3.2 Toxic amines & rising REACH compliance costs
- 4.3.3 Volatility in wood-pulp availability & pricing
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Form
- 5.1.1 Powder
- 5.1.2 Liquid
- 5.2 By Type
- 5.2.1 Acidic
- 5.2.2 Basic
- 5.2.3 Direct
- 5.3 By Origin
- 5.3.1 Organic
- 5.3.2 Synthetic
- 5.4 By Application
- 5.4.1 Printing and Writing
- 5.4.2 Packaging
- 5.4.3 Specialty
- 5.4.4 Others (Tissue and Hygiene)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Archroma
- 6.4.2 Ashok Alco-chem
- 6.4.3 Atul Ltd.
- 6.4.4 BASF
- 6.4.5 Celanese Corporation
- 6.4.6 ChromaScape
- 6.4.7 DyStar Singapore Pte Ltd
- 6.4.8 Kemira Oyj
- 6.4.9 Kiri Industries Limited
- 6.4.10 Lonza
- 6.4.11 Merck KGaA
- 6.4.12 Milliken
- 6.4.13 Nitin Dye Chem Pvt. Ltd
- 6.4.14 Setas Kimya
- 6.4.15 Standard Colors, Inc.
- 6.4.16 Steiner-Axyntis
- 6.4.17 Sudarshan Chemical Industries Limited.
- 6.4.18 Synthesia, a.s.
- 6.4.19 Thermax Limited
- 6.4.20 Vipul Organics Ltd.
- 6.4.21 Zhejiang Longsheng
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment