

|
시장보고서
상품코드
2123632
만성 골수 백혈병 치료 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Chronic Myelogenous Leukemia Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
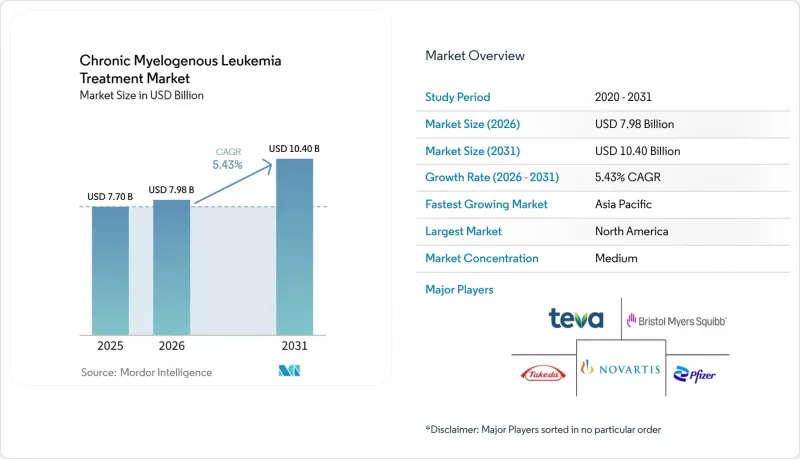
에 의하면, 만성 골수 백혈병 치료 시장 규모는 2025년 77억 달러에서 2026년에는 79억 8,000만 달러로 확대되어 2031년까지 104억 달러에 이를 것으로 예상되고 있어 2026년부터 2031년까지 CAGR 5.43%로 성장할 전망입니다.
본 보고서는 치료 유형(표적 치료, 화학 요법 등), 치료 단계(1차 치료, 2차 치료 등), 투여 경로(경구, 정맥 내 등), 유통 채널(병원 약국, 소매 약국 등), 환자 연령대(소아, 성인 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 만성 골수 백혈병 치료 시장 동향 및 인사이트
CML 발병률 및 유병률 증가
세계 CML 진단 건수는 인구 고령화에 따라 증가하고 있으며, 2024년에는 미국에서 8,930건의 신규 사례가 예상됩니다. 정기적인 혈액 검사를 통한 조기 발견으로 TKI에 양호한 반응을 보이는 만성기 사례가 증가하고 있습니다. 생존율의 향상으로 장기 치료가 필요한 환자층이 확대되고 있는 반면, 저·중소득 국가(LMICs)에서의 진단 누락은 향후 상당한 성장 여지를 남기고 있습니다. 유럽 및 북미의 의료 시스템에서는 이미 분자진단이 표준 치료로 자리 잡고 있으며, 검사 인프라가 정비됨에 따라 아시아태평양에서도 이와 유사한 보급이 진행될 기반이 마련되고 있습니다.
차세대 TKI의 획기적인 진전
FDA가 2024년에 신규 진단 환자를 대상으로 아스키미닙에 부여한 신속 승인은 미리스토일 포켓을 표적으로 하는 새로운 기전을 특징으로 하며, 대조군 TKI의 49%에 비해 68%의 주요 분자 반응률을 달성했습니다. 올베렘바티닙과 같은 돌연변이 특이적 약물은 치료가 어려운 T315I 내성을 해결하며, 중국에서 획기적 치료제로 지정받았는데, 이는 파이프라인이 오프타겟 독성을 줄이는 정밀 표적 치료로 전환되고 있음을 시사합니다.
다중 TKI에 수반되는 오프타겟 독성 및 심혈관 사건
닐로티닙 및 포나티닙은 동맥계 사건과의 관련성이 지적되고 있어, 기준선에서의 심혈관 위험 평가와 빈번한 모니터링이 필요합니다. TKI의 연속 사용은 위험을 증가시키므로, 보다 조기 치료법 변경(TFR)이나 키나아제 억제 프로파일이 더 좁은 돌연변이 특이적 약물에 대한 관심이 높아지고 있습니다.
부문 분석
2025년 만성 골수 백혈병 치료 시장에서 표적 치료는 매출의 91.39%를 차지하며, 화학요법 부문은 2031년까지 연평균 성장률(CAGR) 6.53%로 성장할 것으로 전망됩니다. 의사들 사이에서 높은 인지도, 가이드라인에 대한 폭넓은 채택, 그리고 높은 분자 반응률이 이 부문의 우위를 유지하고 있습니다. 생물학적 요법은 부문 규모는 작지만, 인터페론 기반 병용 요법 및 치료 중단 완화(TFR) 전략에 대한 임상적 관심이 높아짐에 따라 가장 높은 성장률을 나타낼 것으로 예측됩니다. 생물학적 요법을 이용한 만성 골수 백혈병 치료 시장 규모는 분자 반응을 심화하고 지속적인 관해를 뒷받침하는 능력이 연구를 통해 입증됨에 따라 확대될 것으로 예측됩니다. 특히 장기적인 질병 조절이나 잠재적인 TFR을 목표로 하는 환자들 사이에서 TKI와 함께 페그화 인터페론 요법의 채택이 증가하고 있는 것이 예측 기간 동안 해당 부문의 성장을 견인할 것으로 보입니다.
조혈모세포 이식은 만성기 수혜자의 5년 무병 생존율이 80%에 달하고, 완치의 가능성을 유지하고 있지만, TKI에 의해 조기 질병 진행이 억제됨에 따라 그 점유율은 축소되고 있습니다. 이식 후 시클로포스파미드 투여로 인해 기증자 후보의 폭이 넓어져, 특히 유전적 다양성이 높은 집단에 유익하고 있습니다. 화학요법은 여전히 블라스트 위기 단계로 제한되어 있지만, CD20 및 기타 마커를 표적으로 하는 단일클론 항체는 초기 임상시험 단계를 진행 중입니다.
2025년, 1차 치료법은 만성 골수 백혈병 치료 시장 점유율의 53.38%를 차지하며, 이는 이마티닙의 장기적인 사용 실적과 2세대(2G) 대체 약물의 접근성 확대에 힘입은 것입니다. 2차 치료법의 경우, 환자의 생존 기간 연장에 따라 내성 돌연변이가 축적됨에 따라 연평균 성장률(CAGR) 5.72%가 예상됩니다. NCCN 가이드라인에서는 초기 TKI 선택을 소칼(Sokal) 또는 ELTS 위험 점수, 연령, 동반 질환의 부담에 따라 점점 더 개별화하는 경향이 있습니다. 아시미닙이나 올베레바티닙을 이용한 돌연변이 기반 치료 순서 결정에 따라 3차 치료의 채택이 확대될 전망입니다. 임상의들이 병용 요법이나 돌연변이 특이적 치료 요법을 채택함에 따라, 만성 골수 백혈병 치료 시장의 후기 치료 단계 시장 규모는 사상 최고 수준에 도달할 것으로 예측됩니다.
지역별 분석
북미는 FDA의 조기 승인, 종합적인 보험 적용, 그리고 세계에서 가장 밀집된 분자 검사 시설에 힘입어 2025년에는 전 세계 매출의 42.20%를 차지했습니다. 미국의 학술 거점은 전 세계 임상 벤치마크가 되는 TFR 연구 및 병용 요법 임상시험을 주도하고 있습니다. 캐나다의 국민건강보험 제도는 TKI에 대한 접근성을 확대하고 있지만, 주별 처방약 목록 재검토로 인해 신약 도입이 지연될 수 있습니다.
아시아태평양은 연평균 성장률(CAGR) 6.25%로 향후 성장을 주도할 것입니다. 중국은 ‘국가 보험 등재 의약품 목록’을 통해 획기적인 치료법을 신속하게 승인하고 있는 반면, 인도는 민간 보험 보급률 상승을 활용해 TKI 비용을 충당하고 있습니다. 일본의 초고령 사회는 안정적인 수요를 유지하고 있으며, 한국의 정밀의료 이니셔티브는 AI를 활용한 모니터링을 추진하고 있습니다. 지역 간 격차는 여전히 존재하며, 인도와 인도네시아의 농촌 지역에서는 여전히 실시간 PCR 검사 체계가 갖춰지지 않아 최적의 치료 조정이 지연되고 있습니다.
유럽은 성숙한 시장임에도 불구하고 혁신에 우호적인 환경을 조성하고 있습니다. ‘프로젝트 오비스(Project Orbis)’ 협력을 통해 EMA와 FDA의 동시 심사가 가능해지면서 접근성 격차가 줄어들고 있습니다. 독일과 영국은 적응형 임상시험 설계를 주도하고 있지만, 남유럽 국가들에서는 예산 제약으로 인해 고가의 치료법 보급이 지연될 가능성이 있습니다. 중동 및 아프리카는 여전히 신흥 시장이며, 그 확대는 검사 네트워크에 대한 투자와 기부금을 통한 의약품 지원 프로그램에 달려 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the chronic myelogenous leukemia treatment market size is expected to increase from USD 7.70 billion in 2025 to USD 7.98 billion in 2026 and reach USD 10.40 billion by 2031, growing at a CAGR of 5.43% over 2026-2031.
This report is Segmented by Treatment Type (Targeted Therapy, Chemotherapy, and More), Line of Therapy (First-Line, Second-Line and More), Route of Administration (Oral, Intravenous and More), Distribution Channel (Hospital Pharmacies, Retail Pharmacies and More), Patient Age Group (Pediatric, Adults and More) and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Chronic Myelogenous Leukemia Treatment Market Trends and Insights
Rising Incidence & Prevalence of CML
Global CML diagnoses are expanding alongside aging demographics, with 8,930 new U.S. cases anticipated in 2024. Earlier detection through routine blood tests leads to more chronic-phase presentations that respond favorably to TKIs. Improved survival enlarges the prevalent patient pool requiring long-term therapy, while underdiagnosis in low- and middle-income countries (LMICs) leaves room for significant future growth. Healthcare systems in Europe and North America already integrate molecular diagnostics as standard of care, setting the stage for similar penetration in Asia Pacific as laboratory infrastructure matures.
Breakthroughs in Next-Gen TKIs
The FDA's 2024 accelerated approval of asciminib for newly diagnosed patients showcases a novel myristoyl-pocket mechanism that achieved a 68% major molecular response versus 49% with comparator TKIs.Mutation-specific agents like olverembatinib address difficult T315I resistance and received breakthrough status in China, signaling a pipeline pivot toward precision targeting that curtails off-target toxicity.
Off-Target Toxicities & Cardiovascular Events with Multi-TKIs
Nilotinib and ponatinib have been linked to arterial events that necessitate baseline cardiovascular risk assessments and frequent monitoring. Sequential TKI use compounds risk, prompting interest in earlier TFR or alternative mutation-specific drugs that offer narrower kinase inhibition profiles.
Other drivers and restraints analyzed in the detailed report include:
- Escalating R&D Funding & Clinical-Trial Volume
- Shift Toward Treatment-Free Remission (TFR) Protocols
- Stringent Regulatory & Pharmacovigilance Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Targeted therapy secured 91.39% revenue in 2025 in the Chronic Myelogenous Leukemia Treatment market and chemotherapy segment growing at 6.53% CAGR through 2031. Widespread physician familiarity, broad guideline inclusion, and deep molecular response rates maintain its primacy. Biologic therapy, while representing a smaller segment, is projected to register the highest growth rate owing to increasing clinical interest in interferon-based combination regimens and treatment-free remission (TFR) strategies. The Chronic Myelogenous Leukemia Treatment market size for biologic therapies is expected to expand as studies demonstrate their ability to deepen molecular responses and support sustained remission. Growing adoption of pegylated interferon therapies alongside TKIs, particularly in patients pursuing long-term disease control and potential TFR, is expected to drive segment growth over the forecast period.
Stem-cell transplantation retains curative potential with 80% five-year disease-free survival in chronic-phase recipients, yet its share shrinks as TKIs mitigate early progression. Post-transplant cyclophosphamide broadens donor pools, particularly benefitting genetically diverse populations. Chemotherapy remains limited to blast-phase crises, while monoclonal antibodies aimed at CD20 and other markers advance through early trials.
First-line regimens held 53.38% of the Chronic Myelogenous Leukemia Treatment market share in 2025, anchored by imatinib's longevity and wider availability of 2G alternatives. Second-line therapies are forecast for 5.72% CAGR as resistance mutations accumulate over extended patient lifespans. NCCN guidelines increasingly tailor initial TKI choice to Sokal or ELTS risk scores, age, and comorbidity burden. Mutation-guided sequencing with asciminib and olverembatinib is set to lift third-line uptake. The Chronic Myelogenous Leukemia Treatment market size for later-line settings is projected to reach new highs as clinicians adopt combination and mutation-specific regimens.
Complete Report Scope:
- By Treatment Type
- Targeted Therapy
- Chemotherapy
- Biologic Therapy
- Stem Cell Transplantation
- Other Treatment Types
- By Line of Therapy
- First-line
- Second-line
- Third-line & Beyond
- By Route of Administration
- Oral
- Intravenous
- Subcutaneous
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Specialty Clinics
- By Patient Age Group
- Pediatric
- Adults
- Geriatric
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 42.20% of global revenue in 2025, supported by early FDA approvals, comprehensive insurance coverage, and the world's highest density of molecular labs. U.S. academic hubs pioneer TFR studies and combination trials that set clinical benchmarks worldwide. Canadian universal coverage widens TKI access, though adoption of brand-new agents can lag due to provincial formulary reviews.
Asia Pacific leads future growth at an 6.25% CAGR. China fast-tracks breakthrough therapies through the National Reimbursement Drug List, while India leverages rising private insurance penetration to pay for TKIs. Japan's super-aged society sustains steady demand, and South Korea's precision-medicine initiatives promote AI-based monitoring. Regional disparities persist: rural areas in India and Indonesia still lack real-time PCR capacity, delaying optimal therapy adjustments.
Europe constitutes a mature but innovation-friendly arena. Project Orbis collaboration allows simultaneous EMA-FDA reviews, shrinking access gaps. Germany and the United Kingdom spearhead adaptive trial designs, whereas budget constraints in Southern Europe can slow uptake of premium therapies. The Middle East and Africa remain nascent markets whose expansion hinges on lab-network investments and donor-funded medication programs.
- Novartis
- Bristol-Myers Squibb
- Pfizer
- Takeda Pharmaceuticals
- Incyte Corp.
- Merck
- Roche
- Sanofi
- Boehringer Ingelheim
- Teva Pharmaceutical Industries
- Viatris
- Cipla
- Amneal Pharmaceuticals
- Accord Healthcare
- Fresenius
- Ascentage Pharma Group Corp.
- Hansoh Pharmaceutical Group Co. Ltd.
- Sun Pharma Industries Ltd.
- Dr. Reddy's Laboratories Ltd.
- Hikma Pharmaceuticals
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Incidence & Prevalence Of CML
- 4.2.2 Breakthroughs In Next-Gen TKIs
- 4.2.3 Escalating R&D Funding & Clinical-Trial Volume
- 4.2.4 Shift Toward Treatment-Free Remission (TFR) Protocols
- 4.2.5 Imminent Wave Of Generic 2G TKIs Reducing Therapy Cost
- 4.2.6 AI-Enabled Molecular Monitoring For Dose Optimisation
- 4.3 Market Restraints
- 4.3.1 Off-Target Toxicities & Cardiovascular Events With Multi-Tkis
- 4.3.2 Stringent Regulatory & Pharmacovigilance Requirements
- 4.3.3 Rising Real-World TKI Resistance From Poor Adherence
- 4.3.4 Inadequate Molecular-Monitoring Access In LMICs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Treatment Type
- 5.1.1 Targeted Therapy
- 5.1.2 Chemotherapy
- 5.1.3 Biologic Therapy
- 5.1.4 Stem Cell Transplantation
- 5.1.5 Other Treatment Types
- 5.2 By Line of Therapy
- 5.2.1 First-line
- 5.2.2 Second-line
- 5.2.3 Third-line & Beyond
- 5.3 By Route of Administration
- 5.3.1 Oral
- 5.3.2 Intravenous
- 5.3.3 Subcutaneous
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail Pharmacies
- 5.4.3 Online Pharmacies
- 5.4.4 Specialty Clinics
- 5.5 By Patient Age Group
- 5.5.1 Pediatric
- 5.5.2 Adults
- 5.5.3 Geriatric
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Novartis AG
- 6.3.2 Bristol Myers Squibb Co.
- 6.3.3 Pfizer Inc.
- 6.3.4 Takeda Pharmaceutical Co. Ltd.
- 6.3.5 Incyte Corp.
- 6.3.6 Merck & Co., Inc.
- 6.3.7 F. Hoffmann-La Roche Ltd.
- 6.3.8 Sanofi SA
- 6.3.9 Boehringer Ingelheim GmbH
- 6.3.10 Teva Pharmaceutical Industries Ltd.
- 6.3.11 Viatris Inc.
- 6.3.12 Cipla Ltd.
- 6.3.13 Amneal Pharmaceuticals LLC
- 6.3.14 Accord Healthcare Inc.
- 6.3.15 Fresenius Kabi AG
- 6.3.16 Ascentage Pharma Group Corp.
- 6.3.17 Hansoh Pharmaceutical Group Co. Ltd.
- 6.3.18 Sun Pharma Industries Ltd.
- 6.3.19 Dr. Reddy's Laboratories Ltd.
- 6.3.20 Hikma Pharmaceuticals plc
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


