|
시장보고서
상품코드
2123669
생체인식 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Biometrics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 생체인식 시장 규모는 2025년 589억 8,000만 달러로 평가되었고, 2026년에는 678억 6,000만 달러로 추정되고, 2026-2031년 CAGR 15.07%로 성장을 지속할 전망이며, 2031년에는 1,368억 6,000만 달러에 이를 것으로 예측됩니다.
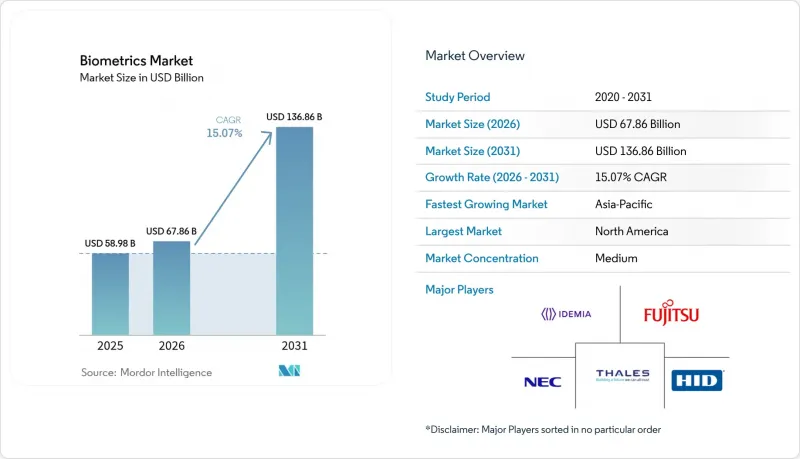
본 보고서는 구성 요소별(하드웨어, 소프트웨어, 서비스), 생체인식 방식별(생리적, 행동적), 접촉 유형별(접촉형, 비접촉형, 하이브리드형), 인증 유형별(단일 요소, 다중 요소), 용도별(접근 제어, 결제 인증, 기타), 최종 이용 산업별(정부, 은행, 금융서비스 및 보험(BFSI), 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 생체인식 시장 동향 및 인사이트
아시아 전역의 정부 주도 국가 전자 신분증 프로그램
아시아 각국의 당국은 대규모 디지털 ID 혁신을 추진하고 있습니다. 한국의 스마트폰 기반 주민등록카드와 2025년 7월까지 외국인에게도 생체인식 ID를 확대하겠다는 베트남의 결정은 종합적인 생태계의 벤치마크가 되고 있습니다. 인도네시아의 2억 달러 규모 ‘INA Digital’ 플랫폼과 필리핀의 8,950만 명 시민 등록은 그동안 은행 계좌를 가질 수 없었던 성인층이 금융 서비스를 이용할 수 있게 해주고 있습니다. 지문, 얼굴, 망막 스캔을 결합한 스리랑카의 멀티모달 프로그램은 2026년 완료를 목표로 하고 있으며, 신흥 경제국들이 어떻게 기존 인프라를 뛰어넘어 발전하고 있는지를 보여주고 있습니다.
지문 결제 카드를 추진하는 EMVCo와 ISO 표준
EMVCo와 ISO 규정이 조화를 이루면서 생체인식 카드는 시범 단계에서 상용 발행 단계로 전환되었습니다. Infineon의 ‘SECORA Pay Bio’ 칩과 Thales의 세계 검사 운영을 통해 오승인율이 감소하고 거래 한도 상향이 가능해졌습니다. 마스터카드(Mastercard)의 ‘Identity Check’와 패스키(Passkey) 지원은 원활한 인증을 보장하며, 발행 기관이 부정 사용 및 차지백을 줄이는 데 도움이 됩니다. 은행들이 PIN이 필요 없는 비접촉식 경험을 우선시함에 따라, 각 벤더들은 2028년까지 1억 1,330만 장의 생체인식 카드가 출하될 것으로 예측했습니다.
GDPR(EU 개인정보보호규정) 및 BIPA에 따른 소송 위험이 시장 확장을 억제
2024년부터 2025년에 걸쳐 Clearview AI에 대한 5,175만 달러의 합의금을 포함해 BIPA 관련 합의금이 2억 달러 이상에 달한 것은 명시적인 동의 없이 얼굴 인식을 도입하는 기업에 막대한 배상 책임이 발생할 수 있음을 시사합니다. GDPR(EU 개인정보보호규정)의 엄격한 데이터 최소화 및 현지 처리 규정에 따라, 유럽에서 1건당 도입 시 5만-20만 유로(5만 6,500-22만 6,000달러)의 규정 준수 비용이 발생하여 소규모 프로젝트의 적용 범위가 축소되고 있습니다. FTC가 Rite Aid에 부과한 시정 조치는 알고리즘 편향성에 대한 감사와 관련하여 미국의 선례가 되었으며, 공급업체들에게 ‘프라이버시 바이 디자인(Privacy by Design)’을 실현하기 위한 아키텍처 재설계를 요구하고 있습니다.
부문 분석
소프트웨어 엔진은 하드웨어가 매출 점유율 41.92%를 유지하는 가운데, 보조적인 역할에서 연평균 성장률(CAGR) 16.35%라는 최고 성장률을 자랑하는 구성 요소로 성장했습니다. 조직들은 클라우드 오케스트레이션, AI 기반 생체 인식, 끊임없이 진화하는 사기 행위에 지속적으로 적응하는 분산형 ID 지갑을 중시하고 있습니다. 엔트러스트(Entrust)의 온피드(OnFido) 인수는 이러한 추세를 반영한 것으로, 딥페이크 방지 기능이 추가됨에 따라 위조 ID 방지 효과가 5배 향상되었습니다.
하드웨어 부문은 전용 센서가 암호화 템플릿을 보안 요소로 전송하는 상황에서 여전히 필수적인 존재입니다. 인피니언(Infineon)의 자동차용 인증 지문 IC는 양산 등급의 구성 요소가 생체인식 시장을 모빌리티 및 접근 제어 부문으로 확대하고 있는 좋은 예입니다. 서비스 부문은 규모는 가장 작지만, 통합 업체들이 규제 산업용으로 다중 모드 도입을 맞춤화하고 있어 꾸준한 수요 증가가 나타나고 있습니다.
홍채 인증은 부품 원가를 절감하고 폼 팩터를 소형화하는 액체 렌즈 광학 기술에 힘입어 연평균 성장률(CAGR) 17.85%로 성장을 지속하고 있습니다. 지문 인증은 스마트폰,결제 카드, 근태 관리 시스템 덕분에 2025년에도 생체인식 시장 점유율의 36.55%를 차지하며 여전히 확고한 입지를 다지고 있습니다. 얼굴 인증은 공항이나 경기장에서 꾸준히 보급되고 있으며, 음성 분석은 콜센터 인증 분야에서 입지를 다져가고 있습니다.
행동 생체인식, 특히 보행 패턴이나 키 입력의 동적 특성은 사용자에게 부담을 주지 않으면서 보안을 강화하는 수동적인 계층을 추가합니다. 성숙한 지문 및 얼굴 인식 솔루션은 멀티모달 키트에서 홍채, 손바닥 정맥 또는 음성 모듈과 결합되는 사례가 증가하고 있으며, 이를 통해 수익원이 다각화되고 단일 모드 사용에 따른 위험이 완화되고 있습니다.
지역별 분석
2025년, 북미는 연방 정부 예산과 민간 부문의 광범위한 도입에 힘입어 전 세계 매출의 30.35%를 차지했습니다. TSA(미국 교통안전청)의 검사 레인 확대 가속화와 DHS(미국 국토안보부)의 신원 관리에 관한 2억 5,080만 달러 규모의 예산 항목은 공급업체들에게 수년에 걸친 수요를 뒷받침하고 있습니다. 캐나다와 멕시코는 무역 효율화를 도모하기 위해 육상 국경의 전자 게이트를 현대화하고 있으며, 북미 대륙 차원의 확장을 강화하고 있습니다.
아시아태평양은 2031년 연평균 성장률(CAGR)이 18.10%로 예측되어 가장 급격한 성장 궤적을 기록할 전망입니다. 한국의 전국적 모바일 ID 도입 완료, 중국의 얼굴 인식 관련 법규 정비, 인도의 Aadhaar와 연계된 결제 서비스는 단일 국가 프로그램을 뛰어넘는 규모의 통합 생체인식 시장을 조성하고 있습니다. 이 지역의 48억 명에 달하는 디지털 지갑 이용자들이 은행 및 통신 사업자에서 생체인증을 통한 본인 확인(KYC)을 선택 사항에서 필수 사항으로 전환시키고 있습니다.
유럽에서는 엄격한 GDPR(EU 개인정보보호규정)의 감독 하에 꾸준한 성장이 이어지고 있습니다. EU의 입국·출국 관리 시스템(EES)을 통해 쉥겐 협정 가입국 전체에서 국경 생체인식이 도입되는 한편, 영국의 새로운 신뢰 프레임워크는 민간 부문의 인증 기술 혁신을 촉진하고 있습니다. 북유럽 국가들의 실증 실험을 통해 단말기 내 처리가 속도를 희생하지 않으면서도 개인정보 보호 감독 기관의 요건을 충족할 수 있음이 입증되었으며, 이는 유럽 전역의 조달 기준을 형성하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the biometrics market size is expected to grow from USD 58.98 billion in 2025 to USD 67.86 billion in 2026 and is forecast to reach USD 136.86 billion by 2031 at 15.07% CAGR over 2026-2031.
This report is Segmented by Component (Hardware, Software, Services), Biometric Modality (Physiological, Behavioral), Contact Type (Contact-Based, Contactless, Hybrid), Authentication Type (Single-Factor, Multi-Factor), Application (Access Control, Payment Authentication, and More), End-Use Industry (Government, BFSI, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Biometrics Market Trends and Insights
Government-backed National e-ID Programs Across Asia
Asian authorities are orchestrating large-scale digital identity transformations. South Korea's smartphone-based resident registration card and Vietnam's decision to extend biometric IDs to foreign nationals by July 2025 have set benchmarks for inclusive ecosystems. Indonesia's USD 200 million INA Digital platform and the Philippines' registration of 89.5 million citizens unlock financial services for previously unbanked adults. Sri Lanka's multi-modal program combining fingerprints, face, and retina scans targets completion in 2026, illustrating how emerging economies leapfrog legacy infrastructures.
EMVCo and ISO Standards Catalyzing Fingerprint Payment Cards
Harmonized EMVCo and ISO rules have moved biometric cards from pilots to commercial issuance. Infineon's SECORA Pay Bio silicon and Thales' global trials cut false-accept rates and allow higher transaction ceilings . Mastercard's Identity Check and passkey support promise frictionless authentication, helping issuers reduce fraud and chargebacks. Vendors forecast shipments of 113.3 million biometric cards by 2028 as banks prioritize PIN-free contactless experiences.
GDPR and BIPA Litigation Risks Curtailing Roll-outs
More than USD 200 million in BIPA settlements during 2024-2025, including Clearview AI's USD 51.75 million payment, signals material liability for enterprises deploying facial recognition without explicit consent. GDPR's strict data-minimization and local-processing rules add EUR 50,000-200,000 (USD 56,500-226,000) compliance cost per European installation, shrinking the addressable base for small projects. The FTC's enforcement against Rite Aid sets a U.S. precedent for algorithmic-bias audits, compelling vendors to redesign architectures for privacy by design.
Other drivers and restraints analyzed in the detailed report include:
- U.S. TSA Biometrics Road-map Driving Federal Procurement Surge
- China's "Smart Airport 2025" Policy Accelerating Face & Voice Biometrics
- Algorithmic Bias Triggering Procurement Moratoriums
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software engines grew from a supporting role to the highest-growth component at a 16.35% CAGR, even while hardware kept the 41.92 revenue share. Organizations value cloud orchestration, AI-based liveness detection, and decentralized identity wallets that continuously adapt to evolving fraud. Entrust's acquisition of Onfido aligns with this trajectory, adding deep-fake countermeasures that improved forged-ID prevention five-fold.
The hardware segment remains indispensable where specialized sensors deliver cryptographic templates to secure elements. Infineon's automotive-qualified fingerprint ICs illustrate how production-grade components expand the biometrics market into mobility and access domains. Services, while smallest, record consistent uptake as integrators customize multi-modal deployments for regulated industries.
Iris recognition posts an 17.85% CAGR, supported by liquid-lens optics that lower bill-of-material cost and shrink form factors. Fingerprint remains entrenched with 36.55% of biometrics market share in 2025, thanks to smartphones, payment cards, and time-clock systems. Facial recognition steadily penetrates airports and stadiums, while voice analytics gains footing in call-center authentication.
Behavioral biometrics, particularly gait and keystroke dynamics, add passive layers that elevate security without user friction. Mature fingerprint and facial solutions increasingly pair with iris, palm-vein, or voice modules in multi-modal kits, diversifying revenue and diluting single-modality risk.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Biometric Modality
- Physiological Biometrics
- Fingerprint AFIS
- Fingerprint Non-AFIS (Automated Fingerprint Identification System)
- Facial Recognition
- Iris Recognition
- Others (Palm Vein, Hand Geometry)
- Behavioral Biometrics
- Voice Recognition
- Signature Verification
- Others (Gait Analysis, Keystroke Dynamics)
- Physiological Biometrics
- By Contact Type
- Contact-based
- Contactless
- Hybrid
- By Authentication Type
- Single-factor
- Multi-factor
- By Application
- Physical and Logical Access Control
- Time and Attendance Management
- Payment and Transaction Authentication
- e-Passport and Border Control
- Patient Identification and EHR Security
- Customer On-boarding (eKYC)
- Public Surveillance and Safety
- Automotive and Smart Vehicle Interfaces
- By End-Use Industry
- Government and Law Enforcement
- BFSI
- Healthcare
- Consumer Electronics
- Commercial and Retail
- Travel and Immigration
- Military and Defense
- Automotive
- Education
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Nordics
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- ASEAN
- Australia
- New Zealand
- Rest of Asia Paccific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America produced 30.35% of global revenue in 2025, anchored by federal budgets and widespread private-sector adoption. TSA's accelerating lane expansions and DHS's USD 250.8 million line-item for identity management provide a multi-year demand floor for vendors . Canada and Mexico modernize land-border e-gates to streamline trade, reinforcing continental scale.
Asia Pacific records the steepest trajectory with an 18.10% CAGR forecast to 2031. South Korea's nationwide mobile-ID completion, China's codified face-recognition rules, and India's Aadhaar-linked pay services cultivate a unified biometrics market bigger than any single-country program. The region's 4.8 billion digital-wallet users push biometric KYC from optional to mandatory across banks and telecoms.
Europe's growth remains steady under strict GDPR oversight. The EU Entry/Exit System rolls out border biometrics across Schengen states, while the United Kingdom's new trust framework fosters private-sector credential innovation. Nordic pilots prove that on-device processing can satisfy privacy watchdogs without sacrificing speed, shaping procurement criteria across the continent.
- Thales Group
- NEC Corporation
- IDEMIA France SAS
- Fujitsu Limited
- HID Global Corporation
- Assa Abloy AB
- Aware Inc.
- Suprema Inc.
- Synaptics Incorporated
- Bio-Key International Inc.
- Zwipe AS
- Fingerprint Cards AB
- M2SYS Technology
- Infineon Technologies AG
- Entrust Corporation
- ImageWare Systems Inc.
- Phonexia s.r.o.
- BioID AG
- Crossmatch Technologies Inc.
- Hitachi Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government-backed National e-ID Programs Across Asia
- 4.2.2 EMVCo and ISO Standards Catalyzing Fingerprint Payment Cards in North America and Europe
- 4.2.3 Post-pandemic Demand for Touch-free Physical Access in European Commercial Real-estate
- 4.2.4 U.S. TSA Biometrics Road-map Driving Federal Procurement Surge
- 4.2.5 China's "Smart Airport 2025" Policy Accelerating Face and Voice Biometrics
- 4.2.6 Biometric KYC Mandates by GCC and African Central Banks
- 4.3 Market Restraints
- 4.3.1 GDPR and BIPA Litigation Risks Curtailing Facial-Recognition Roll-outs
- 4.3.2 Algorithmic Bias Against Dark-Skin Demographics Triggering Procurement Moratoriums
- 4.3.3 CMOS Image-Sensor Shortages Constricting Fingerprint Module Supply
- 4.3.4 Integration and ROI Concerns in South-American Retail Chains
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Industry Stakeholder Analysis
- 4.9 Investment and Funding Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Biometric Modality
- 5.2.1 Physiological Biometrics
- 5.2.1.1 Fingerprint AFIS
- 5.2.1.2 Fingerprint Non-AFIS (Automated Fingerprint Identification System)
- 5.2.1.3 Facial Recognition
- 5.2.1.4 Iris Recognition
- 5.2.1.5 Others (Palm Vein, Hand Geometry)
- 5.2.2 Behavioral Biometrics
- 5.2.2.1 Voice Recognition
- 5.2.2.2 Signature Verification
- 5.2.2.3 Others (Gait Analysis, Keystroke Dynamics)
- 5.2.1 Physiological Biometrics
- 5.3 By Contact Type
- 5.3.1 Contact-based
- 5.3.2 Contactless
- 5.3.3 Hybrid
- 5.4 By Authentication Type
- 5.4.1 Single-factor
- 5.4.2 Multi-factor
- 5.5 By Application
- 5.5.1 Physical and Logical Access Control
- 5.5.2 Time and Attendance Management
- 5.5.3 Payment and Transaction Authentication
- 5.5.4 e-Passport and Border Control
- 5.5.5 Patient Identification and EHR Security
- 5.5.6 Customer On-boarding (eKYC)
- 5.5.7 Public Surveillance and Safety
- 5.5.8 Automotive and Smart Vehicle Interfaces
- 5.6 By End-Use Industry
- 5.6.1 Government and Law Enforcement
- 5.6.2 BFSI
- 5.6.3 Healthcare
- 5.6.4 Consumer Electronics
- 5.6.5 Commercial and Retail
- 5.6.6 Travel and Immigration
- 5.6.7 Military and Defense
- 5.6.8 Automotive
- 5.6.9 Education
- 5.6.10 Others
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 United Kingdom
- 5.7.3.2 Germany
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Nordics
- 5.7.3.7 Russia
- 5.7.3.8 Rest of Europe
- 5.7.4 Asia Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 South Korea
- 5.7.4.4 India
- 5.7.4.5 ASEAN
- 5.7.4.6 Australia
- 5.7.4.7 New Zealand
- 5.7.4.8 Rest of Asia Paccific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Middle East
- 5.7.5.1.1 Saudi Arabia
- 5.7.5.1.2 United Arab Emirates
- 5.7.5.1.3 Turkey
- 5.7.5.1.4 Israel
- 5.7.5.1.5 Rest of Middle East
- 5.7.5.2 Africa
- 5.7.5.2.1 South Africa
- 5.7.5.2.2 Nigeria
- 5.7.5.2.3 Kenya
- 5.7.5.2.4 Rest of Africa
- 5.7.5.1 Middle East
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes global overview, market overview, core segments, financials, strategic information, market rank/share, products and services, recent developments)
- 6.4.1 Thales Group
- 6.4.2 NEC Corporation
- 6.4.3 IDEMIA France SAS
- 6.4.4 Fujitsu Limited
- 6.4.5 HID Global Corporation
- 6.4.6 Assa Abloy AB
- 6.4.7 Aware Inc.
- 6.4.8 Suprema Inc.
- 6.4.9 Synaptics Incorporated
- 6.4.10 Bio-Key International Inc.
- 6.4.11 Zwipe AS
- 6.4.12 Fingerprint Cards AB
- 6.4.13 M2SYS Technology
- 6.4.14 Infineon Technologies AG
- 6.4.15 Entrust Corporation
- 6.4.16 ImageWare Systems Inc.
- 6.4.17 Phonexia s.r.o.
- 6.4.18 BioID AG
- 6.4.19 Crossmatch Technologies Inc.
- 6.4.20 Hitachi Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment