

|
시장보고서
상품코드
2123686
약물 용출 스텐트 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Drug Eluting Stent - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
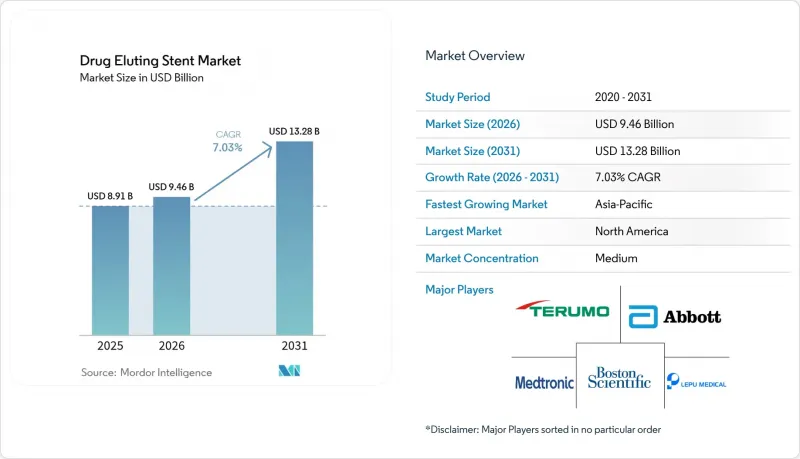
에 의하면, 약물 용출 스텐트 시장 규모는 2025년 89억 1,000만 달러로 평가되었고, 2026년에는 94억 6,000만 달러로 추정되고, 2031년까지 132억 8,000만 달러에 이를 것으로 예상되며, 2026-2031년 CAGR 7.03%로 성장할 전망입니다.
본 보고서는 코팅 유형별(내구성 폴리머 계열, 생체흡수성 폴리머 계열, 폴리머 프리), 소재별(코발트-크롬 합금, 백금-크롬 합금, 스테인리스, 니티놀, 마그네슘 합금/복합재료), 약물 유형별(시롤리무스 및 그 유사체, 기타), 최종 사용자별(병원, 기타), 지역별(북미, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 약물 용출 스텐트 시장 동향 및 인사이트
관상동맥 질환 유병률 증가 및 고령화
세계 관상동맥질환(CAD)의 유병률은 65세 이상 인구가 두 배로 증가하는 속도와 보조를 맞추어 상승하고 있으며, 현재는 1회 시술당 2개 이상의 스텐트 삽입이 필요한 다지 병변을 보이는 환자가 증가하고 있습니다. 이로 인해 예방 심장학의 발전에도 불구하고 스텐트 수요는 유지되고 있습니다. 현재 주요 임상시험에서 의무화된 연령대별 등록을 통해 메디케어 수급자를 대상으로 한 중재 시술의 40%에 대한 데이터의 타당성이 확보되고 있습니다. 한편, 만성 신장병이 동반된 경우, 생체 흡수성 폴리머 스텐트는 장기간에 걸쳐 이물질을 제거할 수 있기 때문에 매력적인 선택지가 되고 있습니다. 유럽과 일본의 노인 심장병 학회는 항혈소판 요법 기간을 단축한 초박형 스트럿 스텐트를 권장하고 있으며, 이 지침은 연령대별 분석에 관한 ISO-14155 규격의 요구 사항 변화와 일치합니다.
PCI 시술 건수 증가와 저침습적 중재술에 대한 선호
2024년, 미국의 연간 PCI 시술 건수는 55만 건에 달했으나, 아시아태평양의 급증은 더욱 두드러졌으며, 중국에서는 농촌 지역의 보험 적용 확대를 배경으로 95만 건의 시술이 기록되었습니다. 요골동맥 접근법이나 당일 퇴원은 이제 일반화되어, 혈관 합병증 감소와 병원의 수용 능력 확보로 이어지고 있습니다. 약물 용출 스텐트 시장 침투가 가속화되고 있습니다. 이는 12개월 시점의 표적 병변 재혈관화율이 5% 이하로 유지되고 있기 때문이며, 이 지표는 보험사의 평가 기준에 포함되어 있습니다.
엄격한 장기 규제상의 증거 요건
유럽의 MDR(의료기기 규정)에서는 모든 생체 흡수성 스캐폴드에 대해 5년간의 추적 조사가 의무화되어 있으며, 이로 인해 주요 임상시험 프로그램에 800만 달러의 추가 비용과 최대 3년의 기간이 더해지게 됩니다. 한편, FDA는 현재 동급 최고의 비교 대상 제품에 대한 직접 비교를 통한 비열등성 시험을 요구하고 있으며, 피험자 수는 최대 3,000명으로 두 배로 늘어났습니다. 시판 후 등록 의무는 최초 1만 건의 이식을 대상으로 하며, 중소기업의 부담을 가중시키는 한편 모니터링의 정확도를 높이고 있습니다.
부문 분석
2025년, 내구성 폴리머 소재 기기는 풍부한 과거 데이터를 바탕으로 약물 용출 스텐트 시장에서 51.44%의 점유율을 차지했으나, 생체 흡수성 코팅은 12개월 내에 분해되어 만성 이물질 반응을 배제할 수 있기 때문에 2031년까지 연평균 성장률(CAGR) 10.36%로 성장할 전망입니다. 폴리머 프리 대체 제품은 2025년에 12%의 점유율에 도달했으며, 현재는 항혈소판 요법의 단기화 전략의 주류를 이루고 있습니다. ISO 10993-13에 따른 독성 검사는 초기 비용을 증가시켰지만, 임상의의 신뢰를 높여 생체 흡수성 플랫폼을 활용한 약물 용출 스텐트 시장 규모가 꾸준히 확대되는 요인이 되고 있습니다.
의료진은 장기간에 걸친 약물 방출이 필요한 복잡한 당뇨병 관련 병변에 대해서는 여전히 내구성이 높은 폴리머를 선택하고 있지만, 주류 사용 경향은 변화하고 있습니다. ACC 2025에서 발표된 BIOFLOW-VI 연구에 따르면, 생체 흡수성 코팅을 사용한 경우 2년 이상 경과 후 발생하는 지연성 스텐트 혈전증이 25% 감소하는 것으로 나타났습니다. 이러한 효과는 기존 플랫폼 시장 점유율 잠식을 가속화하여, 약물 용출 스텐트 시장에서 더 얇고 흡수 속도가 빠른 폴리머로의 전환 추세를 강화할 것으로 예측됩니다.
코발트-크롬은 2025년에도 37.66%의 점유율을 차지하며 여전히 핵심을 이루었지만, 마그네슘 합금 복합재는 12개월 이내에 완전히 흡수되어 혈관 운동이 회복되기 때문에 연평균 성장률(CAGR) 11.77%로 점유율을 급성장하고 있습니다. 백금-크롬 합금은 60마이크로미터라는 가장 얇은 스트럿을 구현하면서도 28%의 점유율을 유지하고 있으며, 높은 방사형 강도가 필요한 석회화된 혈관에서 확고한 입지를 지키고 있습니다. 한편, 외과의사들이 내피화를 촉진하는 것을 우선시함에 따라 스테인리스의 점유율은 한 자릿수 수준으로 축소되었습니다. ISO 10993-15에서 의무화한 동물 모델을 이용한 분해성 검사는 제품 개발 리드타임을 연장시켰지만, 독성에 대한 우려를 불식시키고 신규 금속에 대한 임상의의 수용을 뒷받침하는 동시에, 마그네슘 제 장치에 대한 약물 용출 스텐트 시장 규모 전망을 뒷받침하고 있습니다.
Esprit BTK는 12개월 시점에서 95%의 흡수율을 보이며, 무릎 아래 병변에서 기능 회복을 입증했습니다. 이는 향후 마그네슘 플랫폼의 모델이 되어, 말초 부위에서의 용도를 영구적인 니티놀 케이지에서 전환시키고, 약물 용출 스텐트 시장의 추가적인 다각화를 촉진하는 진전으로 간주됩니다.
지역별 분석
북미는 생체 흡수성 플랫폼의 높은 가격 책정과 적응증이 1개월로 단축되어 적응증 후보가 15만 건 확대된 데 힘입어, 2025년 매출의 39.43%를 차지했습니다. 약물 코팅 풍선이 스텐트 내 재협착 시술의 32%를 대체하고 있어 성장세는 둔화되는 추세이지만, AI 가이드 이미징의 도입이 일부 둔화를 상쇄하고 있어 해당 지역의 약물 용출 스텐트 시장은 여전히 큰 규모를 유지하고 있습니다.
아시아태평양은 2031년 연평균 성장률(CAGR)이 9.21%로 가장 빠르게 성장하고 있는 지역입니다. 이는 중국의 연간 PCI 시술 건수가 100만 건에 육박하고, 국내 제조업체들이 신흥 시장의 가격 상한선을 충족하는 600달러 이하의 기기를 제공하고 있기 때문입니다. 조화로운 신청 절차 덕분에 일본, 한국, 대만, 아세안(ASEAN)에 대한 신청이 한 번으로 해결되어 시장 진입이 간소화되고 수출 확대가 가속화되고 있습니다. 이러한 요인들은 개발도상국 내 약물 용출 스텐트 시장 규모를 확대하는 원동력이 되고 있습니다.
유럽에서는 MDR(의료기기 규정)에 따른 증거 제출 부담으로 어려움을 겪고 있으며, 이로 인해 승인까지의 기간이 2-3년 연장되고, 스텐트 1개당 800만 달러의 추가 비용이 발생하고 있어, 이는 중소기업 시장 진입 장벽이 되고 있습니다. 그럼에도 불구하고, PCI와 CABG의 비율 상승 및 1개월간의 이중 요법 승인으로 인해 수요는 견조한 추세를 보이고 있습니다. 중동 및 아프리카는 6%의 점유율을 차지하고 있지만, 단가가 1인당 의료비의 절반에 상당하기 때문에 보급이 둔화되고 있습니다. 다만, GCC의 카테터실 인프라 투자로 인해 취급량은 서서히 증가하는 추세입니다. 남미는 8%의 점유율을 차지하고 있으며, 이는 주로 브라질에서 연간 18만 건의 PCI 시술이 주도하고 있습니다. 한편, 아르헨티나와 칠레에서는 필수 의료기기로의 지정 확대에 따라 환급 범위가 넓어지면서 두 자릿수의 연평균 성장률(CAGR)을 기록하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the drug eluting stent market size is expected to increase from USD 8.91 billion in 2025 to USD 9.46 billion in 2026 and reach USD 13.28 billion by 2031, growing at a CAGR of 7.03% over 2026-2031.
This report is Segmented by Coating Type (Durable Polymer-Based, Bioresorbable Polymer-Based, Polymer-Free), Material (Cobalt-Chromium Alloy, Platinum-Chromium Alloy, Stainless Steel, Nitinol, Magnesium Alloy/Composite), Drug Type (Sirolimus & Analogues, and More), End User (Hospitals, and More), and Geography (North America, and More). Market Forecasts are Provided in Terms of Value (USD).
Global Drug Eluting Stent Market Trends and Insights
Rising Prevalence of Coronary Artery Disease & Aging Population
Global CAD incidence is rising in lock-step with a doubling of the >= 65-year demographic, and patients now present with multivessel disease that demands two or more implants per procedure, sustaining device volumes despite preventive cardiology gains. Age-stratified enrollment, now mandatory in pivotal trials, ensures data relevance for the 40% of interventions performed in Medicare beneficiaries, while chronic kidney disease comorbidity makes bioresorbable polymer stents attractive because they remove long-term foreign material. Geriatric cardiology societies in Europe and Japan endorse ultra-thin strut scaffolds with abbreviated antiplatelet regimens, guidance that converges with evolving ISO-14155 requirements for age-specific analyses.
Growth in PCI Volumes & Preference for Minimally Invasive Interventions
U.S. annual PCI volume touched 550,000 in 2024, but the Asia-Pacific surge is more pronounced as China logged 950,000 interventions on the back of rural insurance expansion. Radial access and same-day discharge are now commonplace, lowering vascular complications and freeing hospital capacity. Drug-eluting stent market adoption accelerates because target-lesion revascularization remains below 5% at 12 months, a metric embedded in payer scorecards.
Stringent Long-Term Regulatory Evidence Requirements
Europe's MDR obliges five-year follow-up for every bioresorbable scaffold, adding USD 8 million and up to three years to pivotal programs, while the FDA now demands head-to-head non-inferiority against best-in-class comparators, doubling sample size to as many as 3,000 subjects. Post-market registry mandates covering the first 10,000 implants stretch smaller firms yet improve surveillance fidelity.
Other drivers and restraints analyzed in the detailed report include:
- Advances in Polymer Coatings & Ultra-Thin Strut Platforms
- One-Month DAPT Labeling Expanding Eligible Patient Pool
- High Device & Procedure Cost in Low-Income Regions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Durable polymer devices held 51.44% drug-eluting stent market share in 2025, sustained by extensive legacy data, yet bioresorbable coatings are pacing a 10.36% CAGR through 2031 because 12-month degradation eliminates chronic foreign-body reactions. Polymer-free alternatives reached 12% share in 2025 and now headline abbreviated antiplatelet strategies. ISO 10993-13 toxicity assays have raised upfront costs yet boosted clinician confidence, helping the drug-eluting stent market size for bioresorbable platforms climb steadily.
Operators continue to select durable polymers for complex diabetes-associated lesions that require extended drug elution, but mainstream use is shifting. The BIOFLOW-VI trial presented at ACC 2025 showed 25% lower late-stent thrombosis with bioresorbable coatings beyond two years, an effect expected to accelerate cannibalization of older platforms and reinforce the drug-eluting stent market trend toward thinner, faster-absorbing polymers.
Cobalt-chromium remained the backbone with 37.66% share in 2025, yet magnesium alloy composites are outpacing at an 11.77% CAGR as full resorption within 12 months restores vasomotion. Platinum-chromium alloys deliver the thinnest struts-60 µm-while holding 28% share, retaining a foothold in calcified vessels that demand high radial force. Stainless steel shrank to single digits as surgeons prioritize accelerated endothelialization. Animal-model degradation studies mandated by ISO 10993-15 have lengthened product timelines but cleared toxicity concerns, bolstering clinician acceptance of novel metals and supporting the drug-eluting stent market size outlook for magnesium devices.
Esprit BTK's 95% resorption at 12 months demonstrated functional restoration in below-the-knee lesions and provides a template for future magnesium platforms, an advance set to divert peripheral applications from permanent nitinol cages and further diversify the drug-eluting stent market.
Complete Report Scope:
- By Coating Type
- Durable Polymer-based
- Bioresorbable Polymer-based
- Polymer-free
- By Material
- Cobalt-Chromium Alloy
- Platinum-Chromium Alloy
- Stainless Steel
- Nitinol
- Magnesium Alloy / Composite
- By Drug Type
- Sirolimus & Analogues (Everolimus, Zotarolimus, Biolimus A9)
- Paclitaxel
- Dual-therapy / Combination-drug Stents
- By Application
- Coronary Artery Disease
- Peripheral Artery Disease
- By End User
- Hospitals
- Cardiac Catheterization / PCI Centers
- Ambulatory Surgical Centers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 39.43% of 2025 revenue, buoyed by premium pricing for bioresorbable platforms and one-month labeling that widened the candidate pool by 150,000 cases. Growth is moderating as drug-coated balloons cannibalize 32% of in-stent restenosis procedures, yet AI-guided imaging adoption offsets some deceleration, keeping the regional drug-eluting stent market sizable.
Asia-Pacific is the fastest-growing region at a 9.21% CAGR through 2031 as China's annual PCI volumes approach 1 million and domestic manufacturers offer sub-USD 600 devices that satisfy emerging-market price ceilings. Harmonized dossier pathways now allow a single submission for Japan, South Korea, Taiwan, and ASEAN, streamlining access and accelerating export diffusion, catalysts that elevate the drug-eluting stent market size across developing economies.
Europe, wrestles with MDR-instigated evidence burdens that lengthen approvals by two to three years and cost another USD 8 million per scaffold, a deterrent for smaller firms. Nonetheless, rising PCI-to-CABG ratios and one-month dual-therapy endorsements maintain steady demand. Middle East & Africa, at 6%, suffers adoption drag from unit prices equaling half of per-capita health spending, though GCC investment in cath-lab infrastructure is nudging volumes higher. South America holds 8% share, driven largely by Brazil's 180,000 annual PCIs, while Argentina and Chile post double-digit CAGR as essential-device listings expand reimbursement coverage.
- Abbott Laboratories
- Alvimedica
- B. Braun
- Balton Sp.z.o.o
- Biosensors International Group, Ltd.
- BIOTRONIK
- Boston Scientific
- Cook Group
- Elixir Medical
- Johnson & Johnson Services LLC
- JW Medical Systems
- Lepu Medical
- Medtronic
- Meril Life Science
- MicroPort
- OrbusNeich Medical
- Sahajanand Medical Technologies Pvt. Ltd.
- Sino Medical Sciences Technology Inc.
- Terumo
- Translumina
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Coronary Artery Disease & Aging Population
- 4.2.2 Growth in PCI Volumes & Preference for Minimally-Invasive Interventions
- 4.2.3 Advances in Polymer Coatings & Ultra-Thin Strut Platforms
- 4.2.4 One-Month DAPT Labeling Expanding Eligible Patient Pool
- 4.2.5 Domestic Low-Cost DES Production Boosting Adoption in Emerging Asia
- 4.2.6 AI-Guided Intravascular Imaging Improving Stent Placement Success
- 4.3 Market Restraints
- 4.3.1 Stringent Long-Term Regulatory Evidence Requirements
- 4.3.2 High Device & Procedure Cost in Low-Income Regions
- 4.3.3 Supply-Chain Vulnerabilities in Medical-Grade Polymers & Apis
- 4.3.4 Competitive Cannibalization from Drug-Coated Balloons In ISR/Small Vessels
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Coating Type
- 5.1.1 Durable Polymer-based
- 5.1.2 Bioresorbable Polymer-based
- 5.1.3 Polymer-free
- 5.2 By Material
- 5.2.1 Cobalt-Chromium Alloy
- 5.2.2 Platinum-Chromium Alloy
- 5.2.3 Stainless Steel
- 5.2.4 Nitinol
- 5.2.5 Magnesium Alloy / Composite
- 5.3 By Drug Type
- 5.3.1 Sirolimus & Analogues (Everolimus, Zotarolimus, Biolimus A9)
- 5.3.2 Paclitaxel
- 5.3.3 Dual-therapy / Combination-drug Stents
- 5.4 By Application
- 5.4.1 Coronary Artery Disease
- 5.4.2 Peripheral Artery Disease
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Cardiac Catheterization / PCI Centers
- 5.5.3 Ambulatory Surgical Centers
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 United Kingdom
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Alvimedica
- 6.3.3 B. Braun Melsungen AG
- 6.3.4 Balton Sp.z.o.o
- 6.3.5 Biosensors International Group, Ltd.
- 6.3.6 Biotronik SE & Co. KG
- 6.3.7 Boston Scientific Corporation
- 6.3.8 Cook Medical Inc.
- 6.3.9 Elixir Medical Corporation
- 6.3.10 Johnson & Johnson Services LLC
- 6.3.11 JW Medical Systems
- 6.3.12 Lepu Medical Technology Co., Ltd.
- 6.3.13 Medtronic plc
- 6.3.14 Meril Life Sciences Pvt. Ltd.
- 6.3.15 MicroPort Scientific Corporation
- 6.3.16 OrbusNeich Medical
- 6.3.17 Sahajanand Medical Technologies Pvt. Ltd.
- 6.3.18 Sino Medical Sciences Technology Inc.
- 6.3.19 Terumo Corporation
- 6.3.20 Translumina GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


