

|
시장보고서
상품코드
2123737
비디오월 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Video Wall - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
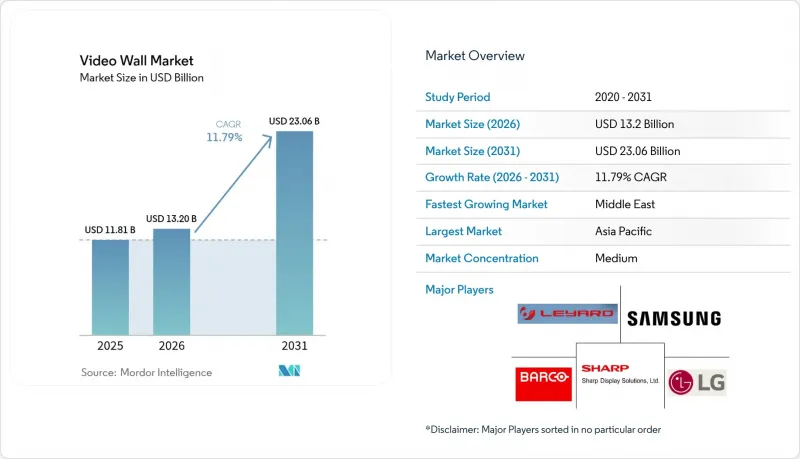
에 의하면, 비디오월시장 규모는 2025년에 118억 1,000만 달러로 평가되었고 2026년 132억 달러에서 2031년까지 230억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 11.79%를 나타낼 전망입니다.
본 보고서는 기술별(LCD, LED, 리어 프로젝션 큐브, 마이크로 LED), 최종 사용자별(소매, 운송 등), 디스플레이 유형별(직접 뷰, 타일형 LCD 패널, 리어 프로젝션 큐브), 설치 장소별(실내, 실외),및 지역별(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 비디오월 시장 동향 및 인사이트
MicroLED 비디오월 솔루션의 부상
MicroLED는 픽셀 단위의 밝기 조절 기능과 1,000,000:1을 초과하는 명암비를 실현하고 있으며, 이러한 특성은 현재 방송 스튜디오나 고급 소매점을 대상으로 한 RFP(제안 요청서)에 명시되어 있습니다. 2024년에 상용화된 삼성의 ‘The Wall’과 LG의 ‘MAGNIT’은 OLED에서 볼 수 있는 유기층을 제거함으로써 수명을 100,000시간 이상으로 연장하고 번인 위험을 해소했습니다. 2025년 초 도쿄에 도입될 소니의 ‘Crystal LED’는 주변 환경 변화에 관계없이 출력을 조정하는 AI 기반 색상 보정 기능을 갖추고 있습니다. 대만의 파운드리 업체들은 수율 향상과 가격 인하를 도모하기 위해 8인치 사파이어로의 전환을 추진하고 있으며, 이로 인해 27.47%의 예측 성장률이 가능해졌습니다. 많은 공공시설에서 현재 IEC 62341의 광생물학적 안전성 기준 준수가 필수로 요구되고 있습니다.
교통 거점에서의 LED 비디오월 도입 확대
공항 및 지하철 운영 사업자들은 실시간 항공편 정보와 승강장 정보를 표시하면서 다이내믹 광고를 전달함으로써, 이용자의 체류 시간을 수익원으로 전환하고 있습니다. 에든버러 공항의 12미터 곡면 LED 월과 캔자스시티의 새로운 터미널에 설치된 18대의 직접 뷰 디스플레이는 모두 2024년에 가동을 시작했습니다. 인천공항의 24미터 리본형 디스플레이는 얼굴 인식 기능을 통합하여 컨텐츠를 개인화하고 있지만, 이 점에 대해 EU 규제 당국으로부터 개인정보 보호에 관한 면밀한 조사를 받고 있습니다. 2.3%의 성장률 상승은 이러한 24시간 365일 가동되는 시설들이 지속적인 수익을 보장하는 10년짜리 서비스 계약을 체결했기 때문입니다.
높은 초기 투자 비용과 총 소유 비용
고급 마이크로 LED 어레이는 1제곱미터당 5,000달러를 초과하기도 하여, 교육 기관이나 지자체 등의 구매자들이 해상도가 낮은 LCD 제품으로 눈을 돌리게 하고 있습니다. 2024년에 여러 공항 운영사가 실시한 5년간의 총 소유 비용 조사에 따르면, 20개 패널로 구성된 LED 월의 비용은 약 32만 달러인 반면, 타일 형태로 배치된 LCD는 18만 달러였습니다. 다만, LED의 긴 수명과 낮은 고장률을 고려하면 그 차이는 줄어듭니다. 예산 확보를 위해 기업 고객들은 하드웨어, 설치, 유지보수를 월정액으로 묶고, 부품 고장 위험을 공급업체가 부담하도록 하는 방식을 채택하고 있습니다. 환율 변동과 관세로 인해 남미와 아프리카에서는 현지 도착 가격이 최대 50%나 상승하여, 리스가 주요 도입 수단이 되고 있습니다.
부문 분석
LED는 2025년 매출의 45.74%를 차지하며, 근거리에서도 매끄러운 영상을 보장하는 1.2mm 미만의 픽셀 피치 덕분에 비디오월 시장의 기반을 형성하고 있습니다. 마이크로 LED는 고급 소매점, 방송 업계, 기업 로비 등의 구매자들이 거의 무한한 명암비와 10만 시간의 수명을 선호함에 따라 2031년까지 연평균 성장률(CAGR) 26.11%로 성장할 전망입니다. LCD는 1mm 미만의 베젤 폭이라는 장점은 있지만, 연중무휴 24시간 가동 환경에서는 휘도 균일성이 급격히 저하되기 때문에 주목도가 높은 프로젝트에서의 채택이 감소하고 있습니다. 또한, LED가 램프 교체 필요성을 없애고 확장성을 단순화함에 따라, 리어 프로젝션형 큐브는 계속해서 제어실 사양에서 제외되고 있습니다.
각 제조업체는 질화갈륨 웨이퍼 확보와 2024년 Mini-LED 시장을 뒤흔든 가격 변동을 완화하기 위해 칩 생산 라인의 수직 통합을 추진하고 있습니다. 2024년 4월 소니가 MicroLED를 자체 생산하기로 결정한 것은 프리미엄 브랜드들 사이에서 엔드투엔드 관리로 전환하는 광범위한 추세를 여실히 보여줍니다. LCD는 예산에 민감한 교육 기관이나 2차 제어실에서 LED에 비해 40% 이상의 자본 비용을 절감할 수 있기 때문에 여전히 매력적입니다.
2025년 비디오월 시장 매출 중 운송 부문이 28.22%를 차지했습니다. 이는 비행 데이터와 광고를 결합한 터미널 전체의 업그레이드가 주도한 결과입니다. 호스피탈리티 및 엔터테인먼트 분야는 스폰서십을 통해 몰입형 환경을 수익화하는 시설에 힘입어 연평균 성장률(CAGR) 20.29%를 나타낼 것으로 예측됩니다. 소매 분야는 여전히 큰 규모를 유지하고 있지만, 체인점들이 전자상거래 인프라 구축을 우선시하고 2차적인 매장 개보수를 미루고 있어 성장 속도는 둔화되고 있습니다. 기업 사용자들은 화상 회의와 대면 회의의 존재감을 융합하기 위해 하이브리드 회의 공간에 베젤이 얇은 비디오월을 도입하고 있으며, 비용 측면에서 LCD를 선호하는 경향이 있습니다.
정부 및 유틸리티 분야는 꾸준히 발전하고 있지만, 수년에 걸친 조달 주기에 제약을 받고 있습니다. 한편, 교육·의료 분야에서는 교육 및 소프트웨어가 포함된 턴키형 패키지가 요구되고 있습니다. ADA(미국 장애인법) 요건을 충족하기 위해 내장형 텍스트 낭독 기능을 포함한 접근성 기능은 현재 표준이 되었습니다.
지역별 분석
아시아태평양은 2025년 매출의 37.92%를 차지하고 있으며, 이는 유럽 및 미국의 동종 업체보다 20-30% 저렴한 가격으로 턴키 시스템을 수출하는 수직 통합형 중국 공급업체에 의해 뒷받침되고 있습니다. 인도의 주요 공항과 대도시권에서는 현재 업그레이드가 진행 중이지만, 일본의 장비 교체는 경제산업성(METI)이 정한 2024년 효율 기준을 준수하고 있습니다. 호주의 광업 지휘 센터에서는 방진 기능이 있고 온도 변화에 강한 모델이 요구되고 있습니다.
중동은 사우디아라비아의 NEOM이나 UAE의 공항 확장 프로젝트에서 햇빛 아래에서도 가시성이 확보되는 50°C 대응 실외용 디스플레이가 요구되고 있어, 2031년까지 연평균 성장률(CAGR)이 13.72%를 나타낼 것으로 예측됩니다. 튀르키예의 소매 그룹은 매장 내 경험을 증진하기 위해 대형 디스플레이 도입을 추진하고 있습니다. 북미에서는 기업들이 LCD 월을 하이브리드 근무 환경에 대응하는 좁은 베젤 LED 모델로 교체함에 따라 시장이 꾸준히 확대되고 있습니다. 유럽의 도입 상황은 엄격한 에너지 규제 및 빛 공해 규제를 반영하고 있습니다. 영국의 교통 허브에서는 10년간의 비용 절감을 목표로 프로젝션 큐브에서 직접 뷰 LED로 전환하고 있습니다. 독일의 자동차 제조업체는 디자인 스튜디오에서 4K 월을 활용하여 도장 및 트림을 실시간으로 시각화하고 있습니다. 프랑스에서는 야간 통행 금지령으로 인해 예산이 실내 시설로 재배정되고 있는 반면, 남미의 성장은 브라질 공항 민영화 프로그램에 따른 관세 인하에 달려 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the video wall market size was valued at USD 11.81 billion in 2025 and estimated to grow from USD 13.2 billion in 2026 to reach USD 23.06 billion by 2031, at a CAGR of 11.79% during the forecast period (2026-2031).
This report is Segmented by Technology (LCD, LED, Rear-Projection Cube, Microled), End-User (Retail, Transportation, and More), Display Type (Direct-View, Tiled LCD Panel, and Rear Projection Cube), Installation Location (Indoor, and Outdoor), and Geography (North America, South America, Europe, Asia-Pacific, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Video Wall Market Trends and Insights
Emergence of MicroLED Video Wall Solutions
MicroLED brings per-pixel dimming and contrast ratios beyond 1,000,000:1, attributes now written into RFPs for broadcast studios and luxury retail. Samsung's The Wall and LG's MAGNIT, commercialized in 2024, eliminate the organic layers found in OLED, extending lifespans beyond 100,000 hours and removing burn-in risk. Sony's Crystal LED installation in Tokyo in early 2025 adds AI-based color calibration that adjusts output regardless of ambient changes. Taiwan-based foundries are shifting to 8-inch sapphire to lift yields and compress pricing, enabling the 27.47% forecast growth. Compliance with IEC 62341 photobiological safety norms is now mandatory in many public installations.
Growing Adoption of LED Video Walls in Transportation Hubs
Airport and metro operators are turning dwell time into revenue by streaming dynamic ads alongside real-time flight or platform data. Edinburgh Airport's 12-meter curved LED wall and Kansas City's new terminal's 18 direct-view displays both went live in 2024. Incheon Airport's 24-meter ribbon integrates facial-recognition triggers to personalize content, drawing privacy scrutiny from EU regulators. The 2.3% growth lift arises because these 24/7 facilities lock in 10-year service contracts that assure recurring revenue.
High Initial Investment and Total Cost of Ownership
Premium MicroLED arrays can top USD 5,000 per square meter, pushing education and municipal buyers toward lower-resolution LCD alternatives. Five-year ownership studies by several airport operators in 2024 show LED walls costing roughly USD 320,000 for a 20-panel build versus USD 180,000 for tiled LCD, though the gap narrows once longer LED lifespans and lower failure rates are factored. To maintain budgets, corporate customers are bundling hardware, installation, and maintenance into fixed monthly fees that place component-failure risk on vendors. Currency swings and tariffs inflate landed costs by up to 50% in South America and Africa, making leasing the primary adoption path.
Other drivers and restraints analyzed in the detailed report include:
- Integration with Command-Center Visualization Platforms
- Expansion of Immersive Venues and eSports Arenas
- Outdoor Light-Pollution Regulations in Major Urban Centers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
LED retained 45.74% of 2025 revenue, anchoring the video wall market thanks to sub-1.2-millimeter pixel pitches that ensure seamless imagery at close range. MicroLED is set to expand at a 26.11% CAGR through 2031 as luxury retail, broadcast, and corporate lobby buyers favor its near-infinite contrast and 100,000-hour lifespan. LCD, while benefiting from bezels under 1 millimeter, is ceding high-profile projects because brightness uniformity degrades faster in 24/7 service. Rear-projection cubes continue to exit control-room specifications as LED eliminates lamp replacements and simplifies scaling.
Manufacturers are vertically integrating chip lines to secure gallium-nitride wafers and blunt pricing swings that rattled Mini-LED in 2024. Sony's April 2024 decision to bring MicroLED fabrication in-house illustrates a broader pivot among premium brands toward end-to-end control. LCD still appeals in budget-sensitive education and secondary control rooms where capital savings exceed 40% versus LED.
Transportation held 28.22% of 2025 revenue in the video wall market, driven by terminal-wide upgrades that combine flight data and advertising. Hospitality and entertainment is forecast to grow at 20.29% CAGR, fueled by venues that monetize immersive environments via sponsorships. Retail remains sizable yet slower as chains prioritize e-commerce infrastructure, deferring secondary-store upgrades. Corporate adopters equip hybrid meeting spaces with narrow-bezel walls that align video conferencing with in-person presence, leaning toward LCD for cost reasons.
Government and utilities progress steadily but are bound by multi-year procurement cycles, while education and healthcare demand turnkey bundles with training and software included. Accessibility features, including embedded text-to-speech, are now standard to satisfy ADA requirements.
Complete Report Scope:
- By Technology
- LCD
- LED
- Rear-Projection Cube
- MicroLED
- By End-User
- Retail
- Transportation
- Government and Public Utilities
- Corporate
- Hospitality and Entertainment
- Others
- By Display Type
- Direct-View Video Wall
- Tiled LCD Panel Wall
- Rear Projection Cube Wall
- By Installation Location
- Indoor
- Outdoor
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
The Asia-Pacific region generated 37.92% of 2025 revenue, sustained by vertically integrated Chinese vendors exporting turnkey systems at prices 20-30% lower than those of Western peers. India's major airports and metros are mid-upgrade, while Japan's replacements align with 2024 efficiency codes from METI. Australia's mining command centers require dust-proof, temperature-tolerant models.
The Middle East is forecast to have a 13.72% CAGR through 2031, as Saudi Arabia's NEOM and the UAE's airport expansions demand sunlight-readable, 50 °C-rated outdoor walls. Retail groups in Turkey are turning to large-format displays to spur in-store experiences. North America advances steadily as enterprises retrofit LCD walls with narrow-bezel LED models compatible with hybrid work suites. European adoption reflects tough energy and light-pollution rules. U.K. transportation hubs move from projection cubes to direct-view LED for 10-year savings. German automakers utilize 4K walls in their design studios to visualize paint and trim in real-time. France's nighttime curfews redirect budgets indoors, while South America's growth hinges on reduced tariffs under Brazil's airport privatization program.
- Samsung Electronics Co., Ltd.
- LG Electronics Inc.
- Leyard Optoelectronic Co., Ltd.
- Barco NV
- Sharp NEC Display Solutions, Ltd.
- Sony Group Corporation
- Panasonic Holdings Corporation
- Christie Digital Systems USA, Inc.
- Unilumin Group Co., Ltd.
- Absen Optoelectronic Co., Ltd.
- Daktronics, Inc.
- ViewSonic Corporation
- Planar Systems, Inc.
- ROE Visual Co., Ltd.
- Shenzhen AOTO Electronics Co., Ltd.
- Delta Electronics, Inc.
- Mitsubishi Electric Corporation
- Toshiba Corporation
- Koninklijke Philips N.V.
- Acer Incorporated
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Adoption of LED Video Walls in Transportation Hubs
- 4.2.2 Increasing Demand for Digital Signage in Retail Environments
- 4.2.3 Advancements in Narrow-Bezel LCD Panels
- 4.2.4 Emergence of MicroLED Video Wall Solutions
- 4.2.5 Integration of Video Walls with Command-Centre Data Visualisation Platforms
- 4.2.6 Expansion of Immersive Entertainment Venues and eSports Arenas
- 4.3 Market Restraints
- 4.3.1 High Initial Investment and Total Cost of Ownership
- 4.3.2 Significant Heat and Power Consumption of Large Displays
- 4.3.3 Supply Chain Volatility for Mini-LED and IC Components
- 4.3.4 Outdoor Light-Pollution Regulations in Major Urban Centres
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 LCD
- 5.1.2 LED
- 5.1.3 Rear-Projection Cube
- 5.1.4 MicroLED
- 5.2 By End-User
- 5.2.1 Retail
- 5.2.2 Transportation
- 5.2.3 Government and Public Utilities
- 5.2.4 Corporate
- 5.2.5 Hospitality and Entertainment
- 5.2.6 Others
- 5.3 By Display Type
- 5.3.1 Direct-View Video Wall
- 5.3.2 Tiled LCD Panel Wall
- 5.3.3 Rear Projection Cube Wall
- 5.4 By Installation Location
- 5.4.1 Indoor
- 5.4.2 Outdoor
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Kenya
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Samsung Electronics Co., Ltd.
- 6.4.2 LG Electronics Inc.
- 6.4.3 Leyard Optoelectronic Co., Ltd.
- 6.4.4 Barco NV
- 6.4.5 Sharp NEC Display Solutions, Ltd.
- 6.4.6 Sony Group Corporation
- 6.4.7 Panasonic Holdings Corporation
- 6.4.8 Christie Digital Systems USA, Inc.
- 6.4.9 Unilumin Group Co., Ltd.
- 6.4.10 Absen Optoelectronic Co., Ltd.
- 6.4.11 Daktronics, Inc.
- 6.4.12 ViewSonic Corporation
- 6.4.13 Planar Systems, Inc.
- 6.4.14 ROE Visual Co., Ltd.
- 6.4.15 Shenzhen AOTO Electronics Co., Ltd.
- 6.4.16 Delta Electronics, Inc.
- 6.4.17 Mitsubishi Electric Corporation
- 6.4.18 Toshiba Corporation
- 6.4.19 Koninklijke Philips N.V.
- 6.4.20 Acer Incorporated
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


