|
시장보고서
상품코드
2123774
태양광 추적기 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Solar Tracker - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
태양광 추적기 시장 규모는 2026년에 733억 5,000만 달러로 추정되고 있어 예측 기간(2026-2031년)에서 CAGR 21.46%로 확대되어 2031년에는 1,938억 9,000만 달러에 이를 전망입니다.
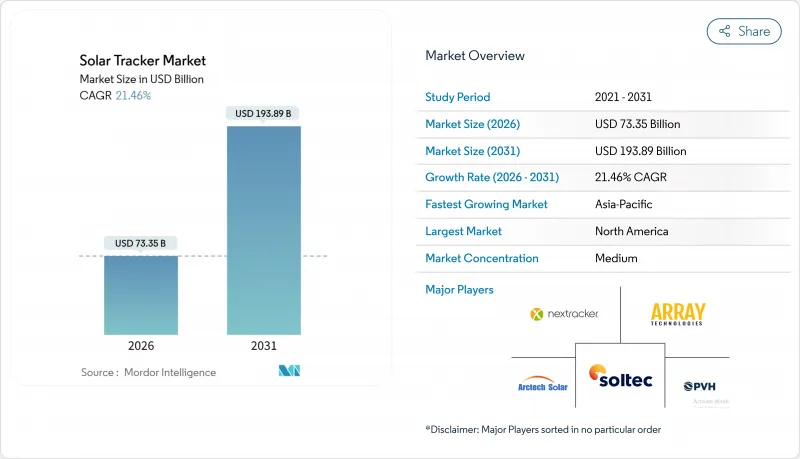
본 보고서는 축의 유형(단축 및 이축), 기술(태양광 발전, 집광형 태양광 발전), 구동 방식(전기 모터, 리니어 액추에이터, 유압), 용도(유틸리티 규모, 상업 및 산업용, 주거·마이크로그리드,아그리볼타익스), 지역(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)별로 분류되어 있습니다.
세계 태양광 추적기 시장 동향 및 인사이트
미국 IRA(인플레이션 억제법)에 힘입어 유틸리티 규모의 PPA가 수 GW 규모의 트래커 계약을 가능하게 하고 있습니다.
투자 세액 공제에서 최대 10퍼센트 포인트의 국내 조달 보너스 크레딧이 적용됨에 따라 공급망 재구성이 진행되었습니다. NEXTracker와 Array Technologies는 Nucor 및 SDI로부터 철강재를 조달하고 뉴멕시코주 및 캘리포니아주의 공장을 확장함으로써 100% 미국산 조달률을 달성하고, 국내 수주량을 전년 대비 40% 증가시켰습니다. 한때 9개월에 달하던 수입 철강의 리드타임이 현재는 10주로 단축되어, 개발 사업자는 세제상의 지분을 더 조기에 수익화할 수 있게 되었습니다. 45배에 달하는 첨단 제조 세액 공제로 인해 철강 자재에 대한 지원이 더욱 강화되어, 열연 코일의 평균 가격이 톤당 750달러라 하더라도 와트당 납품 비용은 낮아지고 있습니다. 이러한 메커니즘이 결합되어, 트래커를 단순한 옵션이 아닌 프로젝트의 기본 설계에 통합할 수 있게 함으로써, 수 기가와트 규모의 PPA(전력 구매 계약) 붐을 뒷받침하고 있습니다.
인도 및 MENA 지역에서 1P 모듈식 설계를 통한 트래커 자본 지출(CapEx)/MW 절감
단일 열 1P 아키텍처를 채택한 인도의 개발 사업자는 철강 사용량과 기초 공사의 감축을 통해 1메가와트당 자본 지출을 15%-20% 절감하여, Solar Energy Corporation의 경매에서 사상 최저 수준의 입찰 가격을 확보하는 데 성공했습니다. 사우디아라비아의 NEOM과 UAE의 5단계 프로젝트 역시 기복이 심한 사막 지대에서의 건설 속도 향상을 이유로 이러한 변화를 반영하고 있습니다. 각 열에 고유한 액추에이터가 장착되어 있어 고장 시 격리성이 향상되고, O&M(운영 및 유지보수)을 위한 현장 방문 횟수가 감소합니다. 이는 사막의 작업자가 현장까지 200km 이상 이동해야 하는 지역에서 중요한 이점이 됩니다. 이 모듈식 모델은 수입 철강재에 비해 인건비가 저렴한 지역에서 특히 매력적이며, 건설사는 열 수를 늘림으로써 와트당 하드웨어 비용을 절감할 수 있습니다.
북미의 구조용 강재 가격 급등과 섹션 232 관세
2024년부터 2025년까지 열연 코일의 평균 가격은 톤당 700-800달러로, 팬데믹 이전 수준보다 약 40% 상승했습니다. 한편, 수입 철강에 대한 25% 관세로 인해 Array Technologies사의 트래커 사업 부문의 매출 총이익률은 320 베이시스 포인트 하락했습니다. ‘섹션 232’에 따른 면제 신청에는 최대 9개월이 소요될 수 있으며, 이로 인해 조달이 지연되어 전력 구매 계약(PPA)에 따른 위약금이 발생할 우려가 있습니다. 소규모 공급업체들이 북미 시장에서 철수함에 따라, 자사 제철소를 통해 안정적인 공급 체계를 갖춘 수직 통합형 기업들 사이에서 시장 점유율이 집중되었습니다.
부문별 분석
2축식 트래커의 설치 대수는 연평균 성장률(CAGR) 22.5%로 확대될 것으로 예측되지만, 2025년에도 단축식 트래커의 출하 대수는 전체의 52.7%를 계속 차지할 것으로 전망됩니다. 단축 설계의 태양광 추적기 시장 점유율은 입증된 신뢰성, 열당 1개의 모터라는 단순한 구조, 그리고 자금 조달에 대한 익숙함 등의 특징에 힘입어, 이러한 특징 덕분에 최근 미국의 유틸리티 건설 프로젝트에서는 거의 보편적으로 채택되고 있습니다. 그러나 칠레의 아타카마나 호주의 필바라에서는 토지 및 일사 조건이 에너지 밀도를 높이기 때문에 발전량을 25%-35% 증가시키는 대가로 개발업자들은 하드웨어 비용이 30%-40% 높아지는 것을 용인하고 있습니다.
축전 시스템과 결합된 프로젝트의 경우, 일조 시간이 연장됨에 따라 배터리의 충방전 사이클 수가 감소하기 때문에 2축식 시스템의 프리미엄성이 더욱 매력적으로 다가옵니다. AllEarth Renewables사와 Deger Energie사는 설치 면적 제약이 설비 투자(CAPEX)보다 우선시되는 상업 및 산업(C&I)용 옥상 시장에서 독자적인 틈새 시장을 개척하고 있습니다. 앞으로 리튬 이온 배터리 비용의 하락으로 인해 광활한 토지를 보유한 지역에서의 2축 추적 시스템 도입은 둔화될 가능성이 있지만, 철도 연선, 항만 및 섬의 마이크로그리드에서는 이 기술의 컴팩트함이 태양광 추적 장치 시장의 추가 성장을 확실히할 것입니다.
결정질 실리콘의 비용 하락과 금융 기관의 신뢰 덕분에, 2025년 도입 실적에서 태양광 추적기는 85.5%를 차지했습니다. CPV(집광형 태양광 발전) 트래커는 현재로서는 극히 일부에 불과하지만, 해수 담수화 플랜트나 광산 등이 부지 확보를 최소화하면서 40%-47%의 모듈 효율을 추구하고 있어 연평균 성장률(CAGR) 26.6%로 확대되고 있습니다. 칠레 소이테크(Soytec)사의 시스템과 호주의 인솔라이트(Insolite)사의 어레이는 방진 대책이 마련된 현장에서 CPV의 실현 가능성을 입증했으나, 2축 트래커의 정밀도 유지 및 광학계 세척의 필요성으로 인해 운영 비용(OPEX)은 여전히 높은 수준을 유지하고 있습니다.
주류인 PV 트래커는 양면 패널과의 통합이 용이하고 능동적인 냉각이 필요하지 않기 때문에 태양광 추적기 시장에서 여전히 가장 큰 점유율을 차지하고 있습니다. CSP 트래커는 열 저장을 통해 저녁 시간대 수요를 충당하고 있는 모로코와 UAE에 여전히 집중되어 있습니다. CPV가 시스템 전체의 비용을 절감하고 25년간의 내구성을 입증하지 않는 한, 그 역할은 대중 시장을 겨냥한 도전자로 보기보다는 특수한 추가 설비에 그칠 것입니다.
지역별 분석
2025년 북미의 점유율이 73.0%를 나타낼 것이라는 점은 IRA(인플레이션 억제법)에 따른 호재를 여실히 보여줍니다. NextEra Energy나 AES와 같은 전력 회사들은 수 기가와트 규모의 국내 조달 요건이 포함된 트래커 발주 계약을 체결하고, 보너스 크레딧을 확보하기 위해 Nucor사의 강재와 미국 공급업체의 모터 조달을 확정했습니다. 그러나 섹션 232에 따른 관세와 톤당 750달러에 달하는 열연 코일 가격은 중소규모 EPC 기업의 이익률을 위협하고 있으며, 업계 재편을 촉진하고 있습니다. 캐나다에서는 각 주에서 발주한 ‘에너지 저장 + 태양광 발전’ RFP(제안 요청서)를 배경으로 완만한 진전이 보이는 반면, 멕시코에서는 관세 회피를 위해 마키라도라의 생산 능력을 활용하고 있습니다.
아시아태평양은 27.9%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 인도의 50GW에 달하는 입찰 프로젝트에서는 설비 투자를 15%-20% 절감할 수 있는 1P 모듈식 트래커가 선호되고 있습니다. 호주의 계통 연계 규정에 따라 웨스턴 다운즈와 완당 사우스에서는 2축 트래커 도입이 진행되고 있으며, 발전 시간 연장으로 인해 축전지의 왕복 효율이 향상되고 있습니다. 중국의 수출업체들은 동남아시아 시장을 독점하고 있지만, 일본과 호주에서는 IEC-62817에 기반한 대출 적격성 장벽에 직면해 있습니다.
유럽에서는 ‘REPowerEU’에 힘입어 도입이 가속화되고 있습니다. 독일의 농업용 태양광 발전에 대한 우대 임베디드 가격, 프랑스의 1.2 GW 승인, 스페인의 양면 수광형 트래커 도입 계획이 성장의 기반이 되고 있지만, 한편 북유럽 국가들에서는 동결 위험으로 인해 설치가 주춤하고 있습니다. 중동에서는 NEOM 및 두바이 페이즈 V가 사막 내 건설을 신속히 진행하기 위해 1P 트래커를 채택하고 있으며, 남아프리카공화국의 에너지 저장 연동형 입찰에서는 듀얼 축 정밀 트래커가 선호되고 있습니다. 사하라 이남 아프리카에서는 O&M(운영·유지보수) 및 기술자 부족으로 인해 진전이 더딘 반면, 라틴아메리카에서는 칠레의 아타카마 지역과 브라질 북동부에 수요가 집중되고 있습니다. 이러한 지역은 직사 일사량이 높고 토지 비용이 저렴하여 자금 조달의 확실성이 높아지고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the solar tracker market size is estimated at USD 73.35 billion in 2026, and is expected to reach USD 193.89 billion by 2031, at a CAGR of 21.46% during the forecast period (2026-2031).
This report is Segmented by Axis Type (Single Axis and Dual Axis), Technology (Photovoltaic, Concentrated Solar Power, and Concentrated Photovoltaic), Drive Type (Electric Motor, Linear Actuator, and Hydraulic), Application (Utility-Scale, Commercial and Industrial, Residential and Micro-Grid, and Agrivoltaics), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Solar Tracker Market Trends and Insights
U.S. IRA-Fueled Utility-Scale PPAs Unlocking Multi-GW Tracker Contracts
Domestic-content bonus credits worth up to 10 percentage points on the investment tax credit have redrawn supply chains. NEXTracker and Array Technologies achieved 100% U.S. content by sourcing steel from Nucor and SDI and expanding New Mexico and California plants, lifting domestic orders 40% year over year. Lead times that once stretched nine months for imported steel now compress to ten weeks, letting developers monetize tax equity sooner. The 45X advanced-manufacturing credit further subsidizes steel inputs, lowering delivered cost per watt even as hot-rolled coil averages USD 750 per ton. Together, these mechanisms underpin a multi-gigawatt PPA wave that locks trackers into baseline project design rather than optional scope.
Diminishing Tracker CapEx/MW via 1P Modular Designs in India & MENA
Indian developers adopting single-row 1P architectures trimmed capital outlay 15%-20% per megawatt by reducing steel tonnage and foundation work, helping them clear record-low Solar Energy Corporation auction tariffs. Saudi Arabia's NEOM and the UAE's Phase V projects mirror the shift, citing faster erection on variable desert terrain. Because each row has its own actuator, fault isolation improves, and O&M visits fall, a key benefit where desert crews travel over 200 km to the site. The modular model is especially attractive in regions where labor is inexpensive relative to imported steel, letting builders trade higher row counts for lower per-watt hardware spend.
Elevated Structural Steel Prices & Section 232 Tariffs in North America
Hot-rolled coil averaged USD 700-800 per ton during 2024-2025, about 40% above pre-pandemic norms, while 25% tariffs on imported steel squeezed tracker gross margins by 320 basis points for Array Technologies. Section 232 exemption requests can take nine months, delaying procurement and triggering PPA penalties. Smaller suppliers exited North America, consolidating share among vertically integrated players with captive mill supply.
Other drivers and restraints analyzed in the detailed report include:
- Bifacial-Optimized Trackers Raising IRR in High-Albedo Regions
- Aggressive 24/7 Renewable Procurement by U.S. Cloud & Mining Firms
- Tracker Failure Risk on Frost-Heave Sites-Nordic & Alpine Utility Farms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dual-axis installations are forecast to expand at a 22.5% CAGR, while single-axis installations retained 52.7% of shipments in 2025. The solar tracker market share for single-axis designs is anchored by proven reliability, one-motor-per-row simplicity, and financing familiarity, features that delivered near-ubiquity in recent U.S. utility builds. Yet developers in Chile's Atacama and Australia's Pilbara accept 30%-40% higher hardware cost in exchange for 25%-35% more generation, where land and irradiance conditions reward energy density.
The dual-axis premium gains additional appeal in storage-paired projects because longer daylight capture reduces battery cycling depth. AllEarth Renewables and Deger Energie have carved niches on C&I rooftops where footprint limits trump capex. Looking forward, falling lithium-ion costs may temper dual-axis adoption in land-abundant geographies, but in rail-side, port, and island microgrids, the technology's compactness is likely to secure incremental solar tracker market growth.
Photovoltaic trackers commanded 85.5% of 2025 deployments thanks to crystalline-silicon cost declines and lender comfort. CPV trackers, while only a sliver today, are scaling at 26.6% CAGR as desalination plants and mines pursue 40%-47% module efficiency that shrinks land take. Soitec systems in Chile and Insolight arrays in Australia proved CPV viability in dust-controlled sites, though dual-axis precision and optical cleaning needs keep opex high.
Mainstream PV trackers retain the largest slice of the solar tracker market size because they integrate easily with bifacial panels and need no active cooling. CSP trackers remain concentrated in Morocco and the UAE, where thermal storage backs evening demand. Unless CPV reduces balance-of-system cost and shows 25-year durability, its role will remain a specialized add-on rather than a mass-market challenger.
Complete Report Scope:
- By Axis Type
- Single Axis
- Dual Axis
- By Technology
- Photovoltaic (PV)
- Concentrated Solar Power (CSP)
- Concentrated Photovoltaic (CPV)
- By Application
- Utility-Scale
- Commercial and Industrial
- Residential and Micro-grid
- Agrivoltaics/Agri-solar
- By Drive Type
- Electric Motor
- Linear Actuator
- Hydraulic
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Spain
- Nordic Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
North America's 73.0% 2025 share underscores IRA tailwinds. Utilities such as NextEra Energy and AES signed multi-gigawatt domestic-content tracker orders, locking in steel from Nucor and motors from U.S. suppliers to secure bonus credits. Section 232 tariffs and hot-rolled coil at USD 750 per ton, however, threaten margins for smaller EPCs, prompting consolidation. Canada inches forward under provincial storage-plus-solar RFPs, while Mexico leverages maquiladora capacity to avoid tariffs.
Asia-Pacific delivers the fastest 27.9% CAGR. India's 50 GW tender pipeline favors 1P modular trackers that cut capex 15%-20%. Australia's grid-forming rule drives dual-axis uptake at Western Downs and Wandoan South, where extended output improves battery round-trip efficiency. Chinese exporters dominate Southeast Asia but face IEC-62817 bankability barriers in Japan and Australia.
Europe accelerates under REPowerEU. Germany's premium tariff for agrivoltaics, France's 1.2 GW approvals, and Spain's bifacial-tracker pipeline anchor growth, while frost-heave risk slows Nordic installs. In the Middle East, NEOM and Dubai Phase V adopt 1P trackers to speed desert builds; South Africa's storage-linked tenders favor dual-axis precision. Sub-Saharan Africa lags due to O&M skill shortages, and Latin America concentrates demand in Chile's Atacama and Brazil's northeast, where direct irradiance and low land cost aid bankability.
- NEXTracker Inc.
- Array Technologies Inc.
- Arctech Solar Holdings Co. Ltd.
- Soltec Power Holdings S.A.
- PV Hardware Solutions S.L.U.
- Valmont Industries Inc. (Convert Italia)
- Trina Solar Co. Ltd. (TrinaTracker)
- GameChange Solar
- Ideematec Deutschland GmbH
- Meca Solar
- STI Norland
- Antai Solar
- SunPower Corporation
- FTC Solar
- Abengoa Solar S.A.
- AllEarth Renewables
- Deger energie GmbH
- Mahindra Susten
- Solar FlexRack
- Convert Italia S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Drivers
- 4.1.1 U.S. IRA-fuelled Utility-Scale PPAs Unlocking Multi-GW Tracker Contracts
- 4.1.2 Diminishing Tracker Cap-Ex/ MW via 1P Modular Designs in India & MENA
- 4.1.3 Bifacial-Optimized Trackers Raising IRR in High-Albedo Regions (Atacama, Nordics)
- 4.1.4 Aggressive 24/7 Renewable Procurement by U.S. Cloud & Mining Firms
- 4.1.5 EU REPower Acceleration of Agrivoltaics - Slim-Row Trackers for Cropland
- 4.1.6 Grid-Forming Storage-Coupled Projects Pushing Dual-Axis Adoption in Australia
- 4.2 Market Restraints
- 4.2.1 Elevated Structural Steel Prices & Section 232 Tariffs in North America
- 4.2.2 Tracker Failure Risk on Frost-Heave Sites-Nordic & Alpine Utility Farms
- 4.2.3 Scarcity of Skilled O&M Crews for Decentralized Actuators in SSA
- 4.2.4 Bankability Concerns for New Chinese Entrants Without IEC 62817 Testing
- 4.3 Supply-Chain Analysis
- 4.4 Regulatory Outlook
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Consumers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Axis Type
- 5.1.1 Single Axis
- 5.1.2 Dual Axis
- 5.2 By Technology
- 5.2.1 Photovoltaic (PV)
- 5.2.2 Concentrated Solar Power (CSP)
- 5.2.3 Concentrated Photovoltaic (CPV)
- 5.3 By Application
- 5.3.1 Utility-Scale
- 5.3.2 Commercial and Industrial
- 5.3.3 Residential and Micro-grid
- 5.3.4 Agrivoltaics/Agri-solar
- 5.4 By Drive Type
- 5.4.1 Electric Motor
- 5.4.2 Linear Actuator
- 5.4.3 Hydraulic
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Spain
- 5.5.2.5 Nordic Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Malaysia
- 5.5.3.6 Thailand
- 5.5.3.7 Indonesia
- 5.5.3.8 Vietnam
- 5.5.3.9 Australia
- 5.5.3.10 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Colombia
- 5.5.4.4 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Products & Services, Recent Developments)
- 6.4.1 NEXTracker Inc.
- 6.4.2 Array Technologies Inc.
- 6.4.3 Arctech Solar Holdings Co. Ltd.
- 6.4.4 Soltec Power Holdings S.A.
- 6.4.5 PV Hardware Solutions S.L.U.
- 6.4.6 Valmont Industries Inc. (Convert Italia)
- 6.4.7 Trina Solar Co. Ltd. (TrinaTracker)
- 6.4.8 GameChange Solar
- 6.4.9 Ideematec Deutschland GmbH
- 6.4.10 Meca Solar
- 6.4.11 STI Norland
- 6.4.12 Antai Solar
- 6.4.13 SunPower Corporation
- 6.4.14 FTC Solar
- 6.4.15 Abengoa Solar S.A.
- 6.4.16 AllEarth Renewables
- 6.4.17 Deger energie GmbH
- 6.4.18 Mahindra Susten
- 6.4.19 Solar FlexRack
- 6.4.20 Convert Italia S.p.A.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment