|
시장보고서
상품코드
2125653
유럽의 태양광 추적기 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Solar Tracker - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
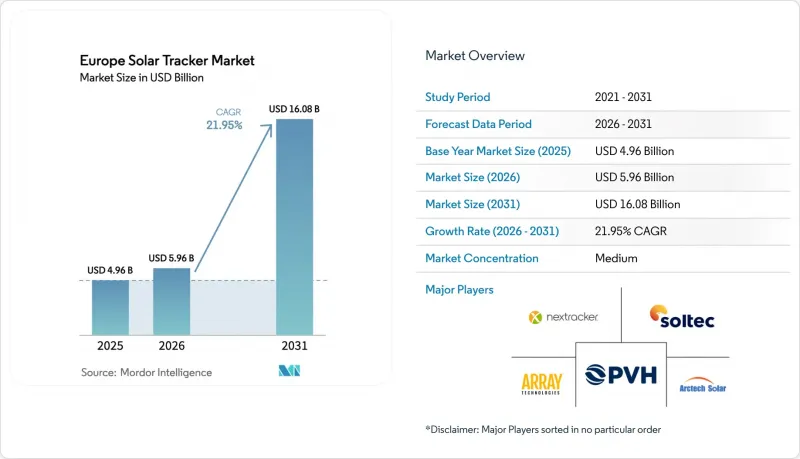
유럽의 태양광 추적기 시장 규모는 2025년에 49억 6,000만 달러로 평가되었고, 2026년에 59억 6,000만 달러로 추정되고, 2031년까지 160억 8,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 21.95%로 성장할 전망입니다.
본 보고서는 축의 유형별(단축 및 이축), 기술별(태양광 발전, 집광형 태양광 발전), 구동 방식별(전기 모터, 리니어 액추에이터, 유압), 용도별(유틸리티 규모, 상업 및 산업용, 주택·마이크로그리드, 아그리볼타익/아그리솔라), 그리고 지역별(영국, 독일, 프랑스, 이탈리아, 스페인, 네덜란드 등)로 분류되어 있습니다.
유럽의 태양광 추적기 시장 동향 및 인사이트
남유럽 전역의 풍부한 일사량
안달루시아와 시칠리아에서는 연간 일사량이 1,800 kWh/m²를 초과하며, 이로 인해 트래커의 에너지 생산량은 고정 경사형에 비해 15-20% 향상되었고, 투자 회수 기간은 2년 미만으로 단축되었습니다. 스페인에서는 2024년에 9.4GW의 신규 태양광 발전 용량이 추가되었으며, 그 선두에는 여름철 피크 출력을 최대한 활용하기 위해 단축 추적기를 채택한 590 MW 규모의 프란시스코 피사로 발전소가 있습니다. 이탈리아의 2024년 신규 도입 용량 5.3 GW에는 밝은 색의 토양 위에서 뒷면의 발전량을 극대화하는 트래커가 장착된 양면 수광형 모듈을 채택한 여러 프로젝트가 포함되어 있었습니다. 그리스도 이에 발맞추어 2025년 6월, 넥스트래커(Nextracker)는 오리케이오 PPC 프톨레마이다 재개발 프로젝트를 위해 550 MW 규모의 수주를 확보했습니다. 이는 트래커가 석탄 채굴 잔여지에서 얼마나 큰 부가가치를 창출할 수 있는지를 여실히 보여줍니다. 북유럽은 일사량이 적고 적설 하중도 크기 때문에 이러한 요인의 영향은 제한적이지만, 남유럽의 외딴 지역의 우위는 여전히 장기적인 성장의 주축이 되고 있습니다.
EU 그린딜 및 REPowerEU의 태양광 발전 목표
REPowerEU에 따라 EU의 2030년까지 태양광 발전 누적 목표는 700GW로 상향 조정되었으며, 이는 연간 약 60GW의 건설 속도에 해당하며, 2023년 속도의 2배에 달할 전망입니다. 독일의 인허가 제도 개혁으로 1MW를 초과하는 지상 설치형 어레이의 승인 주기가 9개월로 단축되어, 트래커 도입에 적합한 광대한 부지를 활용할 수 있게 되었습니다. 스페인은 2024년 6월 입찰에서 3.8GW의 용량을 확보했으며, 낙찰 가격은 평균 0.029유로/kWh를 기록했습니다. 이에 따라 저가 PPA를 이행하기 위한 기본 선택지로서 트래커의 입지가 더욱 공고해졌습니다. 프랑스의 CRE-7 입찰에서는 3.7GW가 배정되었으나, 여전히 지역 주민들의 반대에 직면하고 있어 각국별로 이행 속도에 차이가 있음을 보여주고 있습니다. 개정된 재생에너지 지침에서 의무화된 ‘재생에너지 가속화 지역’의 신속한 구축을 통해 2027년까지 새로운 부지가 확보될 것으로 전망되며, 에너지 밀도를 극대화할 수 있는 트래커 시스템에 대한 수요가 지속될 것으로 예측됩니다.
높은 초기 설비 투자(CAPEX) vs. 고정 경사형
단축 트래커는 고정식보다 15-25%(0.08-0.12달러/WDC) 정도 비싼 편이며, 일사량이 적은 시장이나 금리가 높은 시장에서는 투자 회수 기간이 최대 1년 정도 늘어날 가능성이 있습니다. 폴란드와 루마니아의 개발업체들은 부채 상환 비용을 최소화하기 위해 트래커 도입률을 30% 미만으로 억제하고 있습니다. 옥상 설치가 주류를 이루는 독일 시장도 마찬가지로, 보다 단순한 고정식 시스템을 선호하고 있습니다. 유럽중앙은행(ECB)의 통화정책 전환이 이루어진다면, 할인율 인하를 통해 이러한 부정적 요인은 완화되겠지만, 단기적으로는 역풍이 지속될 것으로 보입니다.
부문 분석
2025년에는 2축 추적 시스템 도입이 신규 매출의 42.5%를 차지하며 연평균 성장률(CAGR) 23.0%로 확대되었으며, 이는 유럽 태양광 추적 시스템 시장 전체 성장률을 약 1% 상회하는 속도일 것입니다. 그렇지만 단축 추적 시스템은 비용이 15-20% 저렴하고 유지보수 절차도 간단하기 때문에 총 설치량에서는 여전히 주류를 차지하고 있습니다. 스페인에서는 평탄한 지형과 높은 일사량을 활용하여 2024년 9.4GW의 설치량 중 약 70%에 단축 추적기가 도입되었습니다. 반면, 이탈리아의 농업용 태양광 발전(아그리볼타익)에 대한 보조금 제도로 인해, 작물 생육의 중요한 단계에서 작물을 피해 방향을 바꿀 수 있는 2축 시스템이 우위를 점하고 있습니다.
규모의 경제 측면에서는 여전히 단축형 대형 제조업체가 우위를 점하고 있습니다. Nextracker사는 2025 회계연도에 전 세계적으로 33.6GW를 출하했으나, 이중축 공급업체 중 1GW를 돌파한 기업은 없었습니다. 하지만 지형에 적응하는 하이브리드형 시스템 덕분에 분류의 경계가 점차 모호해지고 있습니다. 그리스의 550MW 규모 프톨레마이다 재생 프로젝트에서는 지반 침하 구역의 기복에 따라 배치된 관절식 단축 추적기 열이 채택되어, 추가 비용을 전혀 부담하지 않으면서도 듀얼 축 추적기의 많은 이점을 누리고 있습니다. 독일 북부와 같이 일사량이 적은 지역에서는 개발업자들이 수익성을 확보하기 위해 고정 경사형이나 기본적인 단축 추적형을 계속 우선적으로 선택하고 있습니다.
2025년에는 표준형 PV가 87.1%의 점유율을 차지하며 주류를 이루었으나, CPV는 남유럽의 2,000 kWh/m²를 초과하는 DNI(직달 일사량) 지역을 활용함으로써 2031년까지 연평균 성장률(CAGR) 27.1%를 나타낼 것으로 예측됩니다. CPV의 모듈 효율 30-35%가 40-50%의 설비 투자(CAPEX) 프리미엄을 상쇄할 수 있는 것은 스페인, 그리스 및 이탈리아의 일부 지역으로 한정됩니다. 이베르드롤라의 프란시스코 피사로 발전소는 양면 수광형 PV 트래커가 뒷면에서 8-10%의 발전량 증가분을 확보하여, 많은 입찰에서 CPV를 제치고 있는 실례를 보여주고 있습니다.
유럽의 CPV용 태양광 추적기 시장 규모는 여전히 5억 달러 미만이지만, 연구 기관 및 EPC 사업자가 진행하는 초기 단계의 시범 프로젝트는 토지가 제한된 지역에서 초고효율 어레이가 틈새 시장으로서 미래성이 있음을 시사하고 있습니다. 대조적으로, CSP용 트래커는 1kWh당 0.10-0.15달러의 LCOE로 인해 ‘태양광 발전 + 에너지 저장’과 경쟁할 수 없어 여전히 보조적인 역할에 머물고 있습니다. CPV 공급망이 성숙해지고 표준화가 진행됨에 따라, 2축 추적의 정밀도는 필수적인 요소가 되어 향후 확장을 뒷받침하는 기반이 될 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJYAccording to Mordor Intelligence, the Europe solar tracker market size is projected to be USD 4.96 billion in 2025, USD 5.96 billion in 2026, and reach USD 16.08 billion by 2031, growing at a CAGR of 21.95% from 2026 to 2031.
This report is Segmented by Axis Type (Single Axis and Dual Axis), Technology (Photovoltaic, Concentrated Solar Power, and Concentrated Photovoltaic), Drive Type (Electric Motor, Linear Actuator, and Hydraulic), Application (Utility-Scale, Commercial and Industrial, Residential and Micro-Grid, and Agrivoltaic/Agri-solar), and Geography (United Kingdom, Germany, France, Italy, Spain, Netherlands, and More)
Europe Solar Tracker Market Trends and Insights
Abundant Solar Irradiation Across Southern Europe
Annual irradiation above 1,800 kWh/m2 in Andalusia and Sicily lifts tracker energy yield 15-20% versus fixed-tilt and compresses payback to under two years. Spain added 9.4 GW of new solar capacity in 2024, spearheaded by the 590 MW Francisco Pizarro plant that employs single-axis trackers to harvest peak summer output. Italy's 5.3 GW of 2024 additions included multiple bifacial-with-tracker projects that maximize rear-side gain on light-colored soils. Greece is following suit: in June 2025, Nextracker won a 550 MW order for the Oricheio PPC Ptolemaida redevelopment, underscoring how trackers unlock value on reclaimed coal land. Northern Europe's lower irradiation and heavier snow loads moderate this driver's influence, but Southern Europe's isolation edge remains a long-term growth pillar.
EU Green Deal & REPowerEU Solar Targets
REPowerEU raises the bloc's cumulative solar objective to 700 GW by 2030, translating into an annual build-rate near 60 GW, double the 2023 pace. Permitting reforms in Germany trimmed approval cycles for >1 MW ground-mount arrays to nine months, unlocking sizable tracker-ready parcels. Spain cleared 3.8 GW of capacity in its June 2024 auction with winning bids averaging EUR 0.029/kWh, reinforcing trackers as the default choice to honor low-priced PPAs. France's CRE-7 tender allocated 3.7 GW but still battles local opposition, illustrating divergent national execution speeds. Fast-track "renewable acceleration areas" mandated by the revised Renewable Energy Directive are expected to release fresh land banks by 2027, sustaining demand for tracker systems that can maximize energy density.
High Upfront CAPEX vs. Fixed-Tilt
Single-axis trackers carry a 15-25% premium (USD 0.08-0.12/WDC) over fixed-tilt, extending payback by up to a year in lower-irradiation or higher-interest-rate markets. Polish and Romanian developers keep tracker penetration below 30% as they seek to minimize debt service costs. Germany's rooftop-heavy market likewise favors simpler fixed systems. A monetary-policy pivot by the European Central Bank would soften this drag by lowering discount rates, but near-term headwinds persist.
Other drivers and restraints analyzed in the detailed report include:
- Declining Tracker Hardware Costs & Improved Reliability
- Terrain-Following Trackers for Agrivoltaics/Brownfields
- Wind & Snow-Load Engineering in Northern Europe
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dual-axis installations captured 42.5% of incremental revenue in 2025 and are poised to rise at a 23.0% CAGR, outpacing the overall European solar tracker market by roughly 1 percentage point. Single-axis systems nonetheless dominate headline volumes because they cost 15-20% less and offer simpler maintenance protocols. Spain deployed single-axis trackers on roughly 70% of its 9.4 GW 2024 build, leveraging flat terrain and high irradiation. Italy's agrivoltaic subsidies tilt the scales toward dual-axis, which can orient away from crops during sensitive growth stages.
Economies of scale still favor single-axis giants; Nextracker shipped 33.6 GW globally in fiscal 2025, while no dual-axis supplier breached 1 GW. Even so, terrain-adaptive hybrids are blurring classification: Greece's 550 MW Ptolemaida rehabilitation relies on articulated single-axis rows that contour subsidence zones, capturing many benefits of dual-axis without incurring full incremental cost. In lower-irradiation geographies such as Northern Germany, developers continue to prioritize fixed-tilt or basic single-axis to protect return profiles.
Standard PV dominated with 87.1% share in 2025, yet CPV is projected to post a 27.1% CAGR through 2031 by monetizing Southern Europe's >2,000 kWh/m2 DNI corridors. CPV's 30-35% module efficiency offsets its 40-50% CAPEX premium only in Spain, Greece, and parts of Italy. Iberdrola's Francisco Pizarro plant illustrates how bifacial PV trackers capture 8-10% rear-side gain, crowding out CPV in many bids.
The European solar tracker market size for CPV remains below USD 0.5 billion, but early-stage pilots by research institutes and EPCs signal a niche future for ultra-high-efficiency arrays where land is scarce. CSP trackers, in contrast, remain sidelined because their USD 0.10-0.15/kWh LCOE cannot match PV-plus-storage. As CPV supply chains mature and standardization improves, dual-axis tracking precision will be indispensable, anchoring their future expansion.
Complete Report Scope:
- By Axis Type
- Single Axis
- Dual Axis
- By Technology
- Photovoltaic (PV)
- Concentrated Solar Power (CSP)
- Concentrated Photovoltaic (CPV)
- By Drive Type
- Electric Motor
- Linear Actuator
- Hydraulic
- By Application
- Utility-Scale
- Commercial and Industrial (CandI)
- Residential and Micro-grid
- Agrivoltaics/Agri-solar
- By Geography
- United Kingdom
- Germany
- France
- Italy
- Spain
- NORDIC Countries
- Netherlands
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- Nextracker Inc.
- Array Technologies Inc.
- Soltec Power Holdings SA
- PV Hardware (PVH)
- Arctech Solar Holding Co. Ltd.
- Ideematec Deutschland GmbH
- Convert Italia SpA
- Solar FlexRack
- Valmont Solar
- TrinaTracker (Trina Solar)
- Axial Structural Solutions
- Gonvarri Solar Steel
- FTC Solar Inc.
- GameChange Solar
- Optimum Tracker
- Mecasolar
- DEGERenergie GmbH
- SunPower Corporation
- Sun Action Trackers
- Antaisolar
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Abundant solar irradiation across Southern Europe
- 4.2.2 EU Green Deal & REPowerEU solar targets
- 4.2.3 Declining tracker hardware costs & improved reliability
- 4.2.4 Terrain-following trackers for agrivoltaics/brownfields
- 4.2.5 AI-enabled predictive maintenance lowering LCOE
- 4.2.6 EU Net-Zero Industry Act incentives for local production
- 4.3 Market Restraints
- 4.3.1 High upfront CAPEX vs. fixed-tilt
- 4.3.2 Wind & snow-load engineering in Northern Europe
- 4.3.3 Steel-price volatility inflating BoM costs
- 4.3.4 Grid-curtailment risk reducing yield economics
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Axis Type
- 5.1.1 Single Axis
- 5.1.2 Dual Axis
- 5.2 By Technology
- 5.2.1 Photovoltaic (PV)
- 5.2.2 Concentrated Solar Power (CSP)
- 5.2.3 Concentrated Photovoltaic (CPV)
- 5.3 By Drive Type
- 5.3.1 Electric Motor
- 5.3.2 Linear Actuator
- 5.3.3 Hydraulic
- 5.4 By Application
- 5.4.1 Utility-Scale
- 5.4.2 Commercial and Industrial (CandI)
- 5.4.3 Residential and Micro-grid
- 5.4.4 Agrivoltaics/Agri-solar
- 5.5 By Geography
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 NORDIC Countries
- 5.5.7 Netherlands
- 5.5.8 Russia
- 5.5.9 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Products & Services, Recent Developments)
- 6.4.1 Nextracker Inc.
- 6.4.2 Array Technologies Inc.
- 6.4.3 Soltec Power Holdings SA
- 6.4.4 PV Hardware (PVH)
- 6.4.5 Arctech Solar Holding Co. Ltd.
- 6.4.6 Ideematec Deutschland GmbH
- 6.4.7 Convert Italia SpA
- 6.4.8 Solar FlexRack
- 6.4.9 Valmont Solar
- 6.4.10 TrinaTracker (Trina Solar)
- 6.4.11 Axial Structural Solutions
- 6.4.12 Gonvarri Solar Steel
- 6.4.13 FTC Solar Inc.
- 6.4.14 GameChange Solar
- 6.4.15 Optimum Tracker
- 6.4.16 Mecasolar
- 6.4.17 DEGERenergie GmbH
- 6.4.18 SunPower Corporation
- 6.4.19 Sun Action Trackers
- 6.4.20 Antaisolar
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment
- 7.2 Emerging Agrivoltaic Tracker Solutions
- 7.3 Repowering & Retrofitting Fixed-Tilt Plants
- 7.4 Hybrid PV+Storage Tracker Synergies