|
시장보고서
상품코드
2124022
ASEAN의 건설장비 렌탈 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)ASEAN Construction Equipment Rental - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
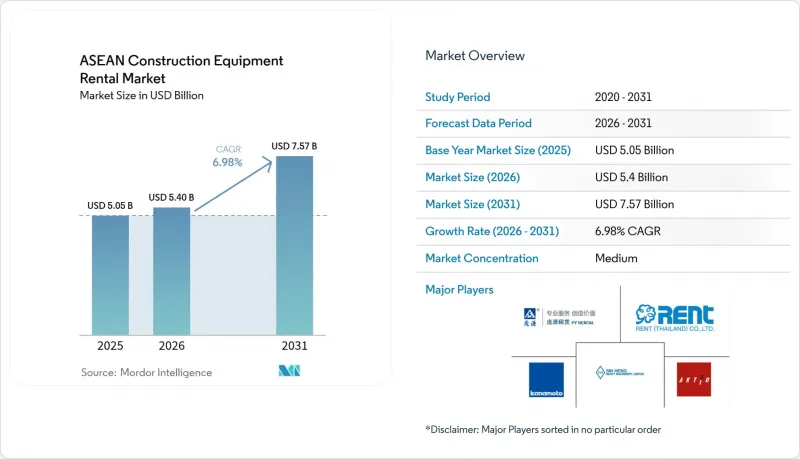
에 의하면, ASEAN 건설장비 렌탈 시장 규모는 2025년에 50억 5,000만 달러로 평가되었고 2026년 54억 달러에서 2031년까지 75억 7,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.98%를 나타낼 전망입니다.
본 보고서는 차량 유형(토공 기계 등), 구동 방식(내연 기관, 하이브리드 구동, 전기 구동), 최종 사용자 산업(인프라, 상업용 부동산 등), 렌탈 기간(단기 및 장기), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
아세안 건설장비 렌탈 시장 동향 및 인사이트
인프라 주도형 경기 부양책
아세안 건설장비 렌탈 시장에서 꾸준한 공공 지출은 교통, 에너지, 도시 개발 프로젝트의 안정적인 수주 잔고를 뒷받침하고 있습니다. 인도네시아의 PSN(국가전략계획)은 대규모 토목 기계 도입에 크게 의존하는 도로, 항만, 수자원 프로젝트에 초점을 맞추고 있으며, 주요 사업에 막대한 예산을 배정하고 있습니다. 베트남은 올해 공공 투자 예산의 상당 부분을 이미 지출했으며, 이러한 적극적인 노력이 장기 렌탈 계약을 뒷받침하고 있습니다. 한편, 태국은 향후 몇 년간 교통망 정비에 막대한 자금을 할당하고 있어, 이로 인해 콘크리트 포장기 및 다짐 장비에 대한 수요가 증가하고 있습니다. OECD는 인도네시아가 향후 10년 이내에 기후 변화에 강한 인프라에 막대한 투자가 필요할 것으로 예측했습니다. 이 예측은 특히 배수 및 홍수 대책 분야에서 렌탈 차량 군에 대한 특수 기계 수요가 증가하고 있음을 보여 주며, 그 시급성을 부각시키고 있습니다. 이러한 추세를 더욱 가속화하듯, 아시아개발은행(ADB)은 향후 10년이 끝날 때까지 아시아 전역에 걸쳐 큰 인프라 격차가 존재할 것이라고 지적하고 있으며, 이는 다양한 렌탈 포트폴리오에 대한 견고하고 다년간 지속될 수요를 시사합니다.
산업단지 및 물류 허브의 확대
최근 몇 년간 베트남은 막대한 외국인 직접 투자를 유치하며 박닌성에서 대규모 물류 거점 개발에 착수했습니다. 아세안(ASEAN)이 향후 몇 년간 산업용 부지 확장을 계획하고 있는 만큼, 말뚝 박기 기계, 텔레핸들러, 임시 발전기 등의 장비에 대한 안정적인 수요가 확보될 전망입니다. 한편, 말레이시아와 인도네시아는 공급망 다각화를 목표로 하는 전자기기 조립 제조업체들에게 주목받는 지역으로 부상하고 있으며, 유연한 렌탈 계약에 기반한 다단계 설비 확충이 진행되고 있습니다. 아세안 건설장비 렌탈 시장에서는 니어쇼어링과 전자상거래(EC)에 힘입은 창고·공장 건설을 배경으로, 정밀 리프팅 장비, 클린룸 대응 장비, 소형 토공 기계에 대한 수요가 급증하고 있습니다.
프로젝트 주기의 단축이 가동률 변동을 초래
아세안(ASEAN) 건설장비 렌탈 시장에서는 건설 공기가 단축되는 반면, 유휴 시간이 급증하여 이익률을 압박하고 있습니다. 이는 승인 절차의 단절적인 진행, 계절적인 몬순, 그리고 자금 조달 지연이 복합적으로 작용하기 때문입니다. 태국에서는 예산 승인이 회계 분기 후반으로 미뤄지는 경우가 빈번합니다. 그 결과, 장비 동원이 동시에 다발적으로 발생하여 렌탈 공급에 부담이 가중되고 있습니다. 최근 한 대형 건설사가 상당한 이익을 보고했으나, 프로젝트 착수 지연으로 인해 매출 목표를 달성하지 못하면서 이러한 변동성이 장비 계획에 미치는 영향이 부각되었습니다. 이러한 과제를 해결하기 위해 렌탈 업체는 유휴 재고를 많이 보유하거나, 수요가 적은 시기에 할증 요금을 부과하는 것 중 하나를 선택할 수밖에 없으며, 결과적으로 프로젝트 비용을 상승시키게 됩니다.
부문별 분석
인도네시아의 토지 개발 추진과 말레이시아의 산업단지 조성으로 인해, 2025년에는 토공 기계가 아세안 건설장비 렌탈 시장의 46.05%를 차지했습니다. 태국의 설비 투자 확대에 따라 포장 및 노면 공사가 가속화되고 있어, 콘크리트 및 도로 건설장비는 2031년까지 연평균 성장률(CAGR) 7.09%를 기록할 전망입니다. 싱가포르의 좁은 현장에서는 스키드 스티어 로더와 콤팩트 트랙 로더가 인기를 끌고 있는 반면, 베트남 전역의 고속도로 노반 공사에서는 진동 롤러가 여전히 필수적인 존재로 자리 잡고 있습니다.
싱가포르의 현장용 충전기와 태국의 배터리 교환 스테이션 시범 운영에 힘입어, 콘크리트 믹서와 소형 로더에는 전기 및 하이브리드 파워트레인이 도입되기 시작했습니다. 2024년에는 코마츠의 유닛 출하 대수는 감소했으나, 부품 매출액은 증가하여 애프터마켓의 렌탈 수요를 뒷받침하는 높은 차량 가동률을 보여주고 있습니다. 베트남에서는 고정밀 리프트 크레인이 다층 물류 시설 건설을 뒷받침하고 있으며, 인도네시아의 홍수 대책 프로젝트에서는 특수 준설용 굴삭기에 대한 수요가 증가하고 있습니다.
2025년, 아세안 건설장비 렌탈 시장에서 내연기관 시스템은 72.40%의 점유율을 유지했습니다. 이는 외딴 지역이나 중량 작업에서 디젤 동력이 여전히 타의 추종을 불허하는 성능을 발휘하기 때문입니다. 그러나 전기식 기종은 싱가포르의 저배출 가스 현장 의무화 및 태국의 배터리식 콘크리트 트럭 실증 실험에 힘입어 2031년까지 연평균 성장률(CAGR) 7.04%를 나타낼 것으로 예측됩니다. 하이브리드 구동 시스템은 장시간 가동은 필수적이면서도 연료비 절감을 중시하는 교량 공사 등의 용도에 활용되고 있습니다.
배터리 밀도의 향상과 집중 충전 거점의 확충으로 인해 렌탈 업체들은 전기식 차량을 효율적으로 운용할 수 있게 되었습니다. H&E;Equipment Services사의 보고에 따르면, 가동 중인 렌탈 차량의 3분의 1이 전기식이며, 운영 비용 절감 효과가 입증되었습니다. 전력망이 제대로 구축되지 않은 인도네시아의 광산 프로젝트에서는 여전히 디젤 엔진이 주류를 이루고 있지만, 배터리의 가격 경쟁력이 향상됨에 따라 가솔린 엔진은 소형 공구 분야로 한정될 전망입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the ASEAN construction equipment rental market size was valued at USD 5.05 billion in 2025 and estimated to grow from USD 5.4 billion in 2026 to reach USD 7.57 billion by 2031, at a CAGR of 6.98% during the forecast period (2026-2031).
This report is Segmented by Vehicle Type (Earthmoving Equipment and More), Propulsion (IC Engine, Hybrid Drive, and Electric Drive), End-User Industry (Infrastructure, Commercial Real-Estate, and More), Rental Duration (Short-Term and Long-Term), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
ASEAN Construction Equipment Rental Market Trends and Insights
Infrastructure-Led Stimulus Programs
Consistent public spending in the ASEAN construction equipment rental market fuels steady work backlogs in transport, energy, and urban projects. Indonesia's PSN has allocated a significant budget for key initiatives, focusing on roads, ports, and water projects that heavily rely on expansive earthmoving fleets. Vietnam's proactive approach is evident as it has already disbursed a substantial portion of its public-investment budget for the year, a move that bolsters longer rental contracts. Meanwhile, Thailand has earmarked considerable funds for transport links over the next few years, driving up the demand for concrete pavers and compaction equipment. The OECD projects that Indonesia will require a massive investment in climate-resilient infrastructure within the next decade. This forecast highlights the urgency and signals a growing need for specialty machinery, particularly in drainage and flood protection, within rental fleets. Adding to the momentum, the Asian Development Bank points to a significant infrastructure gap across Asia through the decade's end, suggesting a robust, multi-year demand for diversified rental portfolios .
Expansion of Industrial Parks & Logistics Hubs
In recent times, Vietnam has attracted substantial foreign direct investment and initiated the development of a significant logistics space in Bac Ninh. As ASEAN plans to expand its industrial land over the next few years, this ensures a consistent demand for equipment like piling rigs, telehandlers, and temporary power units. Meanwhile, Malaysia and Indonesia are becoming hotspots for electronics assemblers aiming for diversified supply chains, leading to multistage buildouts reliant on adaptable rental agreements. The ASEAN construction equipment rental market is witnessing a surge in demand for precision lifting tools, clean-room compatible gear, and compact earthmovers, fueled by nearshoring and e-commerce-driven warehouse and factory constructions.
Short Project Cycles Causing Utilization Volatility
In the ASEAN construction equipment rental market, construction timelines are compressed, and idle-time spikes emerge, eroding margins. This is due to a combination of stop-start approvals, seasonal monsoons, and financing delays. In Thailand, budget approvals frequently push into the latter part of fiscal quarters. This results in simultaneous mobilizations, putting a strain on rental supply. Recently, a major construction company reported significant profits but fell short of its revenue targets due to delayed project starts, underscoring the volatility's impact on equipment planning. To navigate these challenges, rental companies either maintain larger idle inventories or impose higher premiums during slack periods, ultimately inflating project costs.
Other drivers and restraints analyzed in the detailed report include:
- Growing Contractor Preference for OPEX over CAPEX
- Digital Fleet-Management & Telematics Integration
- Persistently High Import Tariffs on Used Machinery
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Due to Indonesia's land-development drives and Malaysia's industrial-park grading, earthmoving equipment captured 46.05% of the ASEAN construction equipment rental market in 2025. Concrete and road machinery should post a 7.09% CAGR through 2031 as Thailand's capex push accelerates paving and surface works. Skid-steer and compact track loaders gain favor in Singapore's cramped sites, while vibratory rollers stay essential for expressway sub-grades across Vietnam.
Electric and hybrid powertrains emerge in concrete mixers and small loaders, supported by Singapore's job-site chargers and Thailand's pilot battery-swap depots. Komatsu unit deliveries fell in 2024, yet parts revenue climbed, showing high fleet utilization that sustains aftermarket rentals. Precision lifting cranes support Vietnam's multi-story logistics builds, and demand for specialty dredging excavators rises for Indonesia's flood-control projects.
Internal combustion systems retained a 72.40% share of the ASEAN construction equipment rental market in 2025, as diesel power remains unrivaled for remote or heavy-duty. Electric units, however, are forecast to grow 7.04% CAGR through 2031, led by Singapore mandates for low-emission sites and Thai pilots of battery concrete trucks. Hybrid drives serve bridge applications where long runtimes are essential, yet fuel savings are prized.
Battery density improvements and clustered charging depots allow rental firms to rotate electric fleets efficiently. H&E Equipment Services reports one-third of its active rental units are electric, validating operating-cost savings. Diesel engines stay prevalent in Indonesian mining projects lacking grid power, while gasoline engines shrink to small tools as battery parity approaches.
Complete Report Scope:
- By Vehicle Type
- Earthmoving Equipment
- Excavators
- Loaders
- Bulldozers
- Skid-steer & Compact Track Loaders
- Material Handling Equipment
- Cranes (Crawler, Mobile, Tower)
- Forklifts & Telehandlers
- Concrete & Road Construction Machinery
- Compaction Equipment
- Earthmoving Equipment
- By Propulsion
- IC Engine
- Diesel
- Gasoline
- Hybrid Drive
- Electric Drive
- IC Engine
- By End-User Industry
- Infrastructure
- Commercial Real-Estate
- Industrial & Logistics
- Mining & Quarrying
- Oil & Gas
- Other Specialised Sectors
- By Rental Duration
- Short-term
- Long-term
- By Country
- Indonesia
- Thailand
- Vietnam
- Singapore
- Malaysia
- Philippines
- Cambodia
- Laos
- Myanmar
- Brunei
List of Companies Covered in this Report:
- Kanamoto Co. Ltd
- Aktio Corp.
- Sin Heng Heavy Machinery Ltd
- Nishio Rent All Co. Ltd
- Tat Hong Holdings Ltd
- Guzent Inc.
- Superkrane Mitra Utama
- Rent (Thailand) Co. Ltd
- Asia Machinery Solutions Vietnam Co. Ltd
- Shanghai Pangyuan Machinery Rental Co. Ltd
- United Tractors Tbk
- Hexindo Adiperkasa Tbk
- Multicrane Perkasa
- UMW Equipment Division
- Coates Hire Indonesia
- Multicore Machinery (Philippines)
- Nikken Corporation
- Caterpillar Rental Services (SEA)
- Komatsu Rental Asia
- Zoomlion Leasing (SEA)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infrastructure-Led Stimulus Programmes
- 4.2.2 Expansion of Industrial Parks & Logistics Hubs
- 4.2.3 Growing Contractor Preference for OPEX Over CAPEX
- 4.2.4 Digital Fleet-Management & Telematics Integration
- 4.2.5 Early-Stage Electrified Equipment Pilots in Singapore & Thailand
- 4.2.6 ESG-Linked Green-Financing Incentives for Rental Fleets
- 4.3 Market Restraints
- 4.3.1 Short Project Cycles Causing Utilization Volatility
- 4.3.2 Persistently High Import Tariffs on Used Machinery
- 4.3.3 Fragmented Equipment-Maintenance Ecosystem
- 4.3.4 Slow Homologation of Battery-Electric Heavy Machines
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Vehicle Type
- 5.1.1 Earthmoving Equipment
- 5.1.1.1 Excavators
- 5.1.1.2 Loaders
- 5.1.1.3 Bulldozers
- 5.1.1.4 Skid-steer & Compact Track Loaders
- 5.1.2 Material Handling Equipment
- 5.1.2.1 Cranes (Crawler, Mobile, Tower)
- 5.1.2.2 Forklifts & Telehandlers
- 5.1.3 Concrete & Road Construction Machinery
- 5.1.4 Compaction Equipment
- 5.1.1 Earthmoving Equipment
- 5.2 By Propulsion
- 5.2.1 IC Engine
- 5.2.1.1 Diesel
- 5.2.1.2 Gasoline
- 5.2.2 Hybrid Drive
- 5.2.3 Electric Drive
- 5.2.1 IC Engine
- 5.3 By End-User Industry
- 5.3.1 Infrastructure
- 5.3.2 Commercial Real-Estate
- 5.3.3 Industrial & Logistics
- 5.3.4 Mining & Quarrying
- 5.3.5 Oil & Gas
- 5.3.6 Other Specialised Sectors
- 5.4 By Rental Duration
- 5.4.1 Short-term
- 5.4.2 Long-term
- 5.5 By Country
- 5.5.1 Indonesia
- 5.5.2 Thailand
- 5.5.3 Vietnam
- 5.5.4 Singapore
- 5.5.5 Malaysia
- 5.5.6 Philippines
- 5.5.7 Cambodia
- 5.5.8 Laos
- 5.5.9 Myanmar
- 5.5.10 Brunei
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Kanamoto Co. Ltd
- 6.4.2 Aktio Corp.
- 6.4.3 Sin Heng Heavy Machinery Ltd
- 6.4.4 Nishio Rent All Co. Ltd
- 6.4.5 Tat Hong Holdings Ltd
- 6.4.6 Guzent Inc.
- 6.4.7 Superkrane Mitra Utama
- 6.4.8 Rent (Thailand) Co. Ltd
- 6.4.9 Asia Machinery Solutions Vietnam Co. Ltd
- 6.4.10 Shanghai Pangyuan Machinery Rental Co. Ltd
- 6.4.11 United Tractors Tbk
- 6.4.12 Hexindo Adiperkasa Tbk
- 6.4.13 Multicrane Perkasa
- 6.4.14 UMW Equipment Division
- 6.4.15 Coates Hire Indonesia
- 6.4.16 Multicore Machinery (Philippines)
- 6.4.17 Nikken Corporation
- 6.4.18 Caterpillar Rental Services (SEA)
- 6.4.19 Komatsu Rental Asia
- 6.4.20 Zoomlion Leasing (SEA)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment