|
시장보고서
상품코드
2124031
건축용 단열재 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Building Insulation Materials - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 건축용 단열재 시장 규모는 2025년 325억 1,000만 달러로 평가되었고, 2026년에는 337억 9,000만 달러로 추정되고, 2031년까지 409억 9,000만 달러에 이를 것으로 예상되며, 2026-2031년 CAGR 3.94%로 성장할 전망입니다.
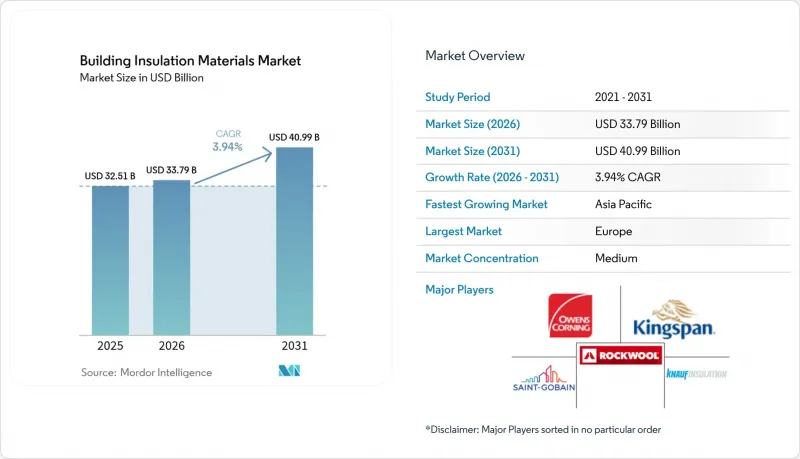
본 보고서는 소재 유형별(유리섬유, 미네랄 울, 셀룰로오스 등), 용도별(지붕, 벽, 바닥, 지하실 등), 최종 사용자별(주거용, 비주거용), 시공 형태별(신축, 개보수), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 건축용 단열재 시장 동향 및 인사이트
에너지 절약 건물에 대한 수요 증가
2024년에는 건축물이 전 세계 최종 에너지 소비량의 30%를 차지한 가운데, 47개국이 건축 외피 기준을 강화했습니다. 캘리포니아주의 ‘타이틀 24-2025’에서는 다락방 단열 성능의 최저 기준이 R-49로 상향 조정되어, 저가형 유리섬유 대신 분사식 셀룰로오스 단열재가 채택되게 되었습니다. EU의 ‘에너지 성능에 관한 건축물 지침(EPBD)’ 개정에 따라, 회원국은 매년 공공 건축물 연면적의 3%를 개보수해야 할 의무가 부과되었으며, 2030년까지 약 2억 4,000만 m²의 파사드 단열이 추가될 전망입니다. 일본에서는 현재 300m²를 초과하는 비주거용 건축물에 대해 제3자 인증이 의무화되어 있으며, 이에 따라 열교를 제거하는 연속 단열 시스템의 보급이 가속화되고 있습니다. 이러한 규제에 따라 높은 R값을 가진 제품은 단순한 프리미엄 추가 옵션이 아닌 표준 사양으로 자리 잡아가고 있습니다.
북미의 친환경 리모델링 인센티브 확대
미국의 ‘인플레이션 억제법’에서는 단열재에 대해 연간 최대 1,200달러의 30%에 해당하는 세액 공제를 제공하고 있으며, 한편 ‘179D 공제’에서는 철저한 에너지 절약 개보수에 대해 1제곱피트당 5달러가 지급됩니다. 캐나다의 ‘그리너 홈즈 그랜트(Greener Homes Grant)’는 2024-2025년 주택 소유자 1인당 3,700달러 상당의 보조금을 제공하여, 열 손실이 35%를 초과하는 다락방 및 지하실 개보수 공사를 촉진했습니다. 퍼시픽 가스 앤 일렉트릭(PG&E)이 제공하는 벽체 빈 공간 단열에 대한 1제곱피트당 0.15달러의 인센티브 등 유틸리티체의 리베이트 덕분에 투자 회수 기간은 5년 미만으로 단축됩니다. 이러한 재정적 조치로 인해 단열 공사는 장기적인 투자 회수가 필요한 구매에서 단기적으로 현금 흐름이 플러스가 되는 개보수로 전환되었으며, 신축 주기에 앞서 개보수 수요를 끌어올리고 있습니다.
자재 및 시공 비용의 급등
미국에서 스프레이식 폴리우레탄 폼의 시공 단가는 보드피트당 평균 1.50-2달러로, 유리섬유·배트의 2배 가격이지만, R값은 고작 30-40% 더 높을 뿐입니다. 시공 업체 부족으로 인해 2025년 북미에서는 단열 기술자가 1만 5,000명 부족해졌으며, 납기 기간은 12주까지 늘어났습니다. 유럽의 에너지 가격 급등으로 인해 유리섬유 로빙 가격은 9% 상승했으며, 스티렌 가격 변동으로 인해 발포재 비용은 1입방미터당 80달러 증가했습니다. 이러한 경제적 요인으로 인해 시장은 에어로겔을 채택하는 프리미엄 프로젝트와 리모델링을 미루는 밸류 부문으로 양분되고 있습니다.
부문 분석
2025년, 유리섬유는 건축용 단열재 시장에서 34.65%의 점유율을 차지했습니다. 이는 설치 비용이 저렴하고 시공 업체들이 익숙하다는 점이 반영된 결과입니다. 폴리스티렌계 소재는 열교를 차단하는 경질 보드를 권장하는 연속 단열 기준에 따라 2031년까지 연평균 성장률(CAGR) 4.18%를 나타낼 것으로 예측됩니다. 또한, 유럽의 고층 빌딩 개보수 공사에서는 화염 전파에 관한 규제가 강화됨에 따라 미네랄 울의 사용량이 11% 증가했습니다. 폴리우레탄 및 폴리이소시아누레이트 폼은 HFO 발포제로의 전환이 진행되고 있는 반면, 에어로겔과 진공 패널은 공간 제약이 있는 리모델링 공사에서 틈새 시장 점유율을 차지하고 있습니다.
고급 에어로겔 솔루션을 위한 건축용 단열재 시장에서는 40-50%의 가격 프리미엄이 붙고 있습니다. 시공업체들은 건축 기준의 최소 요건을 충족하는 주택용 벽에는 유리섬유를 표준으로 사용하고, R-30 이상의 상업용 외벽에는 폴리스티렌을, 친환경 인증 프로젝트에는 바이오 발포재를 채택하고 있습니다. 미네랄 울은 불연성이기 때문에 고가의 팽창성 방화 도료 시공이 필요 없으며, 방화 시험이 엄격한 현장에서 비용 면에서 우위를 점하고 있습니다.
지붕 구조는 2025년 수요의 29.19%를 차지했습니다. 한편, 오픈 플랜으로의 개조 시 더 뛰어난 방음 성능이 요구되고, ASHRAE 90.1-2022에 따른 덕트 누출 제한이 강화됨에 따라, 방음 파티션 및 HVAC 덕트용 건축 단열재는 연평균 성장률(CAGR) 4.85%로 확대될 것으로 예측됩니다. 벽 단열재의 용도는 주로 EU 지역의 파사드 개보수에 의해 주도되고 있으며, 이 부문이 큰 점유율을 차지하고 있습니다. 바닥 및 지하실용 제품은 동결 방지 기초에 슬래브 하부 발포재가 필요한 지역에서 완만한 성장이 예상됩니다.
천장 및 다락방 용도의 경우, 인건비를 30% 절감할 수 있는 분사식 셀룰로오스 단열재가 선호되고 있습니다. LEED의 새로운 ‘음향 성능’ 크레딧에 따라 상업 건축업자들은 미네랄 울 배트 및 타일의 채택을 가속화하고 있습니다. 데이터센터가 팬의 에너지 소비를 줄이기 위해 R-6 덕트 재킷을 지정하고 있으며, 쿨 루프 구조가 경사가 가파른 주택에서 폴리이소(polyiso)의 채택을 촉진하고 있는 만큼, HVAC용 단열재 시장 규모는 2031년까지 50억 달러에 달할 전망입니다.
지역별 분석
EPBD(유럽 에너지 효율 지침) 개정으로 인해 모든 회원국이 2030년까지 탄소 중립 건물을 목표로 하도록 유도됨에 따라, 2025년 매출의 36.91%를 유럽이 차지했습니다. 독일에서는 BEG(기후행동법)에 따라 2024년에 42만 건의 개보수 공사가 실시되었습니다. 또한 프랑스에서는 2025년부터 F 및 G 등급 임대 주택에 대한 임대 금지 조치가 도입되어 480만 가구가 영향을 받게 됩니다. 스웨덴에서는 현재 U값을 0.15 W/m²K 미만으로 유지해야 하는 것이 의무화되어 있으며, 이는 두꺼운 미네랄 울 또는 진공 패널을 사용할 경우에만 달성할 수 있습니다.
아시아태평양은 2025년까지 도시 지역 건축물의 75%가 친환경 기준을 충족하겠다는 중국의 계획에 힘입어 연평균 성장률(CAGR) 4.89%로 가장 빠르게 성장하고 있는 지역입니다. 인도의 2024년 건축 기준법 개정안에서는 100 m2 이상의 상업용 건물을 대상으로 외벽의 U값을 0.40 W/m2K로 상향 조정했습니다. 일본에서는 2025년 이후 신축 비주거용 건축물에 대해 기준 에너지 사용량보다 20% 낮은 수준을 의무화하고 있습니다. 아세안(ASEAN) 신흥 시장에서는 고급 프로젝트에 EDGE나 Green Mark가 채택되고 있지만, 주택 분야로의 보급률은 여전히 15% 미만에 머물러 있습니다.
북미는 큰 시장 점유율을 차지하고 있으며, 주택 담보 대출 금리 상승으로 주택 착공 건수가 둔화되고 있어 그 성장은 신축 주택이 아닌 세제 혜택에 따른 개보수에 의해 지탱되고 있습니다. 캐나다에서는 1980년 이전에 건설된 950만 가구의 주택을 대상으로 최대 2만 9,600달러의 무이자 대출이 제공됩니다. 멕시코에서는 개정된 NOM-020-ENER에 따라 공조 구역 내 건축 외피의 단열 성능이 의무화되었습니다. 남미 및 중동 및 아프리카(MEA) 지역의 합산 점유율은 10% 미만이지만, 때때로 급증하는 추세를 보입니다. 사우디아라비아의 건축 기준에 따르면, 현재 모든 정부 프로젝트에서 R-13 등급의 벽체 사용이 의무화되어 있으며, 그 중 60%를 수입에 의존하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the building insulation materials market size is expected to increase from USD 32.51 billion in 2025 to USD 33.79 billion in 2026 and reach USD 40.99 billion by 2031, growing at a CAGR of 3.94% over 2026-2031.
This report is Segmented by Material Type (Fiberglass, Mineral Wool, Cellulose, and More), Application (Roof, Wall, Floor and Basement, and More), End-User (Residential, Non-Residential), Installation (New Construction, Renovation), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Building Insulation Materials Market Trends and Insights
Growing Demand for Energy-Efficient Buildings
Forty-seven countries strengthened envelope standards in 2024 as buildings consumed 30% of global final energy. California's Title 24-2025 increased attic minimums to R-49, displacing lower-value fiberglass in favor of blown-in cellulose. The EU EPBD recast obliges member states to upgrade 3% of public floor area each year, adding roughly 240 million m2 of facade insulation by 2030. Japan now requires third-party certification for non-residential structures above 300 m2, which is accelerating continuous-insulation systems that eliminate thermal bridges. These rules collectively position high-R-value products as default specifications rather than premium add-ons.
Increasing Green Retrofitting Incentives in North America
The U.S. Inflation Reduction Act offers a 30% tax credit on insulation materials up to USD 1,200 annually, while the 179D deduction pays USD 5 per square foot for deep-energy retrofits. Canada's Greener Homes Grant provided USD 3,700 equivalent per homeowner in 2024-2025 and drove attic and basement projects where heat loss surpasses 35%. Utility rebates such as Pacific Gas & Electric's USD 0.15 per square foot wall-cavity incentive shorten payback periods to under five years. These fiscal levers have shifted insulation from a long-term payback purchase to near-term cash-flow positive upgrades, lifting renovation demand ahead of the new-build cycle.
High Materials and Installation Cost
Spray polyurethane foam averages USD 1.50-2.00 per board foot installed in the United States, double fiberglass batts, while delivering only 30-40% higher R-value. Contractor shortages left North America 15,000 insulators short in 2025, pushing lead times to 12 weeks. Glass-fiber rovings rose 9% on Europe's energy spike, and styrene volatility added USD 80 per cubic meter to foam costs. These economics split the market into premium projects that adopt aerogels and value segments that postpone upgrades.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Government Support for Eco-Friendly and Sustainable Materials
- Growing Preference for Low-VOC Bio-based Foams
- Availability of Affordable Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fiberglass held 34.65% of the building insulation materials market share in 2025, reflecting its low installed cost and contractor familiarity. Polystyrene materials are forecast to grow at a 4.18% CAGR through 2031 as continuous-insulation codes favor rigid boards that break thermal bridges. Mineral wool volume climbed 11% in European high-rise retrofits after tighter flame-spread rules. Polyurethane and polyisocyanurate foams are transitioning to HFO blowing agents, while aerogels and vacuum panels take niche share in space-constrained retrofits.
The building insulation materials market size for premium aerogel solutions commands 40-50% price premiums. Contractors default to fiberglass in code-minimum residential walls, reserve polystyrene for R-30+ commercial envelopes, and adopt bio-based foams for green-certified projects. Mineral wool's non-combustibility exempts it from costly intumescent coatings, giving it an embedded cost edge where fire testing is strict.
Roof assemblies captured 29.19% of the 2025 demand. However, acoustic partitions and HVAC duct wraps are projected to expand at a 4.85% CAGR as open-plan retrofits seek better sound privacy and ASHRAE 90.1-2022 tightens duct leakage limits. Wall insulation applications are mainly driven by EU facade upgrades, which account for a significant share. Floor and basement products grow modestly where frost-protected foundations need under-slab foam.
Ceiling and attic applications favor blown-in cellulose that trims labor costs by 30%. LEED's new Acoustic Performance credit is pivoting commercial builders toward mineral-wool batts and tiles. The building insulation materials market size for HVAC wraps is poised to reach USD 5 billion by 2031 as data centers specify R-6 duct jackets to cut fan energy, while cool-roof assemblies are pulling polyiso into steep-slope housing.
Complete Report Scope:
- By Material Type
- Fiberglass
- Mineral Wool
- Cellulose
- Polyurethane/Polyisocyanurate Foams (PUR/PIR)
- Polystyrene
- Other Materials (Cork, Aerogel and Vacuum Insulation Panels, Spray Foams, Hemp, Calcium-Silicate, etc.)
- By Application
- Roof
- Wall (External and Cavity)
- Floor and Basement
- Ceiling and Attic
- Acoustic Partition and HVAC Duct
- By End-User
- Residential
- Non-Residential
- Commercial
- Infrastructure
- Other Non-Residential Industries (Education, Healthcare, Civic and Religious,etc.)
- By Installation
- New Construction
- Renovation
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordics Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Europe held 36.91% of 2025 revenue as the EPBD recast steers every member state toward zero-emission buildings by 2030. Germany processed 420,000 retrofits in 2024 under BEG, and France's ban on F- and G-rated rentals from 2025 affects 4.8 million dwellings. Sweden now requires U-values below 0.15 W/m2K, achieved only with thick mineral wool or vacuum panels.
Asia-Pacific is the fastest-growing region at 4.89% CAGR, propelled by China's plan for 75% of urban buildings to meet green standards by 2025. India's 2024 code extension covers commercial buildings above 100 m2 and tightens wall U-values to 0.40 W/m2K. Japan requires new non-residential buildings to beat baseline energy use by 20% from 2025. Emerging ASEAN markets adopt EDGE and Green Mark in premium projects, though residential penetration remains below 15%.
North America commands a significant market share, with growth rooted in tax-driven retrofits rather than new homes, as mortgage rates dampen housing starts. Canada's interest-free loans up to USD 29,600 are targeting 9.5 million pre-1980 homes. Mexico's updated NOM-020-ENER introduces mandatory envelope resistance in air-conditioned zones. South America and MEA together contribute under 10% but show episodic surges; Saudi Arabia's code now mandates R-13 walls in all government projects, relying on 60% imports.
- Armacell
- Aspen Aerogels Inc.
- Atlas Roofing Corporation
- BASF SE
- Beijing New Building Materials Public Limited Company
- Cellofoam North America Inc.
- Covestro AG
- Dow
- DuPont
- GAF Materials LLC
- Holcim
- Huntsman International LLC
- Johns Manville
- Kingspan Group
- Knauf Group
- Owens Corning
- Recticel NV/SA
- ROCKWOOL A/S
- Saint-Gobain
- Synthos
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand for Energy Efficient Buildings
- 4.2.2 Increasing Green Retrofitting Incentives in North America
- 4.2.3 Increasing Governemnt Support for the Usage of Eco-Friendly and Sustainable Materials
- 4.2.4 Growing Preference for Low-VOC Bio-based Foams
- 4.2.5 Rising Infrastructure and Industrialization in Asia-Pacific
- 4.3 Market Restraints
- 4.3.1 High Materials and Installation Cost
- 4.3.2 Availability of Affordable Alternatives
- 4.3.3 Regulatory Scrutiny on Global Warming Potential of Blowing Agents
- 4.4 Value Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Material Type
- 5.1.1 Fiberglass
- 5.1.2 Mineral Wool
- 5.1.3 Cellulose
- 5.1.4 Polyurethane/Polyisocyanurate Foams (PUR/PIR)
- 5.1.5 Polystyrene
- 5.1.6 Other Materials (Cork, Aerogel and Vacuum Insulation Panels, Spray Foams, Hemp, Calcium-Silicate, etc.)
- 5.2 By Application
- 5.2.1 Roof
- 5.2.2 Wall (External and Cavity)
- 5.2.3 Floor and Basement
- 5.2.4 Ceiling and Attic
- 5.2.5 Acoustic Partition and HVAC Duct
- 5.3 By End-User
- 5.3.1 Residential
- 5.3.2 Non-Residential
- 5.3.2.1 Commercial
- 5.3.2.2 Infrastructure
- 5.3.2.3 Other Non-Residential Industries (Education, Healthcare, Civic and Religious,etc.)
- 5.4 By Installation
- 5.4.1 New Construction
- 5.4.2 Renovation
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Nordics Countries
- 5.5.3.7 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Armacell
- 6.4.2 Aspen Aerogels Inc.
- 6.4.3 Atlas Roofing Corporation
- 6.4.4 BASF SE
- 6.4.5 Beijing New Building Materials Public Limited Company
- 6.4.6 Cellofoam North America Inc.
- 6.4.7 Covestro AG
- 6.4.8 Dow
- 6.4.9 DuPont
- 6.4.10 GAF Materials LLC
- 6.4.11 Holcim
- 6.4.12 Huntsman International LLC
- 6.4.13 Johns Manville
- 6.4.14 Kingspan Group
- 6.4.15 Knauf Group
- 6.4.16 Owens Corning
- 6.4.17 Recticel NV/SA
- 6.4.18 ROCKWOOL A/S
- 6.4.19 Saint-Gobain
- 6.4.20 Synthos
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment