

|
시장보고서
상품코드
2124039
무선 연결 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Wireless Connectivity - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
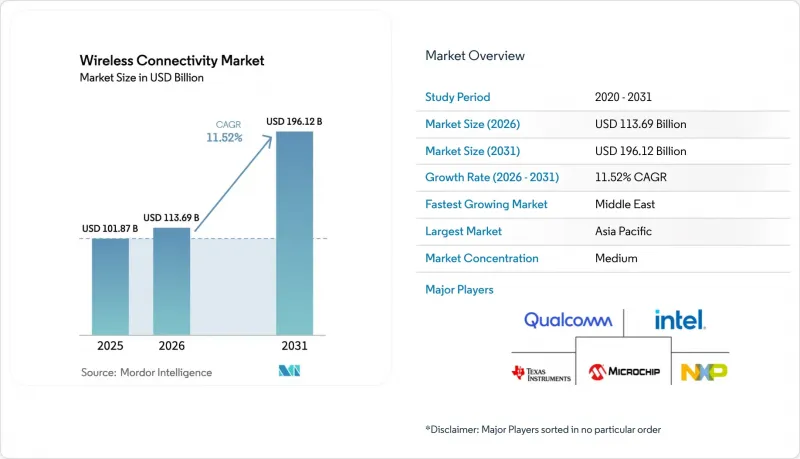
에 의하면, 무선 연결 시장 규모는 2025년에 1,018억 7,000만 달러, 2026년에 1,136억 9,000만 달러가 되어, 2031년까지 1,961억 2,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년까지 CAGR 11.52%로 성장할 전망입니다.
본 보고서는 기술별(Wi-Fi, 블루투스 등), 최종 사용자 산업별(가전, 자동차 등), 주파수 대역별(1GHz 미만, 2.4GHz, 6GHz), 기기 유형별(스마트폰·태블릿,스마트 홈 기기 등), 그리고 지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 달러 기준 금액으로 제시되어 있습니다.
세계 무선 연결 시장 동향 및 인사이트
소비자용 및 산업용 IoT 분야에서 Wi-Fi 6/6E/7 칩셋의 급증
2025년 1분기, 기업용 Wi-Fi 7 액세스 포인트의 출하 대수는 신규 WLAN 장비 전체의 12%에 달했으나, 대부분의 클라이언트 기기가 여전히 320 MHz를 지원하지 않기 때문에 최대 46Gbps의 처리량은 현재로서는 이상적인 수치에 그치고 있습니다. 멀티링크 작동을 통해 공장 센서는 시간 제약이 있는 패킷을 6GHz 대역에서 전송하는 동시에 대용량 데이터를 5GHz 대역에 할당할 수 있어, 혼잡한 공간에서도 지터를 5 ms 미만으로 억제할 수 있습니다. 브로드컴은 2025년에 1,800만 개의 Wi-Fi 7 콤보 칩을 출하했으며, 그 중 절반은 산업용 게이트웨이용이었습니다. 스타형 토폴로지에서 메쉬+게이트웨이형 토폴로지로의 전환에 따라, 기존 PLC 제조업체들은 백플레인 재설계를 강요받고 있으며, 이로 인해 24개월마다의 업데이트 주기가 생겨 2027년까지 칩셋의 두 자릿수 성장이 지속될 것입니다. 펌웨어에 AI 기반 간섭 저감 기능을 통합한 모듈 공급업체는 장기 공급 계약을 확보하고 있어, 노드 부족으로 인한 반도체 가격 변동이 있더라도 이익률을 안정적으로 유지하고 있습니다. 그 결과, 무선 연결 시장에서는 공장 자동화 업그레이드의 상당수가 Wi-Fi 7 도입을 전제조건으로 하고 있습니다.
스마트 계량기 도입을 위한 LPWAN 모듈의 확대
유럽의 유틸리티자들은 규제 당국이 15분 간격의 데이터 수집을 의무화함에 따라 2025년에 계량기의 디지털화를 가속화했습니다. 세번 트렌트(Severn Trent)사는 미들랜드 지역 전역에 100만 대의 LoRaWAN 계량기를 도입하여 현장 방문 대응 비용을 40% 절감했습니다. 요크셔 워터(Yorkshire Water)는 NB-IoT를 채택하고, 기존 이동통신 기지국을 활용하여 130만 대를 구축함으로써 게이트웨이 설비 투자가 필요 없게 되었습니다. 그 결과, 지방 지역을 위한 면허가 필요 없는 LoRa와 인구 밀집 도시 지역을 위한 캐리어급 NB-IoT라는 양극화가 발생하여, 병행하는 생태계가 형성되었습니다. 이로 인해 단일 프로토콜에 의존하는 전략은 위험이 높은 것으로 간주되게 되었습니다. 서브GHz, GNSS, Wi-Fi 스니핑을 결합한 Semtech사의 ‘LoRa Edge’를 통해 독일 및 프랑스의 건설 회사는 2025년에 20만 건의 고가치 자산에 태그를 부착할 수 있게 되어, 산업 간 재사용의 가능성을 시사하고 있습니다. 유틸리티 및 렌터카 업계 역시 초저전력 무선 기술에 주력하고 있으며, 출하 대수가 증가하는 가운데에서도 모듈의 평균 판매 가격(ASP)을 끌어올리고 있습니다. 무선 연결 시장에서 LPWAN의 확산은 이 부문의 ‘롱테일 및 대량 생산’이라는 특징을 더욱 강화하고 있습니다.
분열된 전 세계 주파수 정책이 Wi-Fi 7의 보급을 지연시키고 있다.
미국과 캐나다는 6GHz 대역의 주파수 대역 중 1,200 MHz를 개방했으나, 유럽에서는 실내 사용을 500 MHz로 제한하고, 중국에서는 해당 대역을 완전히 금지하고 있어, 벤더들은 지역별 SKU를 마련할 수밖에 없어 재고가 18% 증가했습니다. 브로드컴의 BCM6726은 서로 다른 EIRP 상한값에 대응하기 위해 엔지니어가 파워 앰프를 재조정하는 과정에서 9개월의 지연이 발생했으며, 이는 시장 출시까지의 기간에 숨겨진 지연이 발생하고 있음을 보여줍니다. 이러한 분열로 인해 상하이와 선전의 기업들은 WLAN 업데이트 계획을 연기하고 기존 5GHz 대역의 업그레이드를 우선시하고 있어, 단기적인 하드웨어 수요가 둔화되고 있습니다. 유럽에서는 자동 주파수 조정 요건으로 인해 인증 비용이 발생하여 중소 시스템 통합사업자에 부담을 주고 있습니다. 그 결과, 무선 연결 시장은 전 세계적인 동시 확대가 아닌, 지역별로 편차가 있는 도입 곡선에 직면해 있습니다.
부문 분석
초광대역(UWB) 매출은 연평균 성장률(CAGR) 12.46%로 증가하고 있으며, BMW와 폭스바겐이 주력 모델에 디지털 키를 탑재하고 있을 뿐만 아니라, 산업용 사업자들이 자산 추적을 위해 센티미터 단위의 위치 측위를 요구하고 있어 모든 경쟁 기술을 앞지르고 있습니다. Wi-Fi는 기업의 액세스 포인트(AP) 업데이트 주기에 힘입어 2025년 매출의 43.43%를 차지하고 있지만, 북미 이외 지역의 6GHz 대역 채널 상한선으로 인해 업그레이드가 정체되면서 그 점유율은 축소되고 있습니다. 블루투스는 연간 28억 대의 기기 출하량을 자랑하지만, SoC 벤더들이 무선 모듈을 무상으로 번들로 제공하기 시작하면서 이익률은 감소하고 있습니다. Zigbee와 Thread는 현재 Matter 프로토콜로 통합되어 있으며, 2025년에는 340개의 인증 제품이 출하되어 스마트 홈 분야의 새로운 인접 시장을 개척하고 있습니다. LoRa나 NB-IoT와 같은 LPWAN 기술은 장거리·저데이터량 센서 분야라는 틈새 시장을 개척하며, 무선 연결 시장의 ‘바벨형’ 구조를 공고히 하고 있습니다. 한쪽 끝에는 최첨단 멀티기가 확장 기술이, 다른 쪽 끝에는 초저전력 계측 기술이 있습니다.
하이브리드 통합이 현재의 로드맵을 특징짓고 있습니다. 예를 들어, Espressif사의 ESP32-C6는 Wi-Fi 6,Bluetooth 5.3, Zigbee, Thread를 하나의 다이에 탑재하고 있어, 디바이스의 상태 변화에 따라 펌웨어가 프로토콜을 전환하거나, 고속 Wi-Fi 펌웨어 업데이트를 지원하거나, Zigbee를 통한 저속 센서 버스트 통신을 가능하게 합니다. IEEE 802.15.4z의 보안 레인징은 Digital Key 3.0에서 필수 요건으로 지정되어 있으며, OEM 간 상호 운용성이 보장됩니다. 전력 소비와 정밀도 간의 상충 관계는 여전히 두드러집니다. 초광대역(UWB)은 동전형 배터리를 6개월 만에 소모시키기 때문에 그 채택은 주 전원으로 구동되는 도어락이나 인포테인먼트 허브에 집중되어 있습니다. 반면, Wi-Fi 7의 2W 전력 소비 사양으로 인해 그 적용은 충분한 방열 능력을 갖춘 기기로 제한됩니다. 이러한 성능 매트릭스를 통해 다양한 반도체 수요 프로파일이 보장되며, 무선 연결 시장은 단일 프로토콜의 부진에 대해서도 탄력성을 유지하고 있습니다.
규제 당국이 셀룰러 V2X(Vehicle-to-Everything)를 의무화하고, 보험사가 릴레이 공격을 무력화하는 초광대역 디지털 키를 할인 대상으로 삼는 가운데, 자동차용 커넥티비티 시장은 연평균 성장률(CAGR) 11.72%로 다른 분야를 앞지르고 있습니다. 제너럴 모터스는 초광대역 기능을 통합한 퀄컴 스냅드래곤 라이드를 2027년형 전 차종에 탑재하여 멀티 라디오의 기준을 확립할 예정입니다. 소비자용 전자기기는 2025년 매출의 37.23%를 차지했으나, 스마트폰 교체 주기가 3.2년으로 연장됨에 따라 판매 대수의 상향 조정 여지는 축소되었습니다. 산업용 자동화 분야에서는 자율형 로봇 및 머신 비전 시스템을 통합하기 위해 프라이빗 5G와 Wi-Fi 6E가 활용되고 있으나, 설비 투자 속도는 5년 주기의 PLC(프로그래머블 로직 컨트롤러) 교체 주기와 연동되어 있습니다. 헬스케어 분야에서는 독자 규격의 무선 기술에서 블루투스 저에너지(Bluetooth Low Energy) 5.4로의 전환이 진행되고 있지만, 규제 당국의 승인으로 인해 상용화가 18-36개월 지연되고 있습니다. 유틸리티용 계측 분야에서는 NB-IoT 및 LoRa로의 전환이 진행되고 있으며, 무선 연결 시장은 비동기적인 수요 곡선이 얽혀 복잡한 양상을 띠고 있습니다.
자동차 분야의 가치 창출은 독립적인 텔레매틱스 박스에서 셀룰러, Wi-Fi, Bluetooth, 초광대역 통신을 통합한 도메인 컨트롤러로 전환되고 있으며, 이로 인해 부품 원가(BOM)가 20% 절감되고 있습니다. 소비자용 전자기기는 Wi-Fi 7 및 초광대역 통신을 탑재한 프리미엄 단말기와 Wi-Fi 5에 머무르는 가성비형 단말기의 두 가지로 나뉘고 있습니다. 산업용 OEM 제조업체들은 광범위한 작동 온도 범위와 IP67 규격 준수를 요구하고 있지만, 이 분야는 현재 주류 엔터프라이즈 WLAN 벤더들이 충분히 커버하지 못하고 있습니다. 의료 관련 기업들은 FDA의 사이버 보안 규정에 따라 인증 템플릿이 명확해지는 대로 블루투스 5.4를 채택하여 2027년부터 2028년에 걸친 파이프라인의 가시성을 높일 것입니다. 이러한 부문 간 동향은 위험과 기회를 분산시키고, 무선 연결 시장의 꾸준한 성장을 뒷받침하고 있습니다.
지역별 분석
아시아태평양은 중국의 5G 구축, 인도의 스마트 시티 계획, 일본의 ‘사회 5.0’ 이니셔티브에 힘입어 2025년 지출의 34.51%를 차지했습니다. 중국은 2024년부터 모든 신규 공공 요금 계량기에 NB-IoT 채택을 의무화하여 4억 대 규모의 잠재 시장을 창출했습니다. 인도는 디지털 인프라에 4,800억 루피(58억 달러)를 배정하여 도시 전역을 커버하는 Wi-Fi 및 IoT 센서 네트워크 기반을 구축했습니다. 도요타는 2025년, 자율주행차를 유도하기 위해 12개 공장에 에릭슨의 프라이빗 5G를 도입하여 공장 내 수요를 촉진했습니다. 동남아시아에서는 농업 기술(애그테크)을 위해 LoRaWAN 네트워크가 도입되어, 2025년까지 240만 개의 토양 수분 센서가 연결될 전망입니다.
중동은 연평균 성장률(CAGR) 12.02%로 가장 빠른 성장 궤도를 보이고 있으며, 사우디아라비아 공공투자기금(PIF)은 5G, Wi-Fi 6E, mm파 백홀을 융합한 NEOM의 통합형 광섬유·무선 네트워크에 200억 달러를 투자했습니다. 아랍에미리트(UAE)는 2025년에 6GHz 대역 주파수 라이선스를 경매에 부쳤으며, du사와 에티살라트사가 두바이에서 Wi-Fi 7을 활용한 고정 무선 연결 서비스를 제공할 수 있게 되었습니다. 튀르키예는 실내에서 6GHz 대역 사용을 승인하여 이스탄불 내 기업용 Wi-Fi 6E 도입을 촉진하고 있습니다. 아프리카에서는 NB-IoT가 주류를 이루고 있으며, MTN 그룹은 2025년에 남아프리카공화국에 120만 대의 스마트 계량기를 설치할 예정입니다.
북미와 유럽에서는 인프라가 성숙해져 신규 도입이 제한적이며, 연평균 성장률(CAGR)은 8-9%에 그치고 있습니다. 그러나 미국 내 6GHz 대역의 조기 자유화가 WLAN의 지속적인 업데이트를 뒷받침하고 있어, 시스코의 6GHz 대역 액세스 포인트(AP) 보급률은 이미 20%를 넘어섰습니다. 멕시코가 2025년에 승인한 규제로 인해 북미 전체의 규정이 통일되어 SKU 수가 감소했습니다. 유럽에서는 규제 상황이 제각각이어서 성장세가 둔화되고 있습니다. 6GHz 대역이 실내 전용이라는 점, 초광대역(UWB)의 출력 제한이 국가마다 다르다는 점, 그리고 국가별로 다른 NB-IoT 주파수가 규제 준수를 가로막는 요인으로 작용하고 있습니다. 독일에서는 2025년까지 450건의 사설 5G 라이선스가 발급되었으나, 그 대부분은 자동차 및 화학 관련 시설용입니다. 영국은 2024년에 6GHz 대역의 실내용 주파수 대역 전체를 개방하여 런던 내 Wi-Fi 7의 보급을 가속화했습니다. 브라질의 주파수 대역에 관한 협의는 여전히 해결되지 않은 상태이며, 이로 인해 해당 국가에서의 6GHz WLAN 도입이 지연되고 있습니다. 전반적으로, 지역별 정책은 규제의 불균일성에 유연하게 대응할 수 있는 벤더에게 이점을 제공하는 다양한 속도의 무선 연결 시장을 형성하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the wireless connectivity market size is projected to be USD 101.87 billion in 2025, USD 113.69 billion in 2026, and reach USD 196.12 billion by 2031, growing at a CAGR of 11.52% from 2026 to 2031.
This report is Segmented by Technology (Wi-Fi, Bluetooth, and More), End-User Industry (Consumer Electronics, Automotive, and More), Frequency Band (Sub-1 GHz, 2. 4 GHz, and 6 GHz), Device Type (Smartphones and Tablets, Smart Home Devices, and More), and Geography (North America, Europe, Asia Pacific, South America, Middle East, Africa). The Market Forecasts are Provided in Terms of Value in USD.
Global Wireless Connectivity Market Trends and Insights
Surge of Wi-Fi 6/6E/7 Chipsets in Consumer and Industrial IoT
Enterprise shipments of Wi-Fi 7 access points reached 12% of new WLAN units in Q1 2025, although headline 46 Gbps throughput remains aspirational because most client devices still lack 320 MHz support. Multi-link operation lets a factory sensor send time-critical packets over 6 GHz while placing bulk data on 5 GHz, holding jitter below 5 ms in congested rooms. Broadcom shipped 18 million Wi-Fi 7 combo chips during 2025, with industrial gateways driving half of that volume. The shift from star to mesh-plus-gateway topologies forces legacy PLC makers to redesign backplanes, creating a 24-month refresh cycle that sustains double-digit chipset growth into 2027. Module suppliers that layer AI-based interference mitigation into firmware are securing long-term supply agreements, insulating margins even as silicon prices wobble due to node scarcity. Consequently, the wireless connectivity market finds Wi-Fi 7 adoption gating many factory-automation upgrades.
Expansion of LPWAN Modules for Smart-Meter Roll-Outs
European utilities accelerated meter digitization in 2025 after regulators mandated 15-minute interval data. Severn Trent deployed 1 million LoRaWAN meters across the Midlands and slashed truck-roll costs by 40%. Yorkshire Water opted for NB-IoT, rolling out 1.3 million units that piggy-back on existing cellular towers, eliminating gateway capex. The resulting bifurcation unlicensed LoRa for rural districts versus carrier-grade NB-IoT in dense metros creates parallel ecosystems where single-protocol strategies now look risky. Semtech's LoRa Edge, which combines sub-GHz, GNSS, and Wi-Fi sniffing, allowed German and French construction firms to tag 200 000 high-value assets during 2025, hinting at cross-vertical reuse. Utilities and rental fleets alike converge on ultra-low-power radios, boosting module ASPs even as volumes scale. For the wireless connectivity market, LPWAN roll-outs reinforce the sector's long-tail, high-volume profile.
Fragmented Global Spectrum Policy Slowing Wi-Fi 7 Adoption
The United States and Canada opened 1200 MHz of 6 GHz spectrum, yet Europe caps indoor use at 500 MHz and China bars the band entirely, obliging vendors to field regional SKUs that inflate inventory by 18%. Broadcom's BCM6726 slipped nine months while engineers retuned power amps to meet disparate EIRP ceilings, illustrating hidden time-to-market penalties. Such fragmentation causes enterprises in Shanghai and Shenzhen to delay WLAN refresh plans in favor of legacy 5 GHz upgrades, muting near-term hardware demand. In Europe, automated frequency coordination requirements add certification fees that squeeze small integrators. Consequently, the wireless connectivity market faces a patchwork adoption curve rather than a synchronized global ramp.
Other drivers and restraints analyzed in the detailed report include:
- Private 5G and Wi-Fi Co-Existence Driving Multi-Radio Gateways
- Government-Funded Open-Roaming City Networks
- Persistent Bluetooth Security Exploits in Medical Wearables
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ultra-wideband revenue is rising at a 12.46% CAGR, outpacing all rival technologies as BMW and Volkswagen embed digital keys in mainstream models, while industrial operators demand centimeter-grade positioning for asset tracking. Wi-Fi still anchored 43.43% of 2025 receipts, buoyed by enterprise AP refresh cycles, yet its share erodes as 6 GHz channel caps outside North America stall upgrades. Bluetooth rides 2.8 billion annual device shipments, but its margin pool narrows as SoC vendors bundle radios without extra cost. Zigbee and Thread, now converged under the Matter protocol, shipped 340 certified products in 2025, opening fresh smart-home adjacencies. LPWAN variants such as LoRa and NB-IoT carve out long-range, low-data sensor niches, solidifying the wireless connectivity market's barbell pattern, bleeding-edge multi-gig extensions at one end and ultra-low-power metering on the other.
Hybrid integration defines current roadmaps. Espressif's ESP32-C6, for instance, hosts Wi-Fi 6, Bluetooth 5.3, Zigbee, and Thread on one die, letting firmware switch protocols as device states shift, support high-rate Wi-Fi firmware updates, and enable low-rate sensor bursts on Zigbee. IEEE 802.15.4z secure ranging is now mandatory for Digital Key 3.0, ensuring interoperability across OEMs. Power-accuracy trade-offs remain stark: ultra-wideband drains a coin cell in six months, so adoption clusters around mains-powered door locks and infotainment hubs. Meanwhile, Wi-Fi 7's 2 W draw confines it to devices with robust thermal budgets. This performance matrix guarantees diverse silicon demand profiles, keeping the wireless connectivity market resilient to single-protocol downturns.
Automotive connectivity outstrips all peers at an 11.72% CAGR as regulators mandate cellular vehicle-to-everything and insurers discount ultra-wideband digital keys that defeat relay attacks. General Motors will embed Qualcomm Snapdragon Ride with integrated ultra-wideband in all 2027 models, locking in multi-radio baselines. Consumer electronics still contributed 37.23% of 2025 revenue, yet smartphone refresh cycles expanded to 3.2 years, trimming unit upside. Industrial automation leans on private 5G and Wi-Fi 6E to orchestrate autonomous robots and machine-vision systems, but the capex cadence aligns with five-year PLC refreshes. Healthcare transitions from proprietary radios to Bluetooth Low Energy 5.4, but regulatory approval extends commercialization by 18-36 months. Utility metering continues its pivot to NB-IoT and LoRa, making the wireless connectivity market a tapestry of asynchronic demand curves.
Value creation in automotive is shifting from discrete telematics boxes to integrated domain controllers that aggregate cellular, Wi-Fi, Bluetooth, and ultra-wideband, chopping BOMs by 20%. Consumer electronics splits into premium devices sporting Wi-Fi 7 and ultra-wideband, and value tiers staying on Wi-Fi 5. Industrial OEMs demand extended temperature and IP67 ratings, an area mainstream enterprise WLAN vendors currently under-serve. Healthcare firms adopt Bluetooth 5.4 once FDA cybersecurity rules clarify certification templates, bolstering pipeline visibility for 2027-2028. These cross-sector rhythms distribute risk and opportunity, underpinning steady expansion in the wireless connectivity market.
Complete Report Scope:
- By Technology
- Wi-Fi
- Bluetooth
- Zigbee
- NFC
- Cellular (4G/5G)
- LPWAN (LoRa, NB-IoT, Sigfox)
- UWB
- Other Technologies
- By End-User Industry
- Consumer Electronics
- Automotive
- Industrial and Manufacturing
- Healthcare and Medical Devices
- Energy and Utilities
- Smart Infrastructure and Buildings
- Other End-User Industries
- By Frequency Band
- Sub-1 GHz
- 2.4 GHz (Legacy Wi-Fi/BLE Devices)
- 6 GHz (Wi-Fi 6E / Wi-Fi 7)
- By Device Type
- Smartphones and Tablets
- Industrial IoT Sensors
- Wearables
- Smart Home Devices
- Automotive Systems
- Healthcare Devices
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Australia and New Zealand
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Saudi Arabia
- Saudi Arabia
- United Arab Emirates
- UAE
- Turkey
- Turkey
- Rest of Middle East
- Rest of Middle East
- Africa
- South Africa
- South Africa
- Nigeria
- Nigeria
- Kenya
- Rest of Africa
- Rest of Africa
- North America
Geography Analysis
Asia Pacific retained 34.51% of 2025 spending, propelled by China's 5G roll-out, India's smart-city program, and Japan's Society 5.0 initiative. China mandated NB-IoT in all new utility meters starting 2024, seeding a 400 million-unit addressable base. India allocated INR 480 billion (USD 5.8 billion) for digital infrastructure, underpinning city-wide Wi-Fi and IoT sensor nets. Toyota equipped 12 plants with Ericsson private 5G in 2025 to guide autonomous vehicles, reinforcing factory demand. Southeast Asia adds LoRaWAN networks for ag-tech, connecting 2.4 million soil-moisture probes by 2025.
The Middle East shows the fastest trajectory at 12.02% CAGR, as Saudi Arabia's Public Investment Fund committed USD 20 billion to NEOM's converged fiber-wireless grid, blending 5G, Wi-Fi 6E, and millimeter-wave backhaul. The UAE auctioned 6 GHz licenses in 2025, allowing du and Etisalat to deploy Wi-Fi 7 fixed-wireless access in Dubai. Turkey approved indoor 6 GHz use, catalyzing enterprise Wi-Fi 6E in Istanbul. Africa clusters around NB-IoT, with MTN Group installing 1.2 million smart meters in South Africa during 2025.
North America and Europe log 8-9% CAGR as mature fleets limit new installs. Yet U.S. early 6 GHz liberalization spurs continual WLAN refresh; Cisco's 6 GHz AP penetration already tops 20%. Mexico's 2025 approval harmonized North American rules, easing SKU counts. Europe's patchwork slows momentum, indoor-only 6 GHz, varying ultra-wideband power caps, and country-specific NB-IoT frequencies pose compliance drag. Germany issued 450 private 5G licenses by 2025, largely to automotive and chemical sites. The UK opened the whole 6 GHz indoor band in 2024, accelerating Wi-Fi 7 uptake in London. Brazil's spectrum consultation remains unresolved, delaying 6 GHz WLAN there. Overall, geography-specific policy shapes a multi-speed wireless connectivity market that rewards vendors agile enough to handle regulatory heterogeneity.
- Qualcomm Incorporated
- Broadcom Inc.
- MediaTek Inc.
- Intel Corporation
- Texas Instruments Inc.
- NXP Semiconductors N.V.
- STMicroelectronics
- Nordic Semiconductor
- Microchip Technology Inc.
- Renesas Electronics Corp.
- Samsung Electronics Co.
- Infineon Technologies AG
- Silicon Laboratories Inc.
- Murata Manufacturing Co.
- Skyworks Solutions Inc.
- Marvell Technology Group Ltd.
- Huawei Technologies Co.
- Qorvo Inc.
- u-blox AG
- Semtech Corporation
- Espressif Systems
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge of Wi-Fi 6/6E/7 Chipsets in Consumer and Industrial IoT
- 4.2.2 Expansion of LPWAN Modules for Smart-Meter Roll-Outs
- 4.2.3 Private 5G and Wi-Fi Co-Existence Driving Multi-Radio Gateways
- 4.2.4 Government-Funded Open-Roaming City Networks
- 4.2.5 AI-Driven Self-Optimising Wireless Networks in Factories
- 4.2.6 Millimetre-Wave Backhaul for Rural FWA Programs
- 4.3 Market Restraints
- 4.3.1 Fragmented Global Spectrum Policy Slowing Wi-Fi 7 Adoption
- 4.3.2 Persistent Bluetooth Security Exploits in Medical Wearables
- 4.3.3 Rising Silicon Costs Due to Advanced Node Scarcity
- 4.3.4 EMC Compliance Hurdles for UWB in Automotive Cabins
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Wi-Fi
- 5.1.2 Bluetooth
- 5.1.3 Zigbee
- 5.1.4 NFC
- 5.1.5 Cellular (4G/5G)
- 5.1.6 LPWAN (LoRa, NB-IoT, Sigfox)
- 5.1.7 UWB
- 5.1.8 Other Technologies
- 5.2 By End-User Industry
- 5.2.1 Consumer Electronics
- 5.2.2 Automotive
- 5.2.3 Industrial and Manufacturing
- 5.2.4 Healthcare and Medical Devices
- 5.2.5 Energy and Utilities
- 5.2.6 Smart Infrastructure and Buildings
- 5.2.7 Other End-User Industries
- 5.3 By Frequency Band
- 5.3.1 Sub-1 GHz
- 5.3.2 2.4 GHz (Legacy Wi-Fi/BLE Devices)
- 5.3.3 6 GHz (Wi-Fi 6E / Wi-Fi 7)
- 5.4 By Device Type
- 5.4.1 Smartphones and Tablets
- 5.4.2 Industrial IoT Sensors
- 5.4.3 Wearables
- 5.4.4 Smart Home Devices
- 5.4.5 Automotive Systems
- 5.4.6 Healthcare Devices
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN
- 5.5.3.6 Australia and New Zealand
- 5.5.3.7 Rest of Asia Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Kenya
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Qualcomm Incorporated
- 6.4.2 Broadcom Inc.
- 6.4.3 MediaTek Inc.
- 6.4.4 Intel Corporation
- 6.4.5 Texas Instruments Inc.
- 6.4.6 NXP Semiconductors N.V.
- 6.4.7 STMicroelectronics
- 6.4.8 Nordic Semiconductor
- 6.4.9 Microchip Technology Inc.
- 6.4.10 Renesas Electronics Corp.
- 6.4.11 Samsung Electronics Co.
- 6.4.12 Infineon Technologies AG
- 6.4.13 Silicon Laboratories Inc.
- 6.4.14 Murata Manufacturing Co.
- 6.4.15 Skyworks Solutions Inc.
- 6.4.16 Marvell Technology Group Ltd.
- 6.4.17 Huawei Technologies Co.
- 6.4.18 Qorvo Inc.
- 6.4.19 u-blox AG
- 6.4.20 Semtech Corporation
- 6.4.21 Espressif Systems
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


