|
시장보고서
상품코드
2124051
지방족 탄화수소 용제 및 희석제 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Aliphatic Hydrocarbon Solvents And Thinners - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 지방족 탄화수소 용제 및 희석제 시장 규모는 2026년에 407만 톤으로 추정되고, 예측 기간(2026-2031년) CAGR 3.51%로 성장을 지속할 전망이며, 2031년까지 501만 톤에 이를 전망입니다.
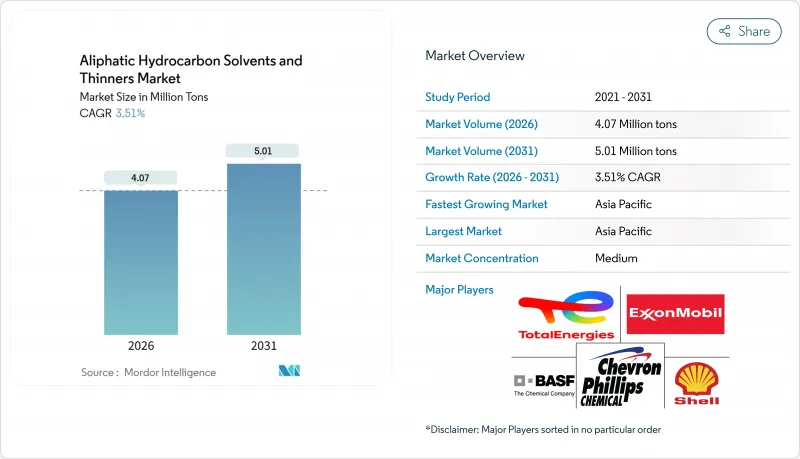
본 보고서는 용제 유형별(헥산, 헵탄, 미네랄 스피릿, 가솔린, 기타), 용도별(페인트 및 코팅, 접착제, 세정·탈지, 고무 제조, 기타) 및 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 수량(톤) 단위로 표시되어 있습니다.
세계의 지방족 탄화수소 용제 및 희석제 시장 동향 및 인사이트
페인트 및 코팅 분야에서의 용도 확대
2024년 전 세계 도료 생산량은 4,830만 톤에 달한 것으로 평가되었으며, 수성 도료의 점유율이 지속적으로 확대되고 있음에도 불구하고 용제형 도료의 배합은 여전히 총량의 38%를 차지하고 있습니다. BASF가 상하이에 건설한 연산 5만 톤 규모의 알키드 수지 생산 라인 등 생산 능력 확충은 중국의 GB 24409-2020 VOC 규제치 이내로 맞추기 위해 지방족 신너가 필요한 OEM용 프라이머 및 금속용 탑코트를 특히 목표로 하고 있습니다. 신축 공사보다 유지보수를 통한 재도장이 톤수 증가를 더욱 주도하고 있습니다. 이는 노후화된 자산에는 더 두꺼운 도막 두께와 다층 도장 시스템이 필요하기 때문입니다. 인도에서는 주요 제조업체들이 2025년까지 일일 120만 리터의 생산 능력을 증강했으며, 이는 현지 공급업체를 뒷받침하는 용제 수요 증가로 이어지고 있습니다. 그러나 캘리포니아주가 2027년에 산업용 유지보수 도료의 VOC 농도를 100 g/L로 제한하는 안을 제시하는 등, 정책 동향에 따라 미국 서부 해안 시장에서는 용제 사용량이 감소할 것으로 예측됩니다. 따라서 배합 설계자들은 엄격해지는 VOC 상한치를 준수하면서도 용해력과 건조 시간의 성능을 극대화해야 하는 줄타기 같은 상황에 놓여 있습니다.
접착제 및 실란트 분야 수요 증가
용제형 접착제 시스템은 긴 개방 시간, 신속한 초기 강도 및 저온에서의 도포가 여전히 필수적인 분야에서 틈새 시장의 중요성을 유지하고 있습니다. 2024년에 헨켈(Henkel)이 출시한 헥산·헵탄 혼합물은 경화 시간을 30% 단축하고 라미네이팅 라인의 속도를 325 m/min까지 높였습니다. 이는 용제 화학의 점진적인 발전이 새로운 설비를 도입하지 않고도 처리 능력을 향상시킬 수 있음을 보여줍니다. 아시아태평양의 소포 물량 급증으로 인해 점착 라벨 및 테이프 생산량이 계속 증가하고 있으며, 이에 따라 미네랄 스피릿에 대한 수요도 유지되고 있습니다. 중동에서 진행 중인 2조 8,000억 달러 규모의 프로젝트가 폴리우레탄계 실란트 수요를 뒷받침하고 있으며, 커튼월 1제곱미터당 여전히 용제 함유 실란트가 필요합니다. 수성 아크릴계 제품이 건설 분야에서 점차 시장 점유율을 확대하고 있지만, 접착 신뢰성이 VOC(휘발성 유기 화합물)에 대한 우려를 상회하는 까다로운 파사드나 신축 이음매 등의 공사에서는 용제계 배합이 여전히 주류를 이루고 있습니다.
엄격한 VOC 및 유해 대기 오염 물질 규제
미국 환경보호청(EPA)은 2024년 12월, 건축용 마감재의 VOC 상한치를 무광 도료의 경우 50 g/L, 유광 도료의 경우 150 g/L로 낮추고, 용제 함유율을 약 15 wt%로 감축했습니다. 캘리포니아주는 더욱 엄격한 조치를 취하여, SCAQMD 규정 1113을 통해 실내용 무광 도료에 10 g/L의 상한선을 부과함으로써, 해당 주라는 최대 지역 시장에서 사실상 용제 사용을 금지했습니다. 중국도 이에 발맞추어 GB 30981.1-2025를 제정하여 산업용 세정 용제 내 방향족 함유량을 0.5 중량%로 제한했습니다. 규제 준수에 드는 비용은 치솟고 있으며, 한 중규모 독일 도료 제조업체는 2024년에 배합 변경에만 250만 달러를 지출했습니다. 이는 저방향족 등급 제품이 일시적인 해결책이 될지라도, 규제 강화가 수요를 잠식하고 있는 실정을 여실히 보여줍니다.
부문 분석
헥산은 유지종자 추출 및 합성 고무 제조 공정에서 필수적인 물질이기 때문에 2025년에는 지방족 탄화수소 용제 및 희석제 시장의 29.30%를 차지했습니다. 브라질, 아르헨티나 및 미국 중서부 지역의 생산 능력 확대에 힘입어, 2024년 식용유 가공 분야의 전 세계 사용량은 118만 톤에 달했습니다. 헵탄은 규모는 작지만, 의약품 합성에서 높은 인화점 및 낮은 독성이 중요하게 여겨지기 때문에 2031년까지 연평균 성장률(CAGR) 4.38%로 가장 높은 성장률을 나타낼 것으로 예측됩니다. 미네랄 스피릿은 도료 희석 및 산업용 세정의 주력으로 여전히 중요한 위치를 차지하고 있지만, 유럽의 초저방향족 기준을 준수하기 위해 수소화 처리에 드는 추가 비용을 흡수해야 합니다. 산업안전규정에 따라 인화점 높은 대체품이 권장됨에 따라, 가솔린 시장 점유율은 지속적으로 하락하고 있습니다. VM&P 나프타나 무취 유형을 포함한 특수 블렌드는 틈새 시장인 인쇄 잉크 및 에어로졸 추진제 분야에 공급되어 다양성을 높이고 있지만, 추가적인 성장은 제한적입니다.
미네랄 스피릿 공급업체들은 순도를 통해 차별화를 꾀하고 있습니다. 방향족 함량이 중량 기준 1% 미만인 ‘ShellSol D60’은 2024년 유럽 산업용 세정제 시장에서 18%의 점유율을 차지했습니다. 엑슨모빌의 베이트타운 정유시설 개보수는 나프탈렌 함량을 10ppm 미만으로 줄이려는 노력을 강조하는 것으로, 이를 통해 의약품 및 식품 접촉 시장에 진출할 수 있게 됩니다. 용제 품질 규격이 엄격해지는 가운데, 수소 처리 설비를 보유한 기업들은 프리미엄 가격을 책정할 수 있어, 판매량 감소라는 역풍에도 불구하고 이 부문의 수익성을 유지하고 있습니다.
지역별 분석
아시아태평양은 2025년 판매량의 41.08%를 차지한 것으로 평가되었으며, 이 지역의 지방족 탄화수소 용제 및 희석제 시장은 2031년까지 연평균 성장률(CAGR) 4.32%를 나타낼 것으로 전망됩니다. 중국은 도시 지역의 외관 도장 및 산업 인프라 분야를 주도하며 안정적인 수요를 창출하고 있습니다. 인도에서는 연간 590만 대의 자동차 생산에 더해 진행 중인 도로 건설이 용제 수요를 견인하고 있으며, 계획적인 도료 생산 능력 확대가 하류 수요의 확대를 약속하고 있습니다. 성숙 시장인 일본과 한국은 자동차 보수 도장을 배경으로 완만한 성장을 보이고 있는 반면, 아세안(ASEAN) 국가들은 전자기기 조립 및 건설과 관련하여 한 자릿수 중반대의 성장률을 기록하고 있습니다.
북미 시장 점유율에는 국가별 서로 다른 추세가 숨어 있습니다. 미국에서는 용제형 도료가 주로 실외용 목재, 고광택 도료, 특수 프라이머에 사용되고 있지만, VOC 규제의 대폭적인 강화로 인해 1리터당 용제 사용량은 꾸준히 감소하고 있습니다. 캐나다는 용제형 도료의 경화에 적합한 추운 기후를 활용하고 있습니다. 멕시코는 자동차 산업의 니어쇼어링의 혜택을 받고 있으며, 미네랄 스피릿을 이용한 세정에 관해 더 엄격한 방화 기준이 유지되고 있습니다.
유럽은 가장 엄격한 VOC 규제를 직면하고 있습니다. 독일에서는 자동차 생산 라인이 수성 베이스 코트로 전환됨에 따라 사용량이 감소했습니다. 영국에서는 선박 및 해양용 보호 코팅 분야에서 수요가 유지되었습니다. 북유럽 국가들은 미네랄 스피릿을 이용한 목재 마감의 전통을 이어가고 있는 반면, 동유럽은 규제 조화가 늦어지고 있는 성장 거점으로 부상하고 있습니다. 러시아는 국내 정제 및 수입 대체 정책에 힘입어 성장했습니다.
남미는 브라질이 주도하고 있으며, 건설 및 자동차 재도장 시장과 밀접하게 연관되어 있습니다. 아르헨티나에서는 염화리튬 분리 시 헥산을 사용하는 리튬 염수 추출 공법으로 인해 시장 위축이 완화되었습니다. 중동 및 아프리카를 합친 지역에서는 사우디아라비아의 메가 프로젝트와, 용제를 다량 사용하는 재도장 시스템이 필요한 남아프리카공화국의 노후된 자동차 보유 대수를 배경으로 상당한 성장이 나타났습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the aliphatic hydrocarbon solvents and thinners market size is estimated at 4.07 Million tons in 2026, and is expected to reach 5.01 Million tons by 2031, at a CAGR of 3.51% during the forecast period (2026-2031).
This report is Segmented by Solvent Type (Hexane, Heptane, Mineral Spirits, Gasoline, and Others), Application (Paints and Coatings, Adhesives, Cleaning and Degreasing, Rubber Manufacturing, and Others), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Volume (Tons).
Global Aliphatic Hydrocarbon Solvents And Thinners Market Trends and Insights
Increasing Application in Paints and Coatings
Global paint output climbed to 48.3 million tons in 2024, and solvent-borne formulations still represented 38% of that total despite continued water-borne gains. Capacity additions-such as BASF's 50,000-ton-per-year alkyd-resin line in Shanghai-specifically target OEM primers and metal topcoats that require aliphatic thinners to remain within China's GB 24409-2020 VOC limits. Maintenance repainting, rather than new construction, increasingly drives tonnage because older assets need higher film-build and multi-coat systems. In India, organized producers lifted manufacturing capacity by 1.2 million liters per day through 2025, translating into incremental solvent demand that supports local suppliers. Yet policy developments, including California's proposed 2027 limit of 100 g/L VOC in industrial maintenance coatings, foreshadow lower solvent intensity in western U.S. markets. Formulators therefore walk a tightrope: maximize solvency and dry-time performance while staying under tightening VOC ceilings.
Expanding Demand from Adhesives and Sealants
Solvent-based adhesive systems retain niche relevance wherever extended open time, rapid green-strength, and low-temperature application remain mandatory. A hexane-heptane blend released by Henkel in 2024 cut cure time by 30% and lifted laminating line speeds to 325 m/min, illustrating how incremental solvent chemistry advances can unlock throughput gains without new equipment. Rapid parcel growth in Asia-Pacific keeps pressure-sensitive label and tape output rising, thereby sustaining mineral-spirits demand. The Middle East's USD 2.8 trillion active project pipeline underpins polyurethane-sealant volumes, and each square meter of curtain wall still requires solvent-containing sealant. Although water-borne acrylics nibble at construction segments, solvent formulations continue to dominate demanding facade and expansion-joint jobs where bond reliability outweighs VOC considerations.
Stringent VOC and Hazardous-Air-Pollutant Regulations
The U.S. EPA slashed VOC limits on architectural finishes to 50 g/L for flat paints and 150 g/L for non-flat coatings in December 2024, cutting solvent loading to roughly 15 wt %. California doubled down, imposing a 10 g/L ceiling on interior flats through SCAQMD Rule 1113, effectively banning solvents in the largest local market. China followed suit with GB 30981.1-2025, capping aromatic content in industrial cleaning solvents at 0.5 wt %. Compliance costs escalate; a mid-sized German paint maker spent USD 2.5 million in 2024 on reformulations alone, underscoring how regulatory stringency erodes demand even where low-aromatic grades offer interim relief.
Other drivers and restraints analyzed in the detailed report include:
- Growth in Construction Activities Globally
- Rising Automotive Refinishing Volumes
- Growing Adoption of Water-Borne and High-Solids Coatings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hexane commanded 29.30% of the aliphatic hydrocarbon solvents and thinners market in 2025, owing to its indispensability in oilseed extraction and synthetic-rubber workflows. Global usage in edible-oil processing reached 1.18 million tons in 2024 following capacity additions across Brazil, Argentina, and the U.S. Midwest. Heptane, while smaller, is forecast to post the fastest 4.38% CAGR through 2031 because pharmaceutical synthesis values its higher flash point and lower toxicity. Mineral spirits remain the workhorse of paint thinning and industrial cleaning but must absorb incremental hydrotreatment costs to comply with Europe's ultra-low-aromatic thresholds. Gasoline's share continues to slide as occupational-safety rules favor higher-flash-point alternatives. Specialty blends, including VM&P naphtha and odorless variants, supply niche printing-ink and aerosol-propellant segments, adding diversity but limited incremental growth.
Mineral-spirits suppliers pursue differentiation via purity. ShellSol D60's aromatic content below 1 wt % achieved 18% penetration in European industrial cleaning in 2024. ExxonMobil's Baytown retrofit underscores the drive to cut naphthalene content under 10 ppm, opening pharmaceutical and food-contact markets. As solvent-quality specifications tighten, players with hydrotreating assets can command premiums, keeping this segment profitable despite volume headwinds.
Complete Report Scope:
- By Solvent Type
- Hexane
- Heptane
- Mineral Spirits
- Gasoline
- Others
- By Application
- Paints and Coatings
- Adhesives
- Cleaning and Degreasing
- Rubber Manufacturing
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 41.08% of 2025 volume, and the aliphatic hydrocarbon solvents and thinners market in the region is projected to post a 4.32% CAGR through 2031. China leads on urban facade repainting and industrial infrastructure, generating steady offtake. India's 5.9 million vehicle output plus ongoing road-building propel solvent demand, and organized paint capacity expansions promise downstream pull. Mature markets Japan and South Korea grow modestly on automotive refinishing, while ASEAN members register mid-single-digit gains tied to electronics assembly and construction.
North America's share masks diverging patterns. The United States uses solvent-borne paints mainly in exterior wood, high-gloss, and specialty primers, but Step-change VOC rules steadily erode per-liter solvent intensity. Canada leverages colder climates that favor solvent-borne curing. Mexico gains from automotive nearshoring and maintains stricter fire-code allowances for mineral-spirits cleaning.
Europe faces the toughest VOC regimes. Germany's usage slipped as automotive lines switched to water-borne basecoats. The United Kingdom preserved demand in marine and offshore protective coatings. Nordic countries defend mineral-spirits wood-finishing traditions, while Eastern Europe remains a pocket of growth where regulatory alignment lags. Russia grew on local refining and import-substitution policies.
South America is dominated by Brazil, tied to construction and vehicle refinishing. Argentina's contraction was mitigated by lithium-brine extraction, which employs hexane for lithium chloride separation. The Middle East and Africa combined delivered substantial growth, led by Saudi Arabia's megaprojects and South Africa's aging vehicle parc requiring solvent-rich refinish systems.
- BASF
- Brenntag SE
- Calumet Specialty Products Partners L.P.
- Chevron Phillips Chemical Company LLC
- Citgo Petroleum Corporation
- Exxon Mobil Corporation
- Gadiv Petrochemical Industries Ltd.
- Gandhar Oil Refinery (India) Limited.
- Honeywell International Inc.
- Hunt Refining Company
- Idemitsu Kosan Co.,Ltd.
- LyondellBasell Industries N.V.
- MG Organics Pvt. Ltd.
- Phillips 66
- Recochem Inc.
- Sasol Limited
- Shell plc
- SK geo centric Co., Ltd.
- TotalEnergies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Application in Paints and Coatings
- 4.2.2 Expanding Demand from Adhesives and Sealants
- 4.2.3 Growth in Construction Activities Globally
- 4.2.4 Rising Automotive Refinishing Volumes
- 4.2.5 Shift Toward Low-Aromatic Health-Safer Grades
- 4.3 Market Restraints
- 4.3.1 Stringent VOC and Hazardous-Air-Pollutant Regulations
- 4.3.2 Growing Adoption of Water-Borne and High-Solids Coatings
- 4.3.3 Volatility in Naphtha-Based Feedstock Supply
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Solvent Type
- 5.1.1 Hexane
- 5.1.2 Heptane
- 5.1.3 Mineral Spirits
- 5.1.4 Gasoline
- 5.1.5 Others
- 5.2 By Application
- 5.2.1 Paints and Coatings
- 5.2.2 Adhesives
- 5.2.3 Cleaning and Degreasing
- 5.2.4 Rubber Manufacturing
- 5.2.5 Others
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 NORDIC Countries
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BASF
- 6.4.2 Brenntag SE
- 6.4.3 Calumet Specialty Products Partners L.P.
- 6.4.4 Chevron Phillips Chemical Company LLC
- 6.4.5 Citgo Petroleum Corporation
- 6.4.6 Exxon Mobil Corporation
- 6.4.7 Gadiv Petrochemical Industries Ltd.
- 6.4.8 Gandhar Oil Refinery (India) Limited.
- 6.4.9 Honeywell International Inc.
- 6.4.10 Hunt Refining Company
- 6.4.11 Idemitsu Kosan Co.,Ltd.
- 6.4.12 LyondellBasell Industries N.V.
- 6.4.13 MG Organics Pvt. Ltd.
- 6.4.14 Phillips 66
- 6.4.15 Recochem Inc.
- 6.4.16 Sasol Limited
- 6.4.17 Shell plc
- 6.4.18 SK geo centric Co., Ltd.
- 6.4.19 TotalEnergies
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment