|
시장보고서
상품코드
2124053
북미의 상업용 LED 조명 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Commercial LED Lighting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
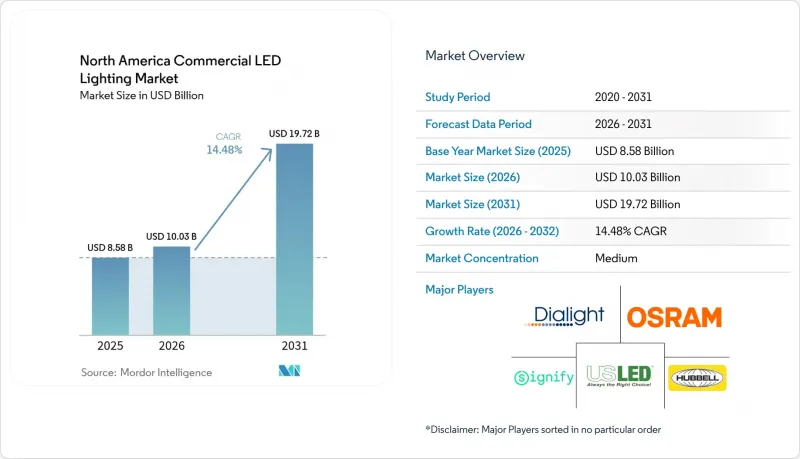
에 의하면, 북미 상업용 LED 조명 시장 규모는 2025년 85억 8,000만 달러, 2026년 100억 3,000만 달러에서 2031년까지 197억 2,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 14.48%를 나타낼 것으로 예측됩니다.
본 보고서는 용도별(소매점, 사무실, 호텔 및 레스토랑, 건축, 의료시설, 교육 기관, 산업·창고 등), 형태별(트로퍼 등), 유통 채널별(직접 판매 등), 설치 형태별(신축, 개보수), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미 상업용 LED 조명 시장 동향 및 인사이트
엄격한 에너지 효율 규정 및 건축 기준
새로운 연방 및 주 기준에 따라 기존 조명 기구의 대부분이 배제됨에 따라, 소유주들은 투자 회수 계산이 불완전한 경우에도 형광등을 교체하고 있습니다. 2024년에 확정된 미국 규정에서는 할로겐 램프 및 백열등의 사용이 금지되는 반면, 캐나다의 2025년 건축 기준에서는 최소 광속 효율 기준치가 상향 조정됩니다. 멕시코의 NOM-030-ENER 규격에서는 공공 건축물에 대한 LED 상당 기준치가 정해져 있습니다. 기준을 충족하지 못하는 제품의 카탈로그 라인업이 사라짐에 따라 판매업체들은 LED를 표준화하고 있으며, 의료 및 교육 분야에서는 건축 기준에 따른 LED로의 전환이 기본이 되고 있습니다.
LED 조명 기구의 가격 하락과 총 소유 비용(TCO)의 우위가 상업 분야에서의 도입을 가속화하고 있습니다.
LED 패키지 및 드라이버 전반에 걸친 급속한 비용 절감으로 인해 조명 기구의 초기 가격이 하락했으며, 많은 상업시설의 개보수 프로젝트에서 2년 미만의 투자 회수 기간을 정당화할 수 있게 되었습니다. 최신 트로퍼형 조명 기구는 형광등의 기준치보다 40% 높은 110 lm/W의 광속 효율을 실현함과 동시에 정격 수명을 약 85,000시간으로 연장했습니다. 이에 따라 유지보수 빈도가 비례하여 감소하여 시설 관리자의 운영 경비가 절감됩니다. 하이베이 조명의 LED 전환을 통해 물류 센터에서는 50-70%의 에너지 절감 효과가 기록되고 있으며, 대규모 시설에서는 연간 6자리 수의 에너지 비용 절감을 실현하고 있습니다. 미국 여러 주에서 시행되고 있는 전력 회사의 인센티브 덕분에 자본 비용이 추가로 10-15% 절감되어, 자금 조달 결정이 LED 도입 쪽으로 결정적으로 기울고 있습니다. 이러한 경제적 요인들이 맞물리면서, 예산에 제약이 있는 부동산 소유주들에게도 투자 회수 계산이 설득력을 갖게 되어 북미 상업용 LED 조명 시장의 단기적인 성장세를 뒷받침하고 있습니다.
제품의 상품화가 진행되는 가운데, 각 제조업체는 경쟁력을 유지하기 위해 소프트웨어 제품의 규모 확대와 번들화를 점점 더 서두르고 있습니다. 이러한 동향은 가격 민감도와 표준화가 만연한 시장에서 제품을 차별화해야 할 필요성에 의해 주도되고 있습니다. 한편, 소규모 유통업체은 최종 사용자에게 편의성과 비용 절감을 제공하는 ‘시공업체 대상 직접 가격 책정’을 실시하는 온라인 경쟁사들로부터 문제에 직면해 있습니다. 이러한 추세로 인해 소규모 사업자들이 수익성과 시장 점유율 유지에 고전하는 가운데, 업계 내 통합의 물결이 가속화되고 있습니다. 이러한 추세의 대표적인 사례로 시그니파이(Signify)를 들 수 있습니다. 이 회사의 이익률 하락은 업계 전체가 직면한 압박이 커지고 있음을 여실히 보여주며, 변화하는 시장 역학 속에서 수익성을 유지해야 하는 광범위한 과제를 반영하고 있습니다.
부문 분석
농업 및 원예 분야의 설치 건수는 수직 농장을 지원하는 스펙트럼 조절형 조명 기구의 혜택을 받아 연평균 성장률(CAGR) 14.89%로 가장 빠른 성장이 예상됩니다. 이 틈새 시장에서는 이미 LED 보급률이 66%에 달하지만, 보조 조명을 갖춘 온실 시장은 여전히 거의 개척되지 않은 상태입니다. 사무실 분야의 설치 건수는 2025년 매출의 27.43%를 차지할 것으로 예상되지만, 하이브리드 근무 방식의 확산으로 인해 직원 밀도가 낮아지면서 성장세가 둔화되고 있습니다. 의료 및 소매 분야에서는 각각 환자의 쾌적함과 상품 진열을 목적으로 고연색성(CRI) 조명 기구가 채택되고 있습니다. 산업용 창고에서는 1와트당 180루멘을 초과하는 고천장용 LED가 채택되고 있으며, 교육 시설에서는 ASHRAE 90.1 규격을 충족하기 위해 자연광 활용이 우선시되고 있습니다.
건축 파사드 등 틈새 시장에서는 3D 프린팅된 금속 광학 시스템에 프리미엄 가격이 책정되고 있습니다. 하류 시장에서는 북미 상업용 LED 조명 시장에서 수직 농업 시장 규모가 급속히 확대될 것으로 예상되는 반면, 2031년까지는 사무실 분야가 북미 상업용 LED 조명 시장에서 최대 점유율을 유지할 것으로 전망됩니다.
트랙 조명은 광속의 유연성과 색 재현성이 필요한 박물관 및 소매업체에 힘입어 연평균 성장률(CAGR) 14.94%를 기록할 전망입니다. 2025년 매출의 23.17%를 차지할 트로퍼의 경우, 대규모 교체 수요가 지속될 것으로 보이지만 가격 상승 여지는 제한적입니다. 냉장 창고용 고천장 조명 기구는 10만 루멘을 초과하며, 다운라이트는 천장의 균일성을 확보하기 위해 색 분포의 허용 범위를 맥아담 타원의 절반으로 좁히고 있습니다. 리니어 스트립이나 매달기식 시스템은 연속적인 라인을 통해 미적 아름다움을 제공합니다.
따라서 북미 상업용 LED 조명 시장에서 트랙 조명 시장 규모는 확대되는 한편, 설치 대수 기준으로는 트로퍼가 계속해서 가장 큰 시장 점유율을 유지하게 될 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the North America commercial LED lighting market size is projected to expand from USD 8.58 billion in 2025 and USD 10.03 billion in 2026 to USD 19.72 billion by 2031, registering a CAGR of 14.48% between 2026 and 2031.
This report is Segmented by Application (Retail Stores, Office, Hospitality, Architectural, Healthcare Facilities, Educational Institutions, Industrial and Warehouse, and More), Form Factor (Troffers, and More), Distribution Channel (Direct Sales, and More), Installation Type (New Construction, and Retrofit), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
North America Commercial LED Lighting Market Trends and Insights
Stringent Energy-Efficiency Regulations and Building Codes
New federal and provincial standards eliminate most legacy lamps, so owners replace fluorescents even when payback modelling is incomplete. U.S. rules finalized in 2024 ban halogen and incandescent options, while Canada's 2025 code lifts minimum efficacy thresholds. Mexico's NOM-030-ENER sets LED-equivalent baselines in public buildings. As catalogue lines for non-compliant products disappear, distributors standardize on LEDs, making code-driven conversions the default in healthcare and education.
Declining LED Luminaire Prices and Total-Cost-of-Ownership Advantage Accelerate Commercial Adoption
Rapid cost compression across LED packages and drivers lowers upfront fixture prices, enabling projects to justify payback periods shorter than two years in many commercial retrofits. Contemporary troffer designs deliver 110 lm/W efficacy 40% higher than fluorescent references, while extending rated life to roughly 85,000 hours; maintenance cycles drop proportionally, cutting operating expenses for facility managers. High-bay conversions record energy savings of 50-70% in distribution centers, generating six-figure annual utility reductions in large venues. Utility incentives across multiple U.S. states further shave 10-15% from capital costs, tipping financing decisions decisively toward LED. Together, these economic levers reinforce the North America Commercial LED Lighting market's momentum in the short term as payback math becomes compelling even for budget-constrained property owners.
As package commoditization intensifies, manufacturers are increasingly compelled to either scale up or bundle their software offerings to remain competitive. This trend is driven by the need to differentiate products in a market where price sensitivity and standardization are prevalent. Meanwhile, smaller distributors face mounting challenges from online competitors who provide direct-to-contractor pricing, offering convenience and cost savings to end users. This dynamic is accelerating a wave of consolidation within the industry, as smaller players struggle to maintain profitability and market share. A notable instance of this trend is Signify, whose declining margins highlight the growing pressures faced across the sector, reflecting the broader challenges of maintaining profitability amidst shifting market dynamics.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Smart, Connected, and IoT-Enabled Lighting Creates New Value Propositions
- Shift Toward Human-Centric and Wellness-Focused Lighting Drives Premium Segment Growth
- Price Erosion Squeezing Vendor Margins Intensifies Competitive Pressure
- High Retrofit and Installation Costs in Legacy Facilities Limit Market Penetration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Agricultural and horticulture installations are forecast to grow fastest at a 14.89% CAGR, benefiting from spectrum-tuned fixtures that support vertical farms. This niche already shows 66% LED penetration, yet supplemented greenhouses remain largely untapped. Office installations, although holding 27.43% of 2025 revenue, slow as hybrid work reduces density. Healthcare and retail adopt high-CRI fixtures for patient comfort and merchandising, respectively. Industrial warehouses adopt high-bay LEDs topping 180 lumens per watt, while educational sites prioritize daylight harvesting to satisfy ASHRAE 90.1.
Niche segments such as architectural facades command premium rates for 3D-printed metal optics. Downstream, the North America commercial LED lighting market size for vertical farming is projected to rise rapidly, while offices maintain the largest North America commercial LED lighting market share through 2031.
Track lights are set to post a 14.94% CAGR, propelled by museums and retailers needing beam flexibility and colour fidelity. Troffers, with 23.17% of 2025 revenue, continue large-scale replacements but see limited price upside. High-bay fixtures exceed 100,000 lumens for cold-storage; downlights tighten colour bins to half a MacAdam ellipse for uniform ceilings. Linear strips and suspended systems provide continuous-line aesthetics.
The North America commercial LED lighting market size for track lights will therefore widen, while troffers keep the highest North America commercial LED lighting market share based on installed base.
Complete Report Scope:
- By Application
- Retail Stores (Showrooms, Malls, Shops)
- Office
- Hospitality (Restaurants, Casinos, Hotels)
- Architectural (Decorative)
- Healthcare Facilities
- Educational Institutions
- Industrial and Warehouse
- Outdoor Commercial (Parking, Facades)
- Agricultural and Horticulture (Vertical Farm)
- By Form Factor
- Troffers
- Downlights
- High-Bay
- Track Lights
- Suspended Pendants
- Panel Lights
- Linear Strips
- Flood and Area Lights
- Other Form Factors
- By Distribution Channel
- Direct Sales
- Retail / Wholesale
- ESCO / Lighting-as-a-Service Providers
- Online / E-Commerce
- By Installation Type
- New Construction
- Retrofit
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Signify Holding
- Acuity Brands Inc.
- Hubbell Inc.
- Cree Lighting
- Dialight plc
- US LED Ltd.
- Osram Licht AG
- Technical Consumer Products Inc.
- Current Lighting Solutions LLC
- Zumtobel Group
- Lutron Electronics Co. Inc.
- Legrand SA
- Leviton Manufacturing Co. Inc.
- Samsung Electronics America
- LG Innotek USA Inc.
- Nichia America Corp.
- Orion Energy Systems Inc.
- Energy Focus Inc.
- Digital Lumens Inc.
- Fagerhult Group
- Revolution Lighting Technologies
- Cooper Lighting Solutions
- Lumileds Holding BV
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Value-Chain Analysis
- 4.3 Regulatory Landscape
- 4.4 Technological Outlook
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Market Drivers
- 4.6.1 Stringent Energy-Efficiency Regulations and Building Codes
- 4.6.2 Declining LED Luminaire Prices and Total Cost-of-Ownership Advantage
- 4.6.3 Growth of Smart, Connected and IoT-Enabled Lighting Systems
- 4.6.4 Shift Toward Human-Centric and Wellness-Focused Lighting in Workplaces
- 4.6.5 Corporate Net-Zero and ESG Targets Accelerating Retrofit Demand
- 4.6.6 Demand from Indoor Vertical Farming and Micro-Fulfillment Centers
- 4.6.7 Emergence of Utility Incentive Programs Targeting Mid-Size Businesses
- 4.6.8 Microgrid and On-Site Renewable Integration Favoring DC-Powered LED Systems
- 4.7 Market Restraints
- 4.7.1 Price Erosion Squeezing Vendor Margins
- 4.7.2 High Retrofit and Installation Costs in Legacy Facilities
- 4.7.3 Critical Component Shortages (Phosphors, Drivers, ICs)
- 4.7.4 Competition from OLED and Micro-LED Illumination Panels
- 4.7.5 Complexity of Lighting Controls Interoperability Standards
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Retail Stores (Showrooms, Malls, Shops)
- 5.1.2 Office
- 5.1.3 Hospitality (Restaurants, Casinos, Hotels)
- 5.1.4 Architectural (Decorative)
- 5.1.5 Healthcare Facilities
- 5.1.6 Educational Institutions
- 5.1.7 Industrial and Warehouse
- 5.1.8 Outdoor Commercial (Parking, Facades)
- 5.1.9 Agricultural and Horticulture (Vertical Farm)
- 5.2 By Form Factor
- 5.2.1 Troffers
- 5.2.2 Downlights
- 5.2.3 High-Bay
- 5.2.4 Track Lights
- 5.2.5 Suspended Pendants
- 5.2.6 Panel Lights
- 5.2.7 Linear Strips
- 5.2.8 Flood and Area Lights
- 5.2.9 Other Form Factors
- 5.3 By Distribution Channel
- 5.3.1 Direct Sales
- 5.3.2 Retail / Wholesale
- 5.3.3 ESCO / Lighting-as-a-Service Providers
- 5.3.4 Online / E-Commerce
- 5.4 By Installation Type
- 5.4.1 New Construction
- 5.4.2 Retrofit
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Signify Holding
- 6.4.2 Acuity Brands Inc.
- 6.4.3 Hubbell Inc.
- 6.4.4 Cree Lighting
- 6.4.5 Dialight plc
- 6.4.6 US LED Ltd.
- 6.4.7 Osram Licht AG
- 6.4.8 Technical Consumer Products Inc.
- 6.4.9 Current Lighting Solutions LLC
- 6.4.10 Zumtobel Group
- 6.4.11 Lutron Electronics Co. Inc.
- 6.4.12 Legrand SA
- 6.4.13 Leviton Manufacturing Co. Inc.
- 6.4.14 Samsung Electronics America
- 6.4.15 LG Innotek USA Inc.
- 6.4.16 Nichia America Corp.
- 6.4.17 Orion Energy Systems Inc.
- 6.4.18 Energy Focus Inc.
- 6.4.19 Digital Lumens Inc.
- 6.4.20 Fagerhult Group
- 6.4.21 Revolution Lighting Technologies
- 6.4.22 Cooper Lighting Solutions
- 6.4.23 Lumileds Holding BV
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment