

|
시장보고서
상품코드
2124106
전류 센서 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Current Sensor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
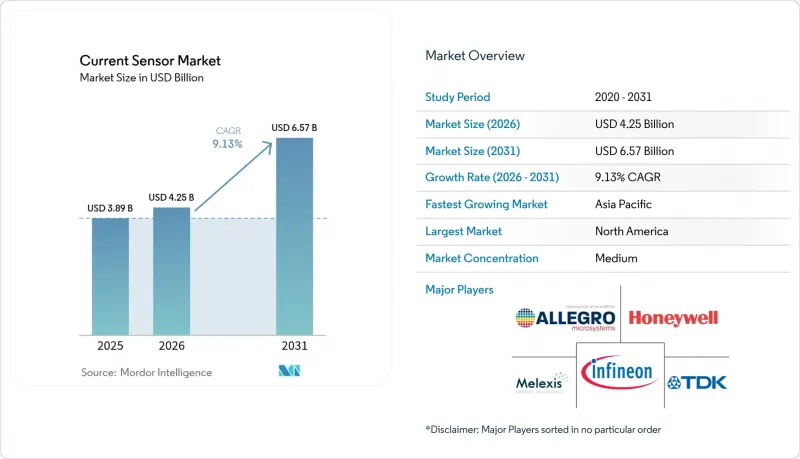
에 의하면, 전류 센서 시장 규모는 2025년 38억 9,000만 달러에서 2026년에는 42억 5,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 9.13%로 성장을 지속하여, 2031년에는 65억 7,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 센서 유형(홀 효과 센서, 광섬유 전류 센서, 유도형/CT 센서 등), 절연 기술(오픈 루프 절연 등), 전류 범위(600A), 최종 사용자 산업(자동차 및 운송, 산업용 자동화·로봇 공학, 에너지 및 전력 등) 및 지역별로 분류되어 있습니다.
세계 전류 센서 시장 동향 및 인사이트
배터리 구동 시스템 및 재생에너지 시스템의 보급
유틸리티 규모의 태양광 발전 및 에너지 저장 프로젝트에는 DC 컴바이너 박스, 인버터 입력, 계통 연계 링크 등 여러 모니터링 지점이 설치되어 있어, 메가와트당 센서 수요에 시너지 효과를 가져오고 있습니다. 양방향 V2G(Vehicle-to-Grid) 인터페이스에서는 충방전 전류 측정 시 1% 미만의 정확도가 요구되어, 기존의 홀 효과 소자에 대한 압박이 커지는 한편, 전자기 내성이 뛰어난 광섬유 센서의 채택이 촉진되고 있습니다. 아시아태평양에서는 재생에너지 도입 의무와 전기차 구매 장려책이 결합되어 자동차, 산업, 전력망 각 시장의 센서 수요가 시너지 효과를 내며 증가했습니다. 또한, 분산형 에너지 시스템 도입에 있어서는 기존 설비의 정확도 확인을 위해 비침습형 로고스키 코일이 선호되어 채택되었습니다. 시스템 통합사업자들은 점점 더 디지털 인터페이스를 지정하게 되었으며, 현장 데이터가 예측 유지보수 플랫폼에 직접 통합되게 되었습니다.
EV의 전동화 및 ADAS 통합 가속화
고급 전기차는 800V 아키텍처로 전환되면서, 센서는 마이크로초 단위의 응답 시간을 실현하면서도 5kV 이상의 절연 내력을 유지해야 했습니다. 단 한 대의 배터리식 전기차만 해도 트랙션 인버터, 배터리 관리 시스템(BMS), 열 루프에 걸쳐 최대 50곳의 전류 측정 지점이 필요했습니다. 스티어 바이 와이어 및 Brake-by-wire 모듈에 탑재된 ADAS 액추에이터에는 ISO 26262 준수를 위해 중복 감지 채널이 추가되었습니다. TMR 솔루션은 뛰어난 온도 안정성과 낮은 정지 전류로 시장 점유율을 확대했으며, Allegro MicroSystems와 같은 공급업체들이 파워트레인 및 섀시 분야에서 기존의 홀 효과 소자를 대체하는 입지를 확립했습니다. 100kHz 이상에서 스위칭을 수행하는 SiC 인버터는 기존 전류 변압기가 대응할 수 있는 대역폭의 한계를 넘어, 파워 모듈 내 통합형 센싱 기술에 대한 투자를 촉진했습니다.
홀 효과 센서의 평균 판매 가격 하락
중국의 팹이 범용 자동차용 등급 시장에 대량으로 공급함에 따라, 매출 총이익률이 압박을 받게 되었고, 기존 공급업체 간의 통합이 촉발되었습니다. Tier 1 통합업체들은 수량 할인을 받기 위해 조달을 일원화함으로써, 엔트리 레벨 홀 효과 센서 분야의 ‘최저가 경쟁’ 추세를 가속화했습니다. 각 벤더는 시스템 인 패키지(SiP)의 기능(진단 기능 및 디지털 인터페이스 등)을 통해 차별화를 꾀했으나, 가격 차이는 여전히 확대되었습니다. 많은 틈새 시장 제조업체들은 TMR 및 광섬유 제품군으로의 전환을 모색했으나, 막대한 연구개발 투자와 장기간에 걸친 자동차용 인증 절차가 중소기업 시장 진입을 가로막았습니다. 통합 모듈 전략은 파워 스테이지 내에 센서와 MCU를 통한 모니터링 기능을 통합함으로써 가격 압박에 부분적으로 대응하고, OEM의 가치 중심 조달 모델과 일관성을 추구했습니다.
부문 분석
홀 효과 소자는 성숙한 생산 라인과 트랙션 인버터 및 산업용 드라이브에서 입증된 신뢰성 덕분에 2025년에는 매출의 47.55%를 차지했습니다. 그러나 대역폭의 상한선과 열 드리프트가 요인이 되어 설계자들은 TMR 및 광섬유 옵션으로 전환해 나갔습니다. 광섬유 센서는 재생에너지 설치 업체들이 고전압 개폐소에서 갈바닉 절연이 없는 측정을 지정함에 따라 2026년부터 2031년까지 연평균 성장률(CAGR) 12.21%를 기록했습니다. TMR은 기존 홀 효과 센서에 비해 10배의 감도를 실현하여, BMS 션트의 대체품에서 낮은 저항 손실을 가능하게 하고, 배터리 팩의 대기 전력을 절감했습니다.
첨단 EV용 인버터에는 1 MHz 대역폭 목표를 충족하는 순간 위상 전류 피드백을 구현하기 위해 코패키징된 TMR 다이가 통합되었습니다. HVDC의 확장에 따라 광섬유식 전류 센서 시장 규모는 2031년까지 10억 1,200만 달러에 달할 것으로 예측됩니다. 1,000 A를 초과하는 전류 범위에서는 유도형 CT가 여전히 일정한 점유율을 유지하고 있는 반면, 로고스키 코일은 도체를 절단하지 않고도 기존 설비의 개조 감사에 대응했습니다. 전력 밀도 로드맵에서 좁은 모듈 설치 면적에 적합한 비포화형 및 얇은 옵션에 대한 수요가 증가함에 따라 이러한 전환은 가속화되었습니다.
오픈 루프 아키텍처가 56.58%의 점유율을 차지하며, 400V EV 팩 및 600V 태양광 발전용 인버터에서 비용과 안전성의 균형을 실현했습니다. 폐루프 방식의 장치는 자기 피드백을 활용하여 ±0.5%의 정확도를 실현했으며, 설계자들이 효율 지표를 개선함에 따라 연평균 성장률(CAGR) 11.12%를 기록했습니다. 이러한 센서는 차량용 충전기 및 서보 드라이브에서 주변 온도로 인한 드리프트를 상쇄하여, 규제 당국이 유럽의 에코디자인 기준을 충족하도록 보장했습니다. 폐쇄 루프 방식 전류 센서 시장 점유율은 2031년까지 41.05%로 상승할 것으로 예측됩니다.
비절연형 션트 센서는 갈바닉 절연이 필수적이지 않았던 신흥 48V 마일드 하이브리드 플랫폼에서 널리 보급되었습니다. 그러나 팩 레벨 전압이 60V에 가까워짐에 따라 그 적용 범위가 위협받게 되었고, 공급업체들은 하이브리드 패키지 내에서 션트와 디지털 아이솔레이터를 결합하기 시작했습니다. 아날로그 프론트엔드, 시그마-델타 변환기 및 절연 채널을 단일 IC로 통합함으로써 BOM 비용이 재검토되고, PCB 면적이 축소되며, 폐쇄 루프 방식의 가치 제안이 강화되었습니다.
지역별 분석
2025년에는 중국이 전기차 생산 규모를 확대하고 반도체 패키징 역량에서 압도적인 우위를 유지함에 따라, 아시아태평양이 매출의 46.27%를 차지하며 1위를 차지했습니다. 각국 정부가 재생에너지에 자금을 지원함에 따라, 국내 광섬유 센서 스타트업 기업의 등장이 촉진되었습니다. 일본은 정밀 제조의 전통을 살려 첨단 TMR 제품의 상용화를 추진한 반면, 한국은 SiC 파워 모듈 수출 라인에 전류 감지 기능을 통합했습니다.
북미는 2위를 차지했습니다. 하이퍼스케일 데이터센터에 대한 투자와 청정 에너지 프로젝트에 대한 ‘인플레이션 감축법(IRA)’의 인센티브가 센서 조달을 뒷받침했습니다. 미국의 리쇼어링(국내 복귀) 프로그램은 전력망 인프라 및 방위 분야를 위한 안전상 중요한 부품의 현지 제조를 촉진했습니다. 캐나다가 추진하는 배터리용 원자재 자급자족 노력은 광업의 전기화와 관련된 지역의 센서 수요를 뒷받침했습니다.
유럽에서는 엄격한 CO2 배출 목표와 기능 안전 요건이 추구되면서, 자동차용 폐쇄 루프(closed-loop) 장치의 평균 판매 가격(ASP)이 높은 수준을 유지했습니다. 독일과 프랑스에는 센서 설계와 GaN 인버터 관련 스타트업 기업을 연결하는 주요 연구개발 거점이 설립되었습니다. 중동 및 아프리카에서는 태양광 발전 단지 투자를 통해 새로운 수요가 기록된 반면, 라틴아메리카의 성장은 멕시코와 브라질의 자동차 조립 클러스터에 의해 주도되었습니다. 각 지역에서 전류 센서 시장 규모는 배터리 생산 거점의 확대 및 재생에너지에 대한 설비 투자와 연동하여 추이를 보였습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 세분화
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the current sensor market size is expected to grow from USD 3.89 billion in 2025 to USD 4.25 billion in 2026 and is forecast to reach USD 6.57 billion by 2031 at 9.13% CAGR over 2026-2031.
This report is Segmented by Sensor Type (Hall-Effect Sensors, Fiber-Optic Current Sensors, Inductive/CT Sensors, and More), Isolation Technology (Open-Loop Isolated, and More), Current Range (600A), End-User Industry (Automotive and Transportation, Industrial Automation and Robotics, Energy and Power, and More), and Geography
Global Current Sensor Market Trends and Insights
Proliferation of Battery-Powered and Renewable-Energy Systems
Utility-scale solar and storage projects installed multiple monitoring points-DC combiner boxes, inverter inputs, and grid-tie links-creating a multiplier effect on sensor demand per megawatt. Bidirectional vehicle-to-grid (V2G) interfaces required sub-1% accuracy when measuring charge and discharge currents, pressuring traditional Hall-effect devices and boosting fiber-optic adoption for their electromagnetic immunity. Asia-Pacific installations paired renewable-energy mandates with EV incentives, compounding sensor demand across automotive, industrial, and grid markets. Distributed-energy deployments also favored non-intrusive Rogowski coils for retrofit accuracy checks. Integrators increasingly specified digital interfaces, so field data fed directly into predictive-maintenance platforms.
Acceleration of EV Electrification and ADAS Integration
Premium EVs migrated to 800 V architectures, compelling sensors to sustain >=5 kV isolation while delivering microsecond response times. A single battery-electric vehicle already required up to 50 current measurement points spanning traction inverters, battery-management systems (BMS), and thermal loops. ADAS actuators in steer-by-wire and brake-by-wire modules added redundant sensing channels for ISO 26262 compliance. TMR solutions gained share through superior temperature stability and lower quiescent current, positioning suppliers like Allegro MicroSystems to replace legacy Hall-effect parts in powertrain and chassis domains. SiC inverters, switching above 100 kHz, stretched bandwidth expectations beyond conventional current transformers, spurring investment in integrated sensing within power modules.
Average-Selling-Price Erosion in Hall-Effect Sensors
Chinese fabs flooded commodity automotive grades, squeezing gross margins and triggering consolidation among incumbent suppliers. Tier-1 integrators centralized procurement to extract volume discounts, accelerating a race-to-bottom dynamic in the entry-level Hall-effect tier. Vendors attempted to differentiate through system-in-package features-diagnostics or digital interfaces-but price gaps still widened. Many niche manufacturers pivoted toward TMR or fiber-optic portfolios; however, the steep R&D commitment and lengthy automotive qualification deterred smaller firms. Integrated module strategies partly countered price pressure by bundling sensor plus MCU supervision within power stages, aligning with OEM value-based sourcing models.
Other drivers and restraints analyzed in the detailed report include:
- Functional-Safety Mandates (ISO 26262, IEC 61508)
- High-Frequency GaN/SiC Power-Electronics Miniaturization
- Supply-Chain Tightness for High-Permeability Core Alloys
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hall-effect devices captured 47.55% revenue in 2025 due to mature production lines and proven reliability across traction inverters and industrial drives. Yet their bandwidth ceiling and thermal drift propelled designers toward TMR and fiber-optic options. Fiber-optic sensors recorded a 12.21% CAGR for 2026-2031 as renewable-energy installers specified galvanic-free measurement in high-voltage switchyards. TMR delivered 10X sensitivity over legacy Hall-effect, enabling low-ohmic drop in BMS shunt replacements and cutting standby power in battery packs.
Advanced EV inverters integrated a co-packaged TMR die for instantaneous phase-current feedback that met 1 MHz bandwidth targets. The current sensor market size for fibre-optic devices is forecast to reach USD 1,012 million by 2031 amid HVDC expansion. Inductive CTs retained a foothold above 1,000 A, while Rogowski coils addressed retrofit audits without interrupting conductors. The transition accelerated as power-density roadmaps demanded non-saturating, low-profile options suitable for tight module footprints.
Open-loop architectures dominated with 56.58% share, balancing cost and safety for 400 V EV packs and 600 V solar inverters. Closed-loop devices-leveraging magnetic feedback for +-0.5% accuracy-posted an 11.12% CAGR as designers sharpened efficiency metrics. These sensors offset ambient temperature drift in onboard chargers and servo drives, ensuring regulators met eco-design standards in Europe. Current sensor market share for closed-loop options is expected to climb toward 41.05% by 2031.
Non-isolated shunt sensors thrived in emerging 48 V mild-hybrid platforms where galvanic isolation was non-mandatory. However, pack-level voltages creeping toward 60 V threatened their addressable window, inciting suppliers to pair shunts with digital isolators in hybrid packages. The convergence of analog front-end, sigma-delta converter, and isolation channel in a single IC redefined BOM costs and shrank PCB real estate, strengthening the closed-loop value proposition.
Complete Report Scope:
- By Sensor Type
- Hall-Effect Sensors
- Fiber-Optic Current Sensors
- Inductive / CT Sensors
- Fluxgate Sensors
- Rogowski-Coil Sensors
- By Isolation Technology
- Open-Loop (Isolated)
- Closed-Loop (Isolated)
- Non-Isolated (Shunt-based)
- By Current Range
- <50 A
- 50 - 200 A
- 200 - 600 A
- >600 A
- By End-User Industry
- Automotive and Transportation
- Industrial Automation and Robotics
- Energy and Power (Solar, Wind, ESS)
- Consumer Electronics
- Telecom and Data-Centers
- Medical Devices
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- ASEAN
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific led with 46.27% revenue in 2025 because China scaled EV output and maintained dominant semiconductor packaging capacity. Governments funded renewables, prompting domestic fiber-optic sensor startups to emerge. Japan leveraged precision-manufacturing heritage to commercialize advanced TMR products, while South Korea integrated current sensing in SiC power-module export lines.
North America ranked second. Hyperscale data-center spending and Inflation Reduction Act incentives for clean-energy projects spurred sensor procurement. United States reshoring programs favored local fabrication of safety-critical components destined for grid infrastructure and defense. Canada's push for battery-raw-material autonomy underpinned regional sensor demand tied to mining electrification.
Europe pursued stringent CO2 targets and functional-safety mandates, sustaining high ASPs for automotive-grade closed-loop devices. Germany and France hosted key R&D hubs linking sensor design with GaN inverter start-ups. The Middle East and Africa recorded emerging demand via solar-park investments, whereas Latin America's growth followed automotive assembly clusters in Mexico and Brazil. Across regions, the current sensor market size co-moved with battery manufacturing footprints and renewable-energy capex.
- Allegro MicroSystems Inc.
- TDK Corporation (TDK-Micronas GmbH)
- Asahi Kasei Microdevices Corp.
- Infineon Technologies AG
- Tamura Corporation
- Melexis NV
- Honeywell International Inc.
- Texas Instruments Inc.
- Sensitec GmbH
- LEM International SA
- Pulse Electronics Corp.
- ACEINNA Inc.
- Vacuumschmelze GmbH & Co KG
- MagnTek Microelectronics Co. Ltd.
- NewJapanRadio Co. Ltd.
- Murata Manufacturing Co. Ltd.
- Onsemi Corp.
- ROHM Semiconductor Co. Ltd.
- Sensata Technologies Inc.
- NK Technologies
- ABB Ltd.
- CR Magnetics Inc.
- Eaton Corp. plc
- LEMKEN AG
- Topworx Inc.
- Schneider Electric SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of battery-powered and renewable energy systems
- 4.2.2 Acceleration of EV electrification and ADAS integration
- 4.2.3 Functional-safety mandates (ISO 26262, IEC 61508)
- 4.2.4 Surge in bidirectional on-board charger (V2G) deployments
- 4.2.5 High-frequency GaN/SiC power-electronics miniaturization
- 4.2.6 Data-center power monitoring for AI workloads
- 4.3 Market Restraints
- 4.3.1 Average-selling-price erosion in Hall-effect sensors
- 4.3.2 Accuracy drift vs. shunt / CT alternatives
- 4.3.3 Supply-chain tightness for high-permeability core alloys
- 4.3.4 Cyber-security compliance costs in smart-grid metering
- 4.4 Evaluation of Critical Regulatory Framework
- 4.5 Value Chain Analysis
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact Assessment of Key Stakeholders
- 4.9 Key Use Cases and Case Studies
- 4.10 Impact on Macroeconomic Factors of the Market
- 4.11 Investment Analysis
5 MARKET SEGMENTATION
- 5.1 By Sensor Type
- 5.1.1 Hall-Effect Sensors
- 5.1.2 Fiber-Optic Current Sensors
- 5.1.3 Inductive / CT Sensors
- 5.1.4 Fluxgate Sensors
- 5.1.5 Rogowski-Coil Sensors
- 5.2 By Isolation Technology
- 5.2.1 Open-Loop (Isolated)
- 5.2.2 Closed-Loop (Isolated)
- 5.2.3 Non-Isolated (Shunt-based)
- 5.3 By Current Range
- 5.3.1 <50 A
- 5.3.2 50 - 200 A
- 5.3.3 200 - 600 A
- 5.3.4 >600 A
- 5.4 By End-User Industry
- 5.4.1 Automotive and Transportation
- 5.4.2 Industrial Automation and Robotics
- 5.4.3 Energy and Power (Solar, Wind, ESS)
- 5.4.4 Consumer Electronics
- 5.4.5 Telecom and Data-Centers
- 5.4.6 Medical Devices
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Allegro MicroSystems Inc.
- 6.4.2 TDK Corporation (TDK-Micronas GmbH)
- 6.4.3 Asahi Kasei Microdevices Corp.
- 6.4.4 Infineon Technologies AG
- 6.4.5 Tamura Corporation
- 6.4.6 Melexis NV
- 6.4.7 Honeywell International Inc.
- 6.4.8 Texas Instruments Inc.
- 6.4.9 Sensitec GmbH
- 6.4.10 LEM International SA
- 6.4.11 Pulse Electronics Corp.
- 6.4.12 ACEINNA Inc.
- 6.4.13 Vacuumschmelze GmbH & Co KG
- 6.4.14 MagnTek Microelectronics Co. Ltd.
- 6.4.15 NewJapanRadio Co. Ltd.
- 6.4.16 Murata Manufacturing Co. Ltd.
- 6.4.17 Onsemi Corp.
- 6.4.18 ROHM Semiconductor Co. Ltd.
- 6.4.19 Sensata Technologies Inc.
- 6.4.20 NK Technologies
- 6.4.21 ABB Ltd.
- 6.4.22 CR Magnetics Inc.
- 6.4.23 Eaton Corp. plc
- 6.4.24 LEMKEN AG
- 6.4.25 Topworx Inc.
- 6.4.26 Schneider Electric SE
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


