|
시장보고서
상품코드
2124201
조선 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Shipbuilding - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 조선 시장 규모는 2025년에 1,572억 1,000만 달러로 평가되었고, 2026년 1,644억 7,000만 달러에서 2031년까지 2,062억 4,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.62%를 나타낼 전망입니다.
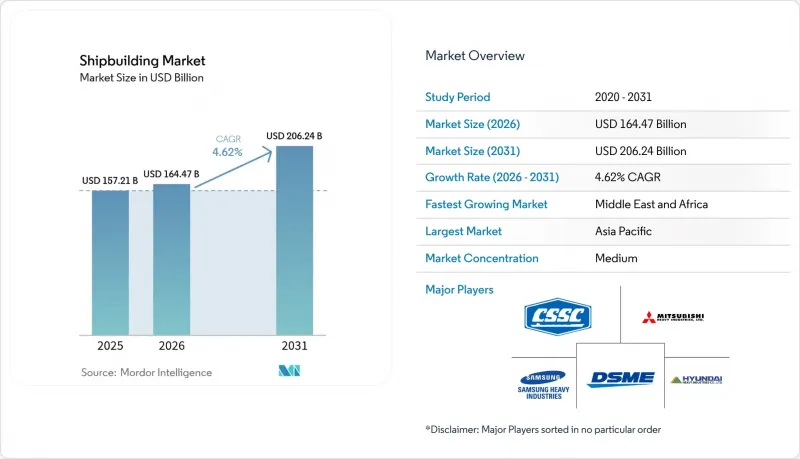
본 보고서는 선박 유형별(벌크선, 유조선, 기타), 추진 기술별(기존, 듀얼 연료 LNG, 기타), 최종 사용자별(상선사, 해양 에너지 사업자, 기타), 소재별(강철, 알루미늄, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 조선 시장 동향 및 인사이트
전 세계 해상 무역량 증가
2024년에는 컨테이너 화물 운송량이 대폭 증가하여 컨테이너 선단의 가동 규모가 100만 TEU 확대됨에 따라 중국, 한국, 일본의 각 조선소에서 신규 수주가 증가했습니다. 홍해의 안보 위험에 대응하여 희망봉 주변의 우회 항로가 지속된 결과, 수에즈 운하를 경유하는 총 처리량은 5분의 4 이상 급감했지만, 톤마일 수요는 확대되었습니다. 항해 거리의 연장으로 인해 항만 혼잡에 따른 운항상의 지장이 있음에도 불구하고, 벌크선 및 더 크고 연료 효율이 높은 컨테이너선에 대한 수요는 유지되고 있습니다. 유럽이 미국에서 카타르 및 서아프리카로 LNG 조달처를 다각화하려는 움직임에 따라 대서양 무역 루트가 확대되고, 장거리 운송 수요가 더욱 높아지고 있습니다. 이러한 동향이 맞물려 2020년대 중반까지 조선 시장의 수주 전망에 호재가 되고 있습니다.
LNG 연료선 수요의 급증
아시아가 전력 및 중공업용으로 저탄소 원료를 찾는 가운데, 전 세계 LNG 소비량은 2040년까지 5분의 3 증가할 것으로 예측됩니다. 카타르 에너지(Qatar Energy)가 삼성중공업에 LNG 운반선 15척을 발주함에 따라, 삼성중공업의 LNG 수주 잔고는 86척에 달했습니다. 한편, 한화오션은 지금까지 180척을 인도했으며, 2025년 말까지 연간 생산 능력을 24척으로 확대할 계획입니다. 쉘(Shell)은 2030년까지 선박용 LNG 수요가 비약적으로 증가할 것이며, 듀얼 연료 추진이 과도기적 주류가 될 것이라는 전망을 제시했습니다. 지정학적 역풍으로 인해 화물의 목적지가 변경될 가능성은 있지만, 카타르의 생산 라인과 미국의 수출 터미널에서 나오는 막대한 공급량 덕분에 액화 사업의 성장이 장기적으로 확실시되고 있으며, 이는 조선 시장에 향후 수년간 수요 전망으로 이어집니다.
변동이 심한 철강·원자재 가격
2024년에는 중국산 철근 가격이 5분의 1 이상 하락했고, 철광석의 벤치마크 가격도 대폭 하락했습니다. 이로 인해 공급 과잉이 발생하여 전 세계 시세가 매주 변동하는 상황이 되고 있습니다. 열연 코일의 연간 평균 가격은 톤당 850달러였으나, 알루미늄 가격도 급등하고 있어 여전히 변동성이 심한 상황입니다. 20만 DWT급 벌크선 1척을 건조하는 데 최대 2만 톤의 강판이 사용되기 때문에 조선소의 이익률은 압박을 받고 있으며, 조선사는 수년에 걸친 건조 기간 동안 수천만 규모의 가격 변동 위험에 노출되어 있습니다. 인도 및 태국의 반덤핑 조치는 원자재 조달을 복잡하게 만들고 물류 비용을 상승시키고 있습니다. 그 결과, 일부 선주는 신규 계약 체결을 미루고 있어 조선 시장의 단기 수주량이 감소하고 있습니다.
부문별 분석
2025년, 벌크선은 조선 시장 점유율의 36.74%를 차지하며 조선 시장에서 가장 큰 비중을 차지했습니다. 규모의 경제, 저속 엔진, 스크러버 개조가 지속적인 수주의 기반이 되고 있습니다. 한편, 컨테이너선 부문은 공급 과잉으로 어려움을 겪고 있는 반면, 효율성 향상과 탈탄소화를 동시에 달성할 수 있는 대형 네오파나막스형 설계로의 전환을 추진하고 있습니다. 유조선 수요는 제재로 인한 무역 경로 변경의 영향을 받아 장거리 운송에 적합한 아프라막스형과 수에즈막스형 선박이 수요를 모았습니다.
오프쇼어 지원선은 전 세계 터빈 기초가 130미터 규모의 모노파일로 확대됨에 따라 2031년까지 연평균 성장률(CAGR) 4.71%라는 가장 높은 성장률을 보이고 있습니다. 중국은 매년 해양 분야 수주액이 견조하게 급증하고 있으며, 비용과 품질의 균형을 통해 유럽의 기존 대형 업체들로부터 시장 점유율을 빼앗고 있습니다. 해군의 수상 전투함은 기술적으로 복잡한 선체를 안정적으로 공급하며, 현금 흐름을 안정시키고 있습니다. 크루즈선 수주는 팬데믹 이후 회복되었으나, 선주들은 여전히 신중한 태도를 유지하며 LNG 듀얼 연료 및 메탄올 대응 선박에 주력하고 있습니다. 이러한 균형 잡힌 수주 구성이 경기 변동의 충격을 완화하여 조선 시장의 광범위한 수주 기반을 유지하고 있습니다.
2025년에도 기존 엔진이 조선 시장 점유율의 72.85%를 차지했습니다. 이는 벙커 연료 인프라가 전 세계적으로 잘 갖춰져 있고, 선원들이 이에 익숙하기 때문입니다. 쉘(Shell)사의 예측에 따르면, 2040년까지 해상 LNG 수요가 5분의 3 증가할 가능성이 있어 LNG 듀얼 연료의 도입이 가속화되고 있지만, 아프리카와 남미의 연료 네트워크 부족이 도입 지역 확대를 제약하고 있습니다. 하이브리드 전기 모듈은 비용보다 정위치 유지 정확도가 중시되는 해상 풍력 발전 및 조사선 부문에서 가장 먼저 도입될 예정입니다.
MAN ES나 WinGD 등의 엔진 제조업체들이 2025년 인도를 목표로 상용 모델을 검증하고 있는 만큼, 메탄올 및 암모니아 대응 계약은 연평균 성장률(CAGR) 4.86%로 증가하고 있습니다. 원자력 추진은 여전히 해군 전용이지만, 차세대 마이크로 원자로는 2035년 이후에 상업적 실현 가능성을 달성할 가능성이 있어 조선 시장에 새로운 전환의 계기를 가져올 것으로 보입니다.
지역별 분석
2025년, 아시아태평양은 조선 시장 점유율의 38.30%를 차지하며 조선 시장에서 그 매우 중요한 위치를 부각시켰습니다. 중국만으로도 전 세계 수주의 5분의 3을 확보했으며, 벌크선(벌크화물선)의 4분의 3을 인도했습니다. 낮은 인건비, 통합된 밸류체인, 방대한 국내 철강 기반 덕분에, 통화 강세를 고려하더라도 중국의 조선소는 비용 경쟁력을 유지하고 있습니다. 한국은 첨단 저장 기술을 통해 LNG 운반선 등 고부가가치 틈새 시장을 공략하며, 전 세계 가스운반선 생산량의 5분의 3 이상을 차지하고 있습니다. 인구 고령화로 인해 노동력이 제한되고 있음에도 불구하고, 일본은 품질을 중시하는 부문과 제로 배출 시범 프로젝트에서 점유율을 계속 유지하고 있습니다.
IEA.ORG에 따르면, 석유 및 가스 설비 투자가 에너지 물류 회랑으로 유입됨에 따라 중동 및 아프리카는 2031년까지 연평균 성장률(CAGR) 4.77%로 가장 높은 성장률을 나타낼 것으로 예측됩니다. 사우디아라비아와 아랍에미리트는 국내 조달률 기준에 따라 지역 내에서 건조해야 하는 대형 중량물 운반선 및 모듈 운반선 프로젝트를 발주하고 있습니다. 튀르키예는 홍해 정세의 불안정을 배경으로, 미국 수출업체와 유럽 구매자 간의 LNG 중계 거점으로 부상하고 있으며, 이에 따라 드라이독 및 신조선에 대한 투자가 촉진되고 있습니다. 북미에서는 존스법(Jones Act) 규정을 활용하여 고부가가치 설치선의 건조를 국내에서 유지하고 있으며, 미 해군의 30개년 계획이 여러 프로그램에 자금을 지원하는 기반이 되고 있습니다. 유럽의 조선소는 환경 규제에 대응하여 함대 갱신이 가속화되고 있지만, 철강 소비 부진과 거시경제적 역풍으로 인해 조선소의 가동률은 억제되고 있습니다. 그럼에도 불구하고 노르웨이와 덴마크는 메탄올 및 암모니아 추진 기술의 연구 개발을 주도하며, 조기 도입 고객이 되고 있는 고객을 확보하고 있습니다. 남미에서는 선택적인 성장이 나타나고 있으며, 브라질 해군이 주도하는 ‘ProSub’ 이니셔티브를 통해 잠수함 및 지원함 수주가 이루어지고 있습니다. 이러한 지역별 다양한 수요가 조선 시장 전반에 걸쳐 다양한 기회를 뒷받침하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the shipbuilding market size was valued at USD 157.21 billion in 2025 and estimated to grow from USD 164.47 billion in 2026 to reach USD 206.24 billion by 2031, at a CAGR of 4.62% during the forecast period (2026-2031).
This report is Segmented by Vessel Type (Bulk Carriers, Oil Tankers, and More), Propulsion Technology (Conventional, Dual-Fuel LNG, and More), End User (Commercial Shipping Companies, Offshore-Energy Operators, and More), Material (Steel, Aluminum, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Shipbuilding Market Trends and Insights
Rising Global Seaborne Trade Volumes
Containerized cargo rebounded sharply in 2024 as volumes grew significantly, lifting the active container fleet by 1 million TEU and underpinning fresh bookings across Chinese, Korean, and Japanese yards. Persistent rerouting around the Cape of Good Hope in response to Red Sea security risks expanded tonne-mile demand even though headline throughput via Suez plunged more than four-fifths. Higher voyage distances sustain demand for bulkers and larger, more fuel-efficient boxships despite operational hiccups linked to port congestion. Europe's push to diversify LNG away from the United States toward Qatar and West Africa widens Atlantic trade lanes, reinforcing the long-haul requirement. These dynamics collectively add positive torque to the shipbuilding market pipeline through mid-decade.
Surge in Demand for LNG-Fuelled Carriers
Global LNG consumption is projected to climb by three-fifths by 2040 as Asia seeks lower-carbon feedstock for power and heavy industry. QatarEnergy's purchase of 15 LNG carriers at Samsung Heavy Industries pushed the builder's LNG backlog to 86 ships. At the same time, Hanwha Ocean has delivered 180 vessels to date and plans to raise annual throughput to 24 hulls by 2025 end. Shell expects marine LNG demand to increase exponentially by 2030, making dual-fuel propulsion the dominant transitional choice. Although geopolitical headwinds could redirect cargoes, the sheer supply of Qatari trains and U.S. export terminals locks in an extended wave of liquefaction growth, translating into multiyear visibility for the shipbuilding market.
Volatile Steel and Raw-Material Prices
Chinese rebar fell more than one-fifth, and iron-ore benchmarks dropped drastically in 2024, creating gluts that swing global quotes weekly. Hot-rolled coil averaged USD 850 per ton during the year, while aluminum prices have also spiked and remain volatile. Yard profit margins tighten because a single 200,000-dwt bulker uses up to 20,000 tons of plate, exposing builders to tens of millions in price swings during multiyear build slots. Anti-dumping measures in India and Thailand complicate raw-material sourcing and elevate logistics costs. Consequently, some owners delay signing new contracts, compressing near-term intake for the shipbuilding market.
Other drivers and restraints analyzed in the detailed report include:
- Naval Fleet Modernisation Programmes
- Decarbonisation Mandates Driving Alt-Fuel Orders
- Global Yard Over-Capacity in the Bulk Segment
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bulk Carriers represented 36.74% of the shipbuilding market share in 2025, translating into the single-largest stake of the shipbuilding market. Economies of scale, low-speed engines, and scrubber retrofits underpin ongoing ordering. Meanwhile, container segments fight overcapacity yet pivot to larger neo-Panamax designs that can twin efficiency gains with decarbonisation pathways. Tanker demand swung on sanction-driven trade re-routing, which favored long-haul Aframax and Suezmax tonnage.
Offshore Support Vessels deliver the fastest 4.71% CAGR to 2031 as global turbine foundations scale up to 130-meter monopiles. China logged a robust spike in offshore order books yearly, gaining share against European incumbents through cost-quality parity. Naval surface combatants contribute a steady stream of technically complex hulls that stabilize cash flows. Cruise bookings improved post-pandemic, yet owners remain measured, focusing on LNG dual-fuel and methanol-ready tonnage. This balanced spread cushions cyclicality, sustaining a broad volume base for the shipbuilding market.
Conventional engines still powered 72.85% of the shipbuilding market share in 2025 because bunker fuel infrastructure is globally available, and crew familiarity is high. Dual-fuel LNG uptake accelerates under Shell's projection that seaborne demand could jump three-fifths by 2040, yet fuel network gaps in Africa and South America constrain deployment geography. Hybrid-electric modules appear first in offshore wind and research vessels where station-keeping precision trumps cost.
Methanol and ammonia-ready contracts grow at a 4.86% CAGR as engine makers such as MAN ES and WinGD validate commercial models for the 2025 handover. Nuclear propulsion remains naval-only, but next-gen microreactors could reach commercial feasibility post-2035, opening another shift vector for the shipbuilding market.
Complete Report Scope:
- By Vessel Type
- Bulk Carriers
- Oil Tankers
- Product / Chemical Tankers
- LNG / LPG Carriers
- Container Ships
- General Cargo Ships
- Passenger & Cruise Ships
- Offshore Support Vessels
- Naval & Coast-Guard Vessels
- Specialized (Ro-Ro, Car Carriers, etc.)
- By Propulsion Technology
- Conventional (HFO/DO)
- Dual-Fuel LNG
- Methanol / Ammonia Ready
- Hybrid-Electric
- Nuclear (Naval)
- By End User
- Commercial Shipping Companies
- Offshore-Energy Operators
- Passenger Transport & Cruise Lines
- Defence & Coast Guards
- Others (Research, Fisheries)
- By Material
- Steel
- Aluminium
- Composites & Advanced Alloys
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Norway
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific carried 38.30% of the shipbuilding market share in 2025, underlining its pivotal weight in the shipbuilding market. China alone secured three-fifths of worldwide orders and shipped three-fourths of bulk carriers. Low labor costs, integrated supply chains, and a vast domestic steel base make Chinese yards cost-competitive even after factoring in currency appreciation. Through advanced containment technology, South Korea protects high-value niches such as LNG carriers, commanding over three-fifths global gas-tanker output. Despite aging demographics restricting the workforce, Japan defends its share in quality-driven segments and zero-emission pilot projects.
The Middle East & Africa region is forecast to log the fastest 4.77% CAGR through 2031 as oil and gas capex flows into energy logistics corridors, IEA.ORG. Saudi Arabia and the UAE award large heavy-lift and module-carrier projects that require regional construction due to national-content thresholds. Turkey emerges as an LNG relay node between U.S. exporters and European buyers amid Red Sea instability, stimulating dry-dock and newbuild investments. North America leverages Jones Act rules to keep high-value installation vessel builds onshore, and the U.S. Navy's 30-year plan anchors multiprogram funding. European yards face environmental compliance that accelerates fleet renewal, but subdued steel consumption and macroeconomic headwinds temper yard utilization. Nonetheless, Norway and Denmark lead R&D in methanol and ammonia propulsion that finds early-adopter clients. South America registers selective growth, with Brazil's naval-focused ProSub initiative placing orders for submarines and support ships. This mosaic of regional imperatives sustains diversified opportunities across the shipbuilding market.
- China State Shipbuilding Corporation
- Mitsubishi Heavy Industries Ltd
- Samsung Heavy Industries
- Daewoo Shipbuilding Marine Engineering Co. Ltd
- Hyundai Heavy Industries Co. Ltd
- Sumitomo Heavy Industries
- Hanjin Heavy Industries and Construction Co.
- Yangzijiang Shipbuilding Ltd
- United Shipbuilding Corporation
- STX Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Seaborne Trade Volumes
- 4.2.2 Decarbonisation Mandates Driving Alt-Fuel Orders
- 4.2.3 Surge In Demand For Lng-Fuelled Carriers
- 4.2.4 Naval Fleet Modernisation Programmes
- 4.2.5 Offshore-Wind Installation Vessel Demand
- 4.2.6 Digital-Twin-Enabled Modular Construction
- 4.3 Market Restraints
- 4.3.1 Volatile Steel And Raw-Material Prices
- 4.3.2 Skilled-Labour Shortage In Key Hubs
- 4.3.3 Global Yard Over-Capacity In Bulk Segment
- 4.3.4 Stricter Imo Ghg Regulation Cost Burden
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Vessel Type
- 5.1.1 Bulk Carriers
- 5.1.2 Oil Tankers
- 5.1.3 Product / Chemical Tankers
- 5.1.4 LNG / LPG Carriers
- 5.1.5 Container Ships
- 5.1.6 General Cargo Ships
- 5.1.7 Passenger & Cruise Ships
- 5.1.8 Offshore Support Vessels
- 5.1.9 Naval & Coast-Guard Vessels
- 5.1.10 Specialized (Ro-Ro, Car Carriers, etc.)
- 5.2 By Propulsion Technology
- 5.2.1 Conventional (HFO/DO)
- 5.2.2 Dual-Fuel LNG
- 5.2.3 Methanol / Ammonia Ready
- 5.2.4 Hybrid-Electric
- 5.2.5 Nuclear (Naval)
- 5.3 By End User
- 5.3.1 Commercial Shipping Companies
- 5.3.2 Offshore-Energy Operators
- 5.3.3 Passenger Transport & Cruise Lines
- 5.3.4 Defence & Coast Guards
- 5.3.5 Others (Research, Fisheries)
- 5.4 By Material
- 5.4.1 Steel
- 5.4.2 Aluminium
- 5.4.3 Composites & Advanced Alloys
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Chile
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Norway
- 5.5.3.6 Spain
- 5.5.3.7 Russia
- 5.5.3.8 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 South Africa
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 China State Shipbuilding Corporation
- 6.4.2 Mitsubishi Heavy Industries Ltd
- 6.4.3 Samsung Heavy Industries
- 6.4.4 Daewoo Shipbuilding Marine Engineering Co. Ltd
- 6.4.5 Hyundai Heavy Industries Co. Ltd
- 6.4.6 Sumitomo Heavy Industries
- 6.4.7 Hanjin Heavy Industries and Construction Co.
- 6.4.8 Yangzijiang Shipbuilding Ltd
- 6.4.9 United Shipbuilding Corporation
- 6.4.10 STX Group
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment