

|
시장보고서
상품코드
2124260
아시아의 인더스트리 4.0 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Asia Industry 4.0 - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
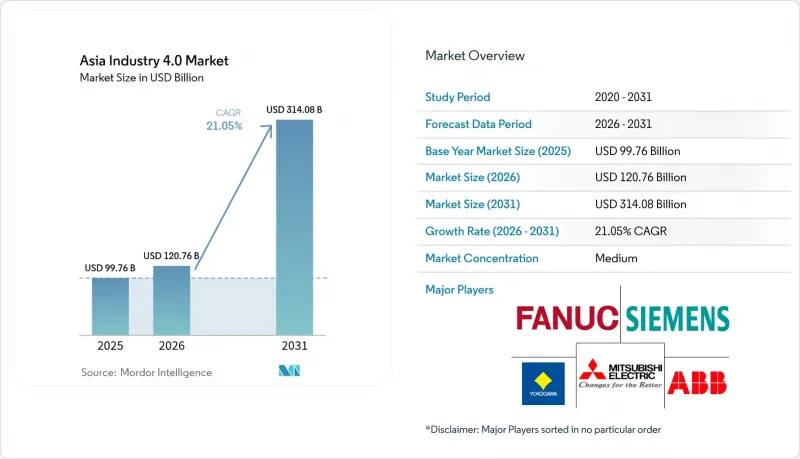
에 의하면, 아시아의 인더스트리 4.0시장 규모는 2025년 997억 6,000만 달러로 평가되었고, 2026년에는 1,207억 6,000만 달러로 추정되고, 2026-2031년 CAGR 21.05%로 성장을 지속할 전망이며, 2031년에는 3,140억 8,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 기술 유형별(산업용 로봇, IIoT 플랫폼 및 연결성, AI 및 ML, 기타), 최종 사용자 산업별(이산 제조, 자동차, 석유 및 가스, 기타), 배포 모델별(온프레미스, 클라우드, 기타), 조직 규모별(대기업 및 중소기업), 지역별(중국, 일본, 인도, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
아시아의 인더스트리 4.0 시장에 대한 인사이트과 동향
디지털 제조를 촉진하는 경제 대책이 산업 변혁을 가속화하고 있습니다.
아시아 전역에서 스마트 팩토리에 대한 보조금, 세제 혜택, 저리 융자 등에 대한 정부의 누적 지원액은 2,000억 달러를 초과하고 있습니다. 중국의 ‘제14차 5개년 계획’과 인도의 ‘생산 연계 인센티브(PLI)’ 제도는 자동화 프로젝트의 자금 조달 장벽을 낮추고, 공공 조달에서 공급업체의 진입 요건을 확대되고 있습니다. 일본의 ‘사회 5.0’과 한국의 ‘K-디지털 뉴딜’에서는 추가 보조금 및 인력 역량 강화 프로그램이 도입되어, 벤더들이 통합된 플랫폼 기반 솔루션을 채택하도록 장려하고 있습니다. 아시아의 인더스트리 4.0 시장은 부품 제조업체, 시스템 통합사업자, 소프트웨어 공급업체가 여러 산업에 걸쳐 동시에 수요 증가를 경험하고 있어 직접적인 혜택을 보고 있습니다. 조기에 부양책의 지원을 받은 제조업체들은 도입 후 2년 이내에 15-20%의 생산성 향상을 보고하고 있으며, 이는 후속 투자를 위한 선순환을 촉진하고 있습니다.
산업용 로봇 수요의 급증으로 전자 및 전기차(EV) 공급망이 변혁을 겪고 있습니다.
2024년에는 전 세계 로봇 도입 대수의 70%를 아시아가 차지했으며, 중국에서만 반도체 패키징 및 배터리 셀 조립을 위해 29만 대의 신규 로봇이 가동을 시작했습니다. 상하이의 전기차 생산 확대와 한국의 배터리 생산 확대에는 고밀도 로봇 셀만이 실현 가능한 마이크론 단위의 정밀도가 요구되고 있습니다. 타크트 타임 단축과 연중무휴 24시간 무인 가동은 밸류체인이 혼란스러운 상황에서도 처리량을 안정화시키려는 OEM의 목표와 부합하며, 아시아의 인더스트리 4.0 시장에서 자율 생산으로의 전환을 뒷받침하고 있습니다. 각 로봇 제조업체들은 현재 비전 센서 및 AI 기반 품질 분석 기능을 패키지화하고 있으며, 시스템의 부가가치를 높이는 동시에 치열한 입찰 경쟁에서 자사 제품의 차별화를 꾀하고 있습니다. 대량 생산을 수행하는 전자기기 라인에서는 투자 회수 기간이 2년 이하인 경우가 많아, 재무 부서는 수작업에 의한 단계적 업그레이드보다 멀티 로봇 셀 도입을 우선시하고 있습니다.
장기적인 이점이 있음에도 불구하고, 높은 초기 투자 비용이 도입의 장벽이 되고 있습니다.
스마트 팩토리로의 개조에는 1개 거점당 1,000만-5,000만 달러가 소요되는 경우가 많으며, 이는 중견 제조업체의 기존 설비 갱신 예산을 상회하는 금액입니다. 베트남이나 인도네시아의 현지 은행은 무형 자산인 소프트웨어에 대해 장기 대출을 제공하는 경우가 거의 없어, 그 결과 자체 자금 조달을 할 수밖에 없거나 프로젝트가 연기되는 경우가 있습니다. 투자 회수 전망은 예측 유지보수를 통한 비용 절감 및 불량품 감소에 달려 있지만, 이는 재무 부서에는 생소한 개념이기 때문에 내부 수익률이 기업의 기준을 충족하더라도 승인률은 낮은 임베디드니다. 그 결과, 아시아의 인더스트리 4.0 시장에서는 양극화가 나타나고 있으며, 자금력이 있는 다국적 기업이 앞서 나가는 반면, 현지 공급업체들은 뒤처지고 있습니다. 설비 투자를 최소화한 구독 모델이 등장하고 있지만, 벤더 종속(vendor lock-in)에 대한 우려와 총소유비용(TCO)의 체계가 모호한 탓에 그 보급은 제한적입니다.
부문 분석
2025년, 산업용 로봇은 전자 및 배터리 셀 자동화에 대한 지속적인 수요에 힘입어 아시아의 인더스트리 4.0 시장에서 23.05%의 점유율을 차지했습니다. 한편, 디지털 트윈 플랫폼은 연평균 성장률(CAGR) 22.15%로 성장하고 있으며, 가상 시운전, 예측 유지보수, 시나리오 계획을 가능하게 함으로써 물리적 자동화에 없어서는 안 될 파트너로서의 입지를 확립해 가고 있습니다. 디지털 트윈 구독과 관련된 아시아의 인더스트리 4.0 시장 규모는 라이선싱 기반 수익 모델이 소프트웨어 일괄 판매를 대체함에 따라 2031년까지 3배로 증가할 것으로 예측됩니다. 지역 내 OEM 기업들은 가동 시작 기간을 최소화하기 위해 로봇 셀에 디지털 트윈을 번들로 제공함으로써, 신규 라인 검증 기간을 6개월에서 3주로 단축하고 있습니다. 또한, 5G의 보급 확대와 센서 비용 하락에 힘입어 IIoT 연결 및 엣지 분석도 두 자릿수 성장을 기록하고 있습니다. 블록체인은 여전히 틈새 기술이지만, 식품 안전 및 의약품 일련화 분야에서 주목을 받고 있는 반면, XR 용도는 원격지나 지방에 위치한 공장의 원격 유지보수를 지원하고 있습니다. 디지털 트윈, 분석, AI 비전을 통합한 스택을 제공하는 벤더는 공장 관리자가 공급업체를 통합함에 따라 더 높은 시장 점유율을 확보할 전망입니다.
아시아의 반도체 팹에서는 5nm 노드 이하 칩에 요구되는 서브미크론 수준의 결함 검출 정밀도를 실현하는 AI 지원형 광학 검사 도구가 도입되고 있습니다. 이러한 도구는 데이터를 디지털 트윈 모델에 직접 공급하여 설계와 제조 간의 루프를 완성하고 있습니다. 일본의 로봇 제조업체들은 현재 팔(arm)에서 AI 추론을 수행하기 위해 NVIDIA 기반 GPU 모듈을 탑재하고 있어, 외부 서버 없이도 로봇 셀의 유연성을 높이고 있습니다. 엣지 게이트웨이에는 동기화된 다중 로봇 운영에 필수적인 결정론적 트래픽을 유지하기 위해 TSN(Time-Sensitive Networking) 기능이 탑재되어 있습니다. 컴퓨팅 비용의 감소에 따라 시뮬레이션 처리량이 향상되어, 제조업체는 물리적 변경을 한 번 수행하기 전에 수백 가지의 매개변수 조합을 테스트할 수 있게 되었습니다. 이러한 종합적인 접근 방식 덕분에 아시아의 인더스트리 4.0 시장은 하드웨어와 소프트웨어가 함께 진화하는 혁신의 샌드박스로서의 입지를 확고히 하고 있습니다.
2025년, 아시아의 인더스트리 4.0 시장에서 이산 제조는 20.65%의 점유율을 유지했습니다. 이는 가전제품의 대량 조립이 주도한 결과입니다. 한편, 항공우주 및 방위 산업 기업들은 엄격한 부품 공차 및 추적성 요건을 충족하기 위해 연평균 성장률(CAGR) 21.95%로 적층 가공, 디지털 트윈, 예측 분석을 도입하고 있습니다. 일본, 한국, 인도의 정부 방위 현대화 예산은 주요 계약업체의 스마트 팩토리 전환을 재정적으로 지원하며, 이에 따른 공급망 생태계의 확장을 가속화하고 있습니다. 중국과 동남아시아의 전기차(EV) 플랫폼은 특히 배터리 및 전력 전자 제품 생산 라인에서 로봇 도입 밀도를 더욱 높이고 있습니다. 반도체 팹은 AI 칩에 대한 수요 증가에 대응하기 위해 첨단 노드 생산을 확대하고 있으며, 이에 따라 결함 검사용 비전 시스템과 서브마이크론급 모션 컨트롤러의 도입이 진행되고 있습니다.
식품 및 음료 가공업체들은 새로운 안전 표시법을 준수하기 위해 블록체인 기반의 추적성을 통합하고 있는 반면, 석유 및 가스 사업자들은 유정의 수명을 연장하기 위해 AI 기반 자산 건전성 관리 플랫폼을 도입하고 있습니다. 에너지 및 유틸리티 기업들은 분산형 재생에너지 자산을 동기화하는 디지털 제어 센터에 투자하고 있으며, 이를 통해 터빈 및 인버터 설비군 전반에 걸쳐 예측 유지보수 소프트웨어 도입이 촉진되고 있습니다. 이러한 동향이 맞물리면서 아시아의 인더스트리 4.0 시장 고객층이 다양화되고, 기술 벤더의 부문 집중 위험이 감소하고 있습니다. 고부가가치 수직 시장이 성숙해짐에 따라, 유지보수, 업그레이드, 데이터 분석을 통한 서비스 수익이 하드웨어 성장률을 상회할 것으로 예상되며, 공급업체의 비즈니스 모델은 지속적인 수익원으로 재편될 것으로 보입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the Asia industry 4.0 market size is expected to grow from USD 99.76 billion in 2025 to USD 120.76 billion in 2026 and is forecast to reach USD 314.08 billion by 2031 at 21.05% CAGR over 2026-2031.
This report is Segmented by Technology Type (Industrial Robotics, Iiot Platforms and Connectivity, AI and ML, and More), End-User Industry (Discrete Manufacturing, Automotive, Oil and Gas, and More), Deployment Model (On-Premise, Cloud, and More), Organisation Size (Large Enterprises and SMEs), and Geography (China, Japan, India, and More). The Market Forecasts are Provided in Terms of Value (USD).
Insights and Trends of Asia Industry 4.0 Market
Pro-digital manufacturing stimulus packages accelerate industrial transformation
Across Asia, cumulative government commitments exceed USD 200 billion for subsidies to smart factories, tax holidays, and low-interest loans. China's 14th Five-Year Plan and India's Production Linked Incentive schemes are lowering capital hurdles for automation projects and widening supplier eligibility in public procurement. Japan's Society 5.0 and South Korea's K-Digital New Deal introduce additional grants and workforce upskilling programs that encourage vendors to adopt integrated, platform-based offerings. The Asia Industry 4.0 market benefits directly as component makers, systems integrators, and software providers experience synchronized demand across multiple verticals. Manufacturers receiving early stimulus support report 15%-20% productivity lifts within two years of deployment, reinforcing a positive feedback loop for follow-on investment.
Surging industrial-robotics demand transforms electronics and EV supply chains
In 2024, seventy percent of global robot installations took place in Asia, with China alone commissioning 290,000 new units for semiconductor packaging and battery-cell assembly. Growing electric-vehicle output in Shanghai and battery expansion in South Korea require micron-scale accuracy that only high-density robotics cells can deliver. Shorter takt times and 24/7 lights-out operations align with OEM goals to stabilize throughput during supply-chain shocks, reinforcing the Asia Industry 4.0 market's migration toward autonomous production. Robotics makers now bundle vision sensors and AI-based quality analytics, enhancing system value and differentiating offerings in crowded bidding contests. Rapid paybacks often under two years in high-volume electronics lines are convincing finance teams to prioritize multi-robot cells over incremental manual upgrades.
High upfront capital expenditure creates adoption barriers despite long-term benefits
Smart-factory retrofits often require USD 10-50 million per site, surpassing conventional equipment-replacement budgets for mid-tier manufacturers. Local banks in Vietnam and Indonesia rarely extend long-term loans for intangible software assets, forcing equity funding or delayed projects. Payback estimates hinge on predictive-maintenance savings and scrap reductions that remain unfamiliar to finance teams, suppressing approval rates even when internal rates of return align with corporate thresholds. The Asia Industry 4.0 market thus exhibits a bifurcation, where cash-rich multinational companies advance, while domestic suppliers lag behind. Capex-light subscription models are emerging, but uptake is limited by perceived vendor lock-in and ambiguous total cost-of-ownership frameworks.
Other drivers and restraints analyzed in the detailed report include:
- Government-funded SME digital-transformation vouchers democratize advanced manufacturing
- Private 5G campus networks enable ultra-low-latency industrial control systems
- Skills shortage and organizational resistance impede technology integration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial Robotics commanded a 23.05% share of the Asia Industry 4.0 market in 2025, driven by continued demand for electronics and battery-cell automation. However, Digital Twin platforms are growing at a 22.15% CAGR, asserting themselves as indispensable companions to physical automation by enabling virtual commissioning, predictive maintenance, and scenario planning. The Asia Industry 4.0 market size tied to digital-twin subscriptions is expected to triple by 2031 as license-based revenue models replace one-time software sales. Regional OEMs are bundling twins with robotics cells to minimize ramp-up times, cutting new-line validation from six months to three weeks. IIoT connectivity and edge analytics also experience double-digit growth, driven by the increasing availability of 5G and declining sensor costs. Blockchain remains a niche technology, but it is gaining traction in food safety and pharmaceutical serialization, while XR applications are assisting with remote maintenance for remote, rural factories. Vendors offering integrated stacks that merge twins, analytics, and AI vision stand to capture a higher wallet share as plant managers consolidate their suppliers.
Asian semiconductor fabs are adopting AI-assisted optical inspection tools that achieve sub-micron defect detection accuracy, a requirement for chips below the 5nm node. These tools feed data directly into digital-twin models, closing the loop between design and manufacturing. Japanese robotics manufacturers are now incorporating Nvidia-based GPU modules for on-arm AI inference, enhancing robotics cell flexibility without the need for external servers. Edge gateways ship with Time-Sensitive Networking (TSN) features to maintain deterministic traffic, crucial for synchronized multi-robot operations. As computing costs decrease, simulation throughput increases, allowing manufacturers to test hundreds of parameter combinations before a single physical change is made. This holistic approach cements the Asia Industry 4.0 market as an innovation sandbox where hardware and software co-evolve.
Discrete manufacturing retained 20.65% of the Asia Industry 4.0 market share in 2025, driven by high-volume assembly of consumer electronics. Yet aerospace and defense companies are embracing additive manufacturing, digital twins, and predictive analytics at a 21.95% CAGR to meet stringent component tolerances and traceability mandates. Government defense-modernization budgets in Japan, South Korea, and India finance smart-factory retrofits at prime contractors, accelerating their supplier ecosystems. Electric-vehicle platforms in China and Southeast Asia further stimulate robotics density, particularly in battery and power electronics lines. Semiconductor fabs are expanding advanced-node production to meet the growing demand for AI chips, thereby increasing the adoption of defect-inspection vision systems and sub-micron motion controllers.
Food and beverage processors integrate blockchain traceability to comply with new safety labeling laws, while oil and gas operators deploy AI-driven asset-integrity platforms to extend well life. Energy and utilities firms invest in digital control centers that synchronize distributed renewable assets, driving the adoption of predictive maintenance software across turbine and inverter fleets. These dynamics collectively broaden the Asia Industry 4.0 market's customer mix, reducing segment concentration risk for technology vendors. As high-value verticals mature, service revenue from maintenance, upgrades, and data analytics is expected to outpace hardware growth, reshaping vendor business models toward recurring income streams.
Complete Report Scope:
- By Technology Type
- Industrial Robotics
- IIoT Platforms and Connectivity
- Artificial Intelligence and Machine Learning
- Blockchain for Industrial Traceability
- Extended / Augmented / Mixed Reality
- Digital Twin
- 3-D Printing / Additive Manufacturing
- Other Technology Types
- By End-user Industry
- Discrete Manufacturing
- Automotive
- Oil and Gas
- Energy and Utilities
- Electronics and Foundry
- Food and Beverage
- Aerospace and Defence
- Other End-user Industries
- By Deployment Model
- On-premise
- Cloud
- Hybrid
- By Organisation Size
- Large Enterprises
- Small and Medium-sized Enterprises (SMEs)
- By Country
- China
- Japan
- India
- South Korea
- South-East Asia
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- ABB Ltd.
- Mitsubishi Electric Corporation
- Siemens AG
- Fanuc Corporation
- Yaskawa Electric Corporation
- Yokogawa Electric Corporation
- Omron Corporation
- Robert Bosch GmbH
- Schneider Electric SE
- Rockwell Automation Inc.
- Honeywell International Inc.
- Emerson Electric Co.
- Cisco Systems Inc.
- Intel Corporation
- IBM Corporation
- SAP SE
- PTC Inc.
- Fujitsu Ltd.
- Hitachi Ltd.
- Keyence Corporation
- Panasonic Corporation
- Huawei Technologies Co. Ltd.
- Samsung Electronics Co. Ltd.
- Denso Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Pro-digital manufacturing stimulus packages across Asia
- 4.2.2 Surging demand for industrial robotics in electronics and EV supply chains
- 4.2.3 Government-funded SME digital-transformation vouchers
- 4.2.4 Private 5G campus networks enabling ultra-low-latency control
- 4.2.5 Carbon-neutral manufacturing mandates driving OPEX optimisation
- 4.2.6 Regional supply-chain resilience schemes (e.g., "China + 1")
- 4.3 Market Restraints
- 4.3.1 High upfront capex and unclear pay-back windows
- 4.3.2 Acute OT-IT skills shortage and change-management inertia
- 4.3.3 Fragmented industrial data standards hindering interoperability
- 4.3.4 Escalating cyber-insurance premiums for connected OT assets
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology Type
- 5.1.1 Industrial Robotics
- 5.1.2 IIoT Platforms and Connectivity
- 5.1.3 Artificial Intelligence and Machine Learning
- 5.1.4 Blockchain for Industrial Traceability
- 5.1.5 Extended / Augmented / Mixed Reality
- 5.1.6 Digital Twin
- 5.1.7 3-D Printing / Additive Manufacturing
- 5.1.8 Other Technology Types
- 5.2 By End-user Industry
- 5.2.1 Discrete Manufacturing
- 5.2.2 Automotive
- 5.2.3 Oil and Gas
- 5.2.4 Energy and Utilities
- 5.2.5 Electronics and Foundry
- 5.2.6 Food and Beverage
- 5.2.7 Aerospace and Defence
- 5.2.8 Other End-user Industries
- 5.3 By Deployment Model
- 5.3.1 On-premise
- 5.3.2 Cloud
- 5.3.3 Hybrid
- 5.4 By Organisation Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium-sized Enterprises (SMEs)
- 5.5 By Country
- 5.5.1 China
- 5.5.2 Japan
- 5.5.3 India
- 5.5.4 South Korea
- 5.5.5 South-East Asia
- 5.5.6 Rest of Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Mitsubishi Electric Corporation
- 6.4.3 Siemens AG
- 6.4.4 Fanuc Corporation
- 6.4.5 Yaskawa Electric Corporation
- 6.4.6 Yokogawa Electric Corporation
- 6.4.7 Omron Corporation
- 6.4.8 Robert Bosch GmbH
- 6.4.9 Schneider Electric SE
- 6.4.10 Rockwell Automation Inc.
- 6.4.11 Honeywell International Inc.
- 6.4.12 Emerson Electric Co.
- 6.4.13 Cisco Systems Inc.
- 6.4.14 Intel Corporation
- 6.4.15 IBM Corporation
- 6.4.16 SAP SE
- 6.4.17 PTC Inc.
- 6.4.18 Fujitsu Ltd.
- 6.4.19 Hitachi Ltd.
- 6.4.20 Keyence Corporation
- 6.4.21 Panasonic Corporation
- 6.4.22 Huawei Technologies Co. Ltd.
- 6.4.23 Samsung Electronics Co. Ltd.
- 6.4.24 Denso Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


