|
시장보고서
상품코드
2124270
로우코드 개발 플랫폼 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Low-code Development Platform - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
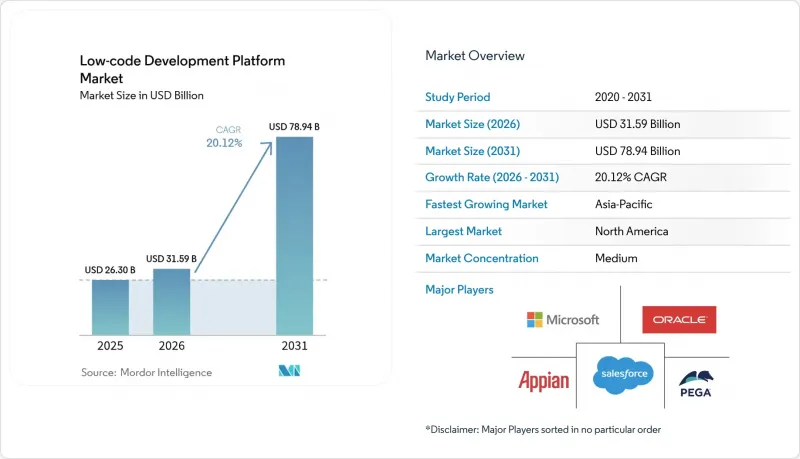
에 의하면, 2026년 로우코드 개발 플랫폼 시장 규모는 315억 9,000만 달러로 추정되고, 2025년 263억 달러에서 확대해, 2031년에는 789억 4,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 20.12%로 성장할 것으로 전망됩니다.
본 보고서는 구성 요소별(플랫폼, 기타), 용도 유형별(웹 기반, 모바일 기반, 기타), 배포 방식별(온프레미스, 클라우드), 조직 규모별(중소기업, 대기업), 산업별(은행, 금융서비스 및 보험(BFSI), 소매 및 전자상거래, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러)으로 표시되어 있습니다.
세계의 로우코드 개발 플랫폼 시장 동향 및 인사이트
로우코드 조달을 통한 미국 연방 정부 기관의 레거시 COBOL 시스템 현대화 의무화
연방 정부 각 부처는 수십년동안 사용되어 온 COBOL 플랫폼을 폐지하고, 계약 간접비를 23% 절감하는 다중 공급업체 계약 방식의 포괄 구매 계약을 통해 이를 로우코드 시스템으로 대체하고 있습니다. 국방계약관리국(DCMA)은 2025년 현대화에 관한 정보 제공 요청(RFI)에서 통합 계약 관리를 위한 우선적인 수단으로 로우코드를 강조했습니다. 현재 각 주 정부도 이러한 연방 정부의 모델을 따르고 있으며, 대상 지출 규모를 확대함과 동시에 급속한 현대화를 위한 공공 부문의 표준으로서 로우코드 플랫폼의 입지를 공고히 하고 있습니다. FedRAMP 및 DoD IL5 준수를 입증할 수 있는 벤더는 이러한 확대되는 조달 흐름에 우선적으로 진입할 수 있으며, 로우코드 개발 플랫폼 시장의 추가적인 성장을 뒷받침하고 있습니다.
EU의 실시간 컴포저블 뱅킹 이니셔티브가 로우코드 도입을 가속화하고 있습니다.
금융 데이터 접근 규정에 따라 유럽의 은행들은 2027년까지 API를 통해 고객 데이터를 공개해야 할 의무가 있습니다. 이를 보완하는 ‘디지털 운영 복원력 법(Digital Operational Resilience Act)’ 규정은 ICT 위험 감독을 강화하고, 주 단위로 업데이트되는 규정에 적응할 수 있는 애자일 아키텍처로의 전환을 금융 기관에 촉구하고 있습니다. 로우코드 플랫폼은 규정 준수를 충족하는 API를 생성하고 관리 증거를 자동화함으로써 이 두 가지 요구 사항을 모두 충족합니다. 유럽중앙은행(ECB) 감독 당국은 모듈식 서비스 배포를 평가하는 클라우드 아웃소싱 관련 요건을 공식적으로 규정하고 있습니다. 이에 따라 전통적 은행들은 로우코드 개발 플랫폼 시장에서 핀테크 신생 기업의 출시 속도를 따라잡기 위해 로우코드 도구에 의존하고 있습니다.
독점 런타임에 의한 벤더 락인이 전환 비용을 상승시키고 있다.
2024년 동료 검토를 거친 연구에서는 전환 위험을 정량화하고, 독점 런타임에 묶인 용도의 높은 비용 위험을 밝혀내는 클라우드 벤더 락인 예측 프레임워크가 발표되었습니다. 많은 로우코드 시스템은 워크플로를 폐쇄형 실행 엔진으로 컴파일하기 때문에 이식성이 제한됩니다. CIO들은 현재 소스 코드 내보내기 및 컨테이너화된 배포 옵션을 요구하고 있으며, 이는 구매 주기의 지연을 초래하여 로우코드 개발 플랫폼 시장의 일부 성장을 억제하고 있습니다.
부문 분석
플랫폼 부문은 2025년 매출의 71.35%를 차지했으며, 로우코드 개발 플랫폼 시장의 기반을 형성하고 있습니다. 기업들은 시각적 모델링, 프로세스 오케스트레이션, 통합 데이터베이스를 결합한 통합 환경을 선호하며, 이를 통해 도구 과다 사용을 억제하고 있습니다. Salesforce의 Informatica 80억 달러 규모 인수와 같은 산업 재편 움직임으로 인해 데이터 관리와 AI가 단일 런타임으로 통합되면서 기업에 대한 락인 효과가 더욱 심화되고 있습니다. 플랫폼 도입에 이어 서비스 라인 확대가 진행되고 있습니다. 특정 벤더를 표준화하는 연방 정부 기관에서는 통합 컨설팅, 거버넌스 프레임워크, AI 프롬프트 설계에 대한 지속적인 수요가 발생하고 있습니다.
서비스 부문은 규모는 작지만, 조직들이 COBOL 워크로드 마이그레이션, ESG 분석 통합, GenAI 코파일럿 훈련을 수행할 파트너를 찾음에 따라 연평균 성장률(CAGR) 23.45%로 성장하고 있습니다. 이러한 자문 수요 증가로 인해 프리미엄 지원 및 관리형 서비스 계약률이 상승하며, 업계에 지속적인 수익원이 추가되고 있습니다. 예측 기간 동안 라이선스 외에도 교육, 데이터 패브릭 튜닝, AI 모델 거버넌스를 패키지로 제공하는 벤더는 평생 가치(LTV)를 두 배로 늘리고 시장을 확대할 수 있습니다.
2025년에도 웹 애플리케이션이 지출의 54.40%를 차지했으며, 현장 기술자나 원격 근무 직원이 ‘오프라인 우선’ 기능을 요구함에 따라 모바일 워크로드는 연평균 성장률(CAGR) 22.63%로 증가하고 있습니다. 카메라, 생체 인식, 증강현실(AR)용 네이티브 플러그인을 통해 모바일 경험은 더욱 풍부해지고 상황에 맞게 변화하고 있습니다. 모바일 이용 사례를 위한 로우코드 개발 플랫폼 시장 규모는 특히 보험 검사 및 유틸리티 유지보수 부문에서 급속히 확대될 것으로 예측됩니다.
API 중심 설계는 웹 앱과 모바일 앱 모두를 확장하며, 조합형 뱅킹 및 오픈 데이터 정책과도 부합합니다. 마이크로소프트가 계획하고 있는 모놀리식 Dynamics 365 화면에서 작업 지향적 AI 에이전트로의 전환은 인터페이스가 상황에 맞는 마이크로 인터랙션으로 녹아드는 경향을 부각시키고 있습니다. 반응형 디자인, 원클릭 PWA 생성, 안전한 오프라인 동기화를 제공하는 벤더는 다중 채널에서의 일관성을 추구하는 조직들 사이에서 시장 점유율을 점차 확대해 나갈 것으로 보입니다.
지역별 분석
북미는 연방 정부의 현대화와 성숙한 벤처 생태계에 힘입어 2025년에는 매출의 30.60%를 차지했습니다. 미국 정부의 COBOL 단계적 폐지와 FedRAMP 준수의 철저한 이행은 주 정부 기관의 모델이 되어, 사법, 교통, 의료 분야에서 재현 가능한 배포의 기반을 마련하고 있습니다. 캐나다에서는 로우코드를 활용하여 핀테크 라이선싱 및 디지털 ID 프로젝트를 가속화하고 있으며, 이는 지역 전체의 성장세를 확대되고 있습니다. 벤처 캐피털은 AI를 접목한 로우코드 스타트업에 대한 지원을 지속하며, 로우코드 개발 플랫폼 시장을 뒷받침하는 제품 혁신을 촉진하고 있습니다.
아시아태평양은 21.13%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 일본의 보험사들은 IFRS 17에 대응하는 감사 대응형 빌더를 도입하고 있는 반면, 싱가포르 금융관리청은 핀테크 샌드박스의 신속한 도입을 장려하고 있습니다. 중국은 걸프 연안 국가들의 하이퍼스케일 데이터센터에 자금을 지원하며, 유럽 및 미국 표준을 준수하는 런타임을 호스팅하는 주권 클라우드를 제공합니다. 인도의 주요 IT 서비스 기업들은 전 세계 변혁 프로젝트에 로우코드 액셀러레이터를 통합하여 수출 수익을 확대하는 동시에, 국내 공공 부문에서의 도입을 촉진하고 있습니다. 이러한 노력들이 결합되어 향후 로우코드 개발 플랫폼 시장의 성장에 이 지역이 지대한 기여를 할 수 있도록 뒷받침하고 있습니다.
유럽은 전 세계 제품 로드맵을 형성하는 규제적 영향력을 보유하고 있습니다. ECB(유럽중앙은행)의 클라우드 기준, 오픈 뱅킹 API 도입 기한, ESG 공시 의무로 인해 기업들은 규정 준수를 신속히 자동화해야 하는 압박을 받고 있습니다. 북유럽 국가 정부들은 로우코드 포털을 통해 시민 서비스를 제공하고 있으며, 독일의 자동차 OEM 기업들은 성능에 대한 우려에도 불구하고 현장용 앱 프로토타입을 개발하고 있고, 프랑스의 유틸리티 기업들은 ESG 보고 파이프라인을 통합하고 있습니다. 이러한 조치의 추진력이 시너지 효과를 창출함에 따라, 유럽은 지속적으로 확대되는 로우코드 개발 플랫폼 시장의 초석으로 자리매김하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, low-code development platform market size in 2026 is estimated at USD 31.59 billion, growing from 2025 value of USD 26.30 billion with 2031 projections showing USD 78.94 billion, growing at 20.12% CAGR over 2026-2031.
This report is Segmented by Component (Platform and More), Application Type (Web-Based, Mobile-Based, and More), Deployment Type (On-Premises, Cloud), Organization Size (Small and Medium Enterprises, Large Enterprises), Industry Vertical (BFSI, Retail and E-Commerce, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Low-code Development Platform Market Trends and Insights
Mandated modernization of legacy COBOL systems in U.S. federal agencies via low-code procurement
Federal departments are retiring decades-old COBOL platforms and replacing them with low-code systems through multi-award blanket purchase agreements that lower contract overhead by 23% . The Defense Contract Management Agency highlighted low-code in its 2025 modernization RFI as the preferred path for integrated contract management. States now replicate these federal templates, expanding addressable spend and cementing low-code platforms as the public-sector default for rapid modernization. Vendors able to verify FedRAMP and DoD IL5 compliance gain privileged access to this growing procurement wave, supporting further growth for the low-code development platform market.
Real-time composable banking initiatives in the EU accelerating low-code adoption
The Financial Data Access regulation obliges European banks to expose customer data via APIs by 2027. Complementary Digital Operational Resilience Act rules tighten ICT risk oversight and push institutions toward agile architectures that can adapt to weekly rule updates. Low-code platforms answer both needs by generating compliant APIs and automating control evidence. Supervisors at the European Central Bank have formalized cloud-outsourcing expectations that reward modular service deployment. Traditional banks therefore rely on low-code tooling to match the release velocity of fintech challengers across the low-code development platform market.
Proprietary runtime vendor lock-in elevating migration costs
A 2024 peer-reviewed study introduced a cloud vendor lock-in prediction framework that quantifies switching risk and reveals high cost exposures for applications bound to proprietary runtimes. Many low-code systems compile workflows into closed execution engines that limit portability. CIOs now require source-code export and containerized deployment options, slowing purchase cycles and suppressing a portion of the low-code development platform market.
Other drivers and restraints analyzed in the detailed report include:
- APAC insurers' regulatory approval of low-code audit trails
- GenAI copilots within platforms reducing build-cycle time by 40%
- Performance limitations for compute-intensive industrial IoT apps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The platform segment represented 71.35% revenue in 2025 and anchors the low-code development platform market. Enterprises favor unified environments that combine visual modelling, process orchestration, and integrated databases, thereby reducing tool sprawl. Consolidation plays such as Salesforce's USD 8 billion acquisition of Informatica fold data management and AI into a single runtime to deepen enterprise lock-in. Service-line expansion follows platform rollout: federal agencies that standardize on one vendor generate continuous demand for integration consulting, governance frameworks, and AI-prompt design.
Services, while smaller, are growing at 23.45% CAGR as organizations look for partners to migrate COBOL workloads, embed ESG analytics, and train GenAI copilots. This advisory wave lifts attach rates for premium support and managed services, adding recurring revenue layers to the industry. Over the forecast, vendors that package training, data-fabric tuning, and AI-model governance alongside licences can double lifetime value and widen the market.
Web apps still controlled 54.40% spending in 2025, yet mobile workloads are rising at 22.63% CAGR as field technicians and remote employees demand offline-first capabilities. Native plug-ins for camera, biometrics, and augmented reality make mobile experiences richer and more contextual. The low-code development platform market size for mobile use cases is projected to grow rapidly, especially in insurance inspections and utility maintenance.
API-centric designs extend both web and mobile apps, aligning with composable-banking and open-data directives. Microsoft's planned shift from monolithic Dynamics 365 screens to task-oriented AI agents underlines how interfaces will dissolve into contextual micro-interactions. Vendors that ship responsive design, one-click PWA generation, and secure offline sync will capture incremental market share among organizations pursuing multi-channel parity.
Complete Report Scope:
- By Component
- Platform
- Services
- By Application Type
- Web-Based
- Mobile-Based
- Desktop / Server-Based
- API-Centric & Micro-Services
- By Deployment Mode
- Cloud
- On-Premise
- By Organization Size
- Small and Medium Enterprises
- Large Enterprises
- By Industry Vertical
- Banking
- Financial Services and Insurance (BFSI)
- Retail and E-commerce
- Government and Defense
- Information Technology and Telecom
- Healthcare and Life Sciences
- Manufacturing
- Energy and Utilities
- Education
- Media and Entertainment
- Others (Transportation, Real Estate)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Nordics
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
North America held 30.60% revenue in 2025, driven by federal modernization and a mature venture ecosystem. The U.S. government's push to sunset COBOL and enforce FedRAMP compliance sets a template for state agencies, seeding repeatable rollouts across justice, transport, and health. Canada leverages low-code to expedite fintech licensing and digital-identity projects, broadening regional momentum. Venture capital continues to back AI-infused low-code startups, fuelling product innovation that sustains the low-code development platform market.
Asia-Pacific posts the fastest 21.13% CAGR. Japan's insurers adopted audit-ready builders for IFRS 17, while Singapore's Monetary Authority encourages rapid fintech sandboxing. China finances hyperscale data centers in Gulf states, offering sovereign clouds that host Western-compatible runtimes. India's IT-services leaders embed low-code accelerators within global transformation deals, amplifying export revenue while catalyzing local public-sector uptake. These initiatives collectively underpin the region's outsized contribution to future low-code development platform market growth.
Europe wields regulatory influence that shapes global product roadmaps. ECB cloud standards, open-banking API deadlines, and ESG disclosure mandates force enterprises to automate compliance fast. Nordic governments deliver citizen services via low-code Portals, Germany's auto OEMs prototype shop-floor apps despite performance caveats, and French utilities integrate ESG reporting pipelines. With policy momentum compounding, Europe remains a cornerstone of the expanding low-code development platform market.
- Microsoft Corporation
- Salesforce Inc.
- Appian Corporation
- Oracle Corporation
- Mendix (Business of Siemens)
- OutSystems Inc.
- ServiceNow Inc.
- Magic Software Enterprises Ltd.
- Quickbase Inc.
- Zoho Corporation
- Clear Software LLC
- Temenos (formerly Kony Inc.)
- AgilePoint Inc.
- Betty Blocks B.V.
- Creatio Global
- Kissflow Inc.
- Nintex Global Ltd.
- GeneXus International SA
- LANSA Inc.
- Newgen Software Technologies
- WaveMaker Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Mandated Modernization of Legacy COBOL Systems in U.S. Federal Agencies via Low-Code Procurement
- 4.2.2 Real-Time Composable Banking Initiatives in EU Accelerating Low-Code Adoption
- 4.2.3 APAC Insurers Regulatory Approval of Low-Code Audit Trails
- 4.2.4 GenAI Copilots Within Platforms Reducing Build-Cycle Time by 40%
- 4.2.5 EU ESG Reporting Deadlines Driving Rapid App Deployment Demand
- 4.3 Market Restraints
- 4.3.1 Proprietary Runtime Vendor Lock-In Elevating Migration Costs
- 4.3.2 Performance Limitations for Compute-Intensive Industrial IoT Apps
- 4.3.3 Data-Residency Barriers Hampering Cloud-First Deployments in Middle East
- 4.4 Regulatory or Technological Outlook
- 4.4.1 Emerging Technology Trends
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
- 4.6 Vendor Market Positioning Analysis
- 4.7 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Platform
- 5.1.2 Services
- 5.2 By Application Type
- 5.2.1 Web-Based
- 5.2.2 Mobile-Based
- 5.2.3 Desktop / Server-Based
- 5.2.4 API-Centric & Micro-Services
- 5.3 By Deployment Mode
- 5.3.1 Cloud
- 5.3.2 On-Premise
- 5.4 By Organization Size
- 5.4.1 Small and Medium Enterprises
- 5.4.2 Large Enterprises
- 5.5 By Industry Vertical
- 5.5.1 Banking
- 5.5.2 Financial Services and Insurance (BFSI)
- 5.5.3 Retail and E-commerce
- 5.5.4 Government and Defense
- 5.5.5 Information Technology and Telecom
- 5.5.6 Healthcare and Life Sciences
- 5.5.7 Manufacturing
- 5.5.8 Energy and Utilities
- 5.5.9 Education
- 5.5.10 Media and Entertainment
- 5.5.11 Others (Transportation, Real Estate)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Nordics
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 South Africa
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 United Arab Emirates
- 5.6.5.4 Nigeria
- 5.6.5.5 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 Salesforce Inc.
- 6.4.3 Appian Corporation
- 6.4.4 Oracle Corporation
- 6.4.5 Mendix (Business of Siemens)
- 6.4.6 OutSystems Inc.
- 6.4.7 ServiceNow Inc.
- 6.4.8 Magic Software Enterprises Ltd.
- 6.4.9 Quickbase Inc.
- 6.4.10 Zoho Corporation
- 6.4.11 Clear Software LLC
- 6.4.12 Temenos (formerly Kony Inc.)
- 6.4.13 AgilePoint Inc.
- 6.4.14 Betty Blocks B.V.
- 6.4.15 Creatio Global
- 6.4.16 Kissflow Inc.
- 6.4.17 Nintex Global Ltd.
- 6.4.18 GeneXus International SA
- 6.4.19 LANSA Inc.
- 6.4.20 Newgen Software Technologies
- 6.4.21 WaveMaker Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment