|
시장보고서
상품코드
2124288
아시아태평양의 스몰셀 타워 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Asia Pacific Small Cell Tower - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
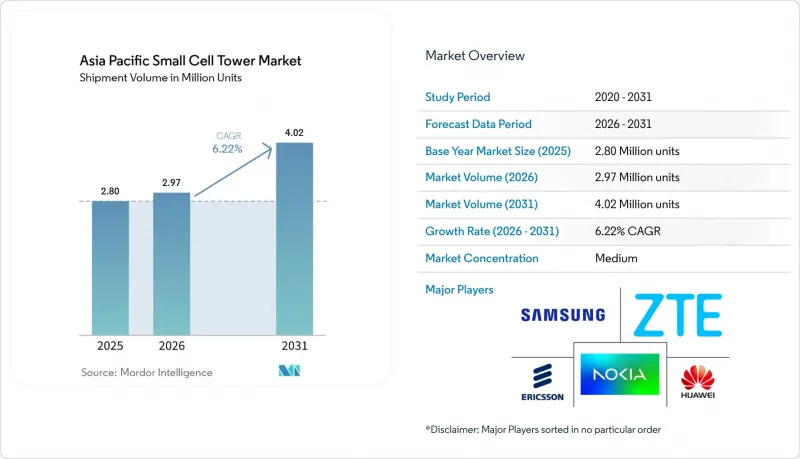
에 의하면, 아시아태평양의 스몰셀 타워 시장 규모는 2025년 280만 대로 평가되었고, 2026년에는 297만 대로 추정되고, 2026-2031년 CAGR 6.22%로 성장을 지속할 전망이며, 2031년에는 402만 대에 이를 것으로 예측됩니다.
본 보고서는 용도별(실외·실내), 네트워크 기술별(3G, 4G/LTE, 5G), 소유 모델별(통신 사업자 설치, 중립 호스트, 민간 기업), 도입 장소별(도심, 교외, 지방), 국가별(중국, 한국, 일본, 인도, 동남아시아, 기타 아시아태평양)로 분류되어 있습니다. 시장 예측은 수량(대수) 기준으로 제시되어 있습니다.
아시아태평양의 스몰셀 타워 시장 동향 및 인사이트
모바일 데이터 트래픽의 급증 및 고밀도화 요구 사항
모바일 동영상 스트리밍, 클라우드 게임, 업무용 협업 도구의 보급으로 인해 주요 대도시권에서는 트래픽이 전년 대비 40-60% 급증하여, 매크로 기지국의 설계상 한계를 넘어서는 용량 부족 현상이 발생하고 있습니다. 통신 사업자들은 현재 부동산 제약이 있는 지역에서 스펙트럼 재사용을 실현하기 위한 가장 비용 효율적인 수단으로 스몰셀을 활용한 고밀도 네트워크를 꼽고 있습니다. 가로등 기둥, 버스 정류장 대합실, 건물 외벽 등에 이러한 무선 장비를 설치함으로써 토지 소유주와의 협상을 최소화하면서 설치 기간을 단축할 수 있습니다. 이러한 고밀도화의 필요성은 피크 시간대에 사용자 1인당 처리량 수요가 여전히 가장 높은 공항, 쇼핑몰, 오락 시설로도 확대되고 있습니다. 4G 앵커 캐리어와 5G NR을 통합한 소형 멀티밴드 무선 장비를 공급할 수 있는 벤더는 우선 공급업체로서의 입지를 확고히 다지고 있습니다. 그 결과, 아시아태평양의 스몰셀 타워 시장은 시범 도입 단계에서 대규모 그리드 계획 단계로 성숙해 가고 있습니다.
아시아태평양 전역의 5G 구축 일정 가속화
각사의 경쟁적인 발표로 인해 각국의 5G 로드맵이 최대 18개월이나 앞당겨지면서, 통신 사업자들은 부지 확보, 토목 공사, 통합 작업을 단축할 수밖에 없게 되었습니다. 중국과 한국 정부는 인프라 개발을 더 광범위한 경제 성장 목표와 연계하여, 전개를 가속화하기 위해 자금과 공공 부지를 제공합니다. 스몰셀은 커버리지 범위가 제한적이기 때문에 새로운 매크로 타워를 기다릴 필요 없이 신속하게 5G 커버리지를 오버레이할 수 있습니다. NSA 모드와 SA 모드를 전환할 수 있는 멀티 기술 무선 장비는 통신 사업자가 단기적인 커버리지 약속을 이행하는 동시에, 독립형(SA) 코어로의 전환을 위한 기반 구축을 지원합니다. 통합 안테나, 디지털 프론트홀, 제로 터치 프로비저닝 도구는 수익 창출까지의 기간을 단축시켜, 아시아태평양의 스몰셀 타워 시장에서 견조한 수요를 뒷받침하고 있습니다.
복잡한 부지 확보 및 인허가 장벽
지자체별 구역 지정 규정의 불일치로 인해 승인 절차가 장기화되고 임대료가 급등하고 있습니다. 특히 인도의 1급 도시에서는 건물 소유주가 고액의 임대료를 요구하기 때문에 이러한 경향이 두드러집니다. 일부 관할 구역에서는 소방, 항공, 문화재 보호 부서로부터 개별적으로 ‘이의 없음 증명서’를 취득해야 하며, 이는 프로젝트 일정을 지연시키는 요인이 되고 있습니다. 표준화된 요금 체계가 존재하지 않아, 부지별 비용 변동이 투자 수익률(ROI) 산정을 어렵게 하고, 네트워크 계획 수립을 복잡하게 만들고 있습니다. 통신 사업자들은 옥상 접근권에 대해 매번 협상을 진행하는 경우가 많으며, 이로 인해 네트워크 밀도 향상이 지연되고, 아시아태평양의 스몰 셀 타워 시장에서 단기적인 출하량 상한선이 되고 있습니다.
부문 분석
2025년, 실내 설치 사이트는 아시아태평양 스몰 셀 타워 시장 출하 대수의 30.88%를 차지한 것으로 평가되었으며, 이는 약 86만 대에 해당합니다. 또한 2031년까지 연평균 성장률(CAGR) 7.32%를 나타낼 것으로 전망됩니다. 기업들은 고객 참여 도구, 무인 계산대, 몰입형 소매 디스플레이에 있어 견고한 실내 5G 환경이 필수적이라고 생각합니다. 그 결과, 쇼핑몰, 공항, 경기장에서는 Wi-Fi 업그레이드 대신 스몰셀 계층에만 설비 투자 예산을 할당하고 있습니다. 뉴트럴 호스트 사업자는 이러한 시스템을 장기 서비스 계약에 포함시킴으로써 예산 승인을 원활하게 하는 동시에 여러 통신사에 대한 접근성을 확보하고 있습니다.
실외 구축은 계속해서 아시아태평양 스몰셀 타워 시장의 기반을 이루고 있으며, 2025년 출하 대수의 69.12%를 차지했습니다. 통신 사업자들은 출퇴근 시간대 매크로 섹터의 혼잡을 완화하기 위해 골목길이나 교통 통로에 폴 마운트형 및 벽면 설치형 무선 장비를 설치하고 있습니다. 통합형 가로 설비 설계에서는 무선 기기, 전원 모듈, 백홀 회선을 미관을 고려한 케이스에 일체화하여, 이를 통해 지자체의 조례 요건을 충족하고 있습니다. 실외 그리드가 여전히 주요 수익원인 반면, 실내 그리드의 성장세가 가속화되고 있는 것은 이 시장이 두 가지 궤도로 성장하고 있음을 보여줍니다.
4G/LTE 무선 기기는 2025년 출하 대수의 50.32%를 차지했으며, 아시아태평양의 스몰 셀 타워 시장 규모에서 141만 대에 해당하는데, 이는 통신 사업자들이 기존 주파수 대역 할당을 최대한 활용하는 것을 우선시하고 있음을 반영합니다. 그러나 통신 사업자들이 멀티 기가비트급 피크 처리량을 지원하는 미드밴드 및 mm파 대역을 도입함에 따라, 5G 무선 기기는 연평균 성장률(CAGR) 7.98%로 확대되고 있습니다. 듀얼 표준 커버리지를 실현하는 콤보 무선 기기는 사이트 임대료 지출을 억제하면서 사용자의 전환을 가속화합니다.
또한, 멀티 기술 플랫폼의 도입은 단말기 구성과 관련된 현실적인 과제에도 대응하고 있습니다. 2025년 말 시점에서 동남아시아의 많은 시장에서 5G 스마트폰 보급률은 45% 미만에 그치고 있어, 통신 사업자들은 음성 서비스 및 IoT 엔드포인트를 위해 4G 앵커 링크를 유지할 수밖에 없습니다. 3G의 단계적 폐지 계획에 따라 추가 주파수 대역이 확보되고, 통신 사업자는 해당 대역폭을 5G NR용으로 재할당할 수 있게 됨에 따라, 소프트웨어를 통한 업그레이드가 가능한 무선 장비에 대한 수요가 더욱 높아지고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the Asia Pacific small cell tower market size is expected to grow from 2.80 million units in 2025 to 2.97 million units in 2026 and is forecast to reach 4.02 million units by 2031 at 6.22% CAGR over 2026-2031.
This report is Segmented by Application (Outdoor, and Indoor), Network Technology (3G, 4G/LTE, and 5G), Ownership Model (Operator-Deployed, Neutral-Host, and Private Enterprises), Deployment Location (Urban, Suburban, and Rural), and Country (China, South Korea, Japan, India, South-East Asia, and Rest of Asia Pacific). The Market Forecasts are Provided in Terms of Volume (Units).
Asia Pacific Small Cell Tower Market Trends and Insights
Rapid Surge in Mobile Data Traffic and Densification Requirements
Mobile video streaming, cloud gaming, and workplace collaboration tools have triggered year-over-year traffic spikes of 40-60% in key metropolitan areas, exceeding the capacity of macro sites beyond their engineered limits. Operators now view dense grids of small cells as the most cost-efficient lever to add spectral reuse in real estate-constrained neighborhoods. Street-level poles, bus shelters, and building facades host these radios, minimizing landlord negotiations while shortening installation cycles. The densification imperative extends to airports, malls, and entertainment venues, where per-user throughput demands remain highest during peak hours. Vendors able to supply compact, multi-band radios that integrate 4G anchor carriers with 5G NR are securing preferred-supplier status. As a result, the Asia Pacific small cell tower market continues to mature from pilot deployments toward mass-scale grid planning.
Accelerated 5G Rollout Timelines Across Asia Pacific
Competitive announcements have condensed national 5G roadmaps by as much as 18 months, forcing operators to compress site-acquisition, civil works, and integration activities. Governments in China and South Korea have linked infrastructure development to broader economic growth targets, releasing funds and public properties for accelerated deployment. Because small cells cover limited radii, they enable rapid 5G coverage overlays without waiting for new macro towers. Multi-technology radios that switch between NSA and SA modes help operators satisfy near-term coverage promises while laying groundwork for standalone cores. Integrated antennas, digital front-haul, and zero-touch provisioning tools are shortening time-to-revenue, underpinning robust demand for the Asia Pacific small cell tower market.
Complex Site Acquisition and Permitting Hurdles
Municipal zoning disparities prolong approval cycles and inflate leasing charges, especially across tier-1 Indian cities where building owners demand premium rents. Some jurisdictions require separate no-objection certificates from fire, aviation, and heritage departments, which can extend project timelines. The absence of standardized fee structures complicates network planning, as per-site cost variability challenges return-on-investment calculations. Operators often negotiate rooftop access on an ad-hoc basis, delaying grid densification and capping near-term shipment volumes for the Asia Pacific small cell tower market.
Other drivers and restraints analyzed in the detailed report include:
- Government Initiatives and Spectrum Policies Supporting Small Cell Deployments
- Emergence of Private 5G Networks in Manufacturing Corridors
- High Upfront Capital Expenditure for Dense Deployments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Indoor sites captured 30.88% of shipments in 2025, equivalent to approximately 0.86 million units of the Asia Pacific small cell tower market size, and are projected to track a 7.32% CAGR to 2031. Enterprises view robust indoor 5G as non-negotiable for customer engagement tools, cashier-less checkouts, and immersive retail displays. Consequently, shopping malls, airports, and stadiums allocate capital expenditure budgets exclusively for small cell layers rather than Wi-Fi upgrades. Neutral-host operators bundle these systems into long-term service agreements, easing budget approval while ensuring multi-carrier access.
Outdoor deployments continue to anchor the Asia Pacific small cell tower market, accounting for 69.12% of the 2025 volumes. Operators use pole-mount and wall-mount radios in alleyways and transit corridors to alleviate macro-sector congestion during peak commuting hours. Integrated street-furniture designs blend radios, power modules, and backhaul links into aesthetically pleasing housings, thereby satisfying municipal ordinances. Although outdoor grids remain the dominant revenue stream, the rising momentum in indoor grids underscores the market's dual-track growth narrative.
4G/LTE radios comprised 50.32% of 2025 shipments, equivalent to 1.41 million units in the Asia Pacific small cell tower market size, reflecting operators' preference for maximizing existing spectrum allocations. Yet 5G radios are expanding at an 7.98% CAGR as carriers introduce mid-band and mmWave layers that support multi-gigabit peak throughput. Combo radios that deliver dual-standard coverage preserve site rent outlays and accelerate user migration.
Multi-technology platform adoption also addresses the realities of device mix. In late 2025, 5G smartphone penetration sits below 45% in many Southeast Asian markets, compelling operators to retain 4G anchor links for voice services and IoT endpoints. Gradual sunset plans for 3G free additional spectrum, enabling carriers to refarm bandwidth for 5G NR, thus reinforcing demand for software-upgradable radios.
Complete Report Scope:
- By Application
- Outdoor
- Indoor
- By Network Technology
- 3G
- 4G/LTE
- 5G
- By Ownership Model
- Operator-deployed
- Neutral-host
- Private enterprises
- By Deployment Location
- Urban
- Suburban
- Rural
- By Country
- China
- South Korea
- Japan
- India
- South-East Asia
- Rest of Asia Pacific
List of Companies Covered in this Report:
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- ZTE Corporation
- Samsung Electronics Co., Ltd.
- Parallel Wireless Inc.
- Airspan Networks Inc.
- Baicells Technologies Co., Ltd.
- NEC Corporation
- Comba Telecom Systems Holdings Limited
- Fujitsu Limited
- JMA Wireless
- CommScope Holding Company, Inc.
- Mavenir Systems, Inc.
- Rakuten Symphony, Inc.
- Qucell Networks Co., Ltd.
- ip.access Ltd.
- Corning Incorporated
- Sercomm Corporation
- Dali Wireless, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid surge in mobile data traffic and densification requirements
- 4.2.2 Accelerated 5G rollout timelines across Asia Pacific
- 4.2.3 Government initiatives and spectrum policies supporting small cell deployments
- 4.2.4 Emergence of private 5G networks in manufacturing corridors
- 4.2.5 AI-powered self-optimizing networks lowering OPEX for densification
- 4.3 Market Restraints
- 4.3.1 Complex site acquisition and permitting hurdles
- 4.3.2 High upfront capital expenditure for dense deployments
- 4.3.3 Interference management in shared and unlicensed spectrum bands
- 4.3.4 Semiconductor supply-chain disruptions delaying roll-outs
- 4.4 Impact of Macroeconomic Factors
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Intensity of Competitive Rivalry
- 4.8.5 Threat of Substitutes
- 4.9 Analysis of 5G Roadmap in Asia Pacific
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Outdoor
- 5.1.2 Indoor
- 5.2 By Network Technology
- 5.2.1 3G
- 5.2.2 4G/LTE
- 5.2.3 5G
- 5.3 By Ownership Model
- 5.3.1 Operator-deployed
- 5.3.2 Neutral-host
- 5.3.3 Private enterprises
- 5.4 By Deployment Location
- 5.4.1 Urban
- 5.4.2 Suburban
- 5.4.3 Rural
- 5.5 By Country
- 5.5.1 China
- 5.5.2 South Korea
- 5.5.3 Japan
- 5.5.4 India
- 5.5.5 South-East Asia
- 5.5.6 Rest of Asia Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Huawei Technologies Co., Ltd.
- 6.4.2 Telefonaktiebolaget LM Ericsson
- 6.4.3 Nokia Corporation
- 6.4.4 ZTE Corporation
- 6.4.5 Samsung Electronics Co., Ltd.
- 6.4.6 Parallel Wireless Inc.
- 6.4.7 Airspan Networks Inc.
- 6.4.8 Baicells Technologies Co., Ltd.
- 6.4.9 NEC Corporation
- 6.4.10 Comba Telecom Systems Holdings Limited
- 6.4.11 Fujitsu Limited
- 6.4.12 JMA Wireless
- 6.4.13 CommScope Holding Company, Inc.
- 6.4.14 Mavenir Systems, Inc.
- 6.4.15 Rakuten Symphony, Inc.
- 6.4.16 Qucell Networks Co., Ltd.
- 6.4.17 ip.access Ltd.
- 6.4.18 Corning Incorporated
- 6.4.19 Sercomm Corporation
- 6.4.20 Dali Wireless, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need assessment