

|
시장보고서
상품코드
2124318
마이크로러닝 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Microlearning - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
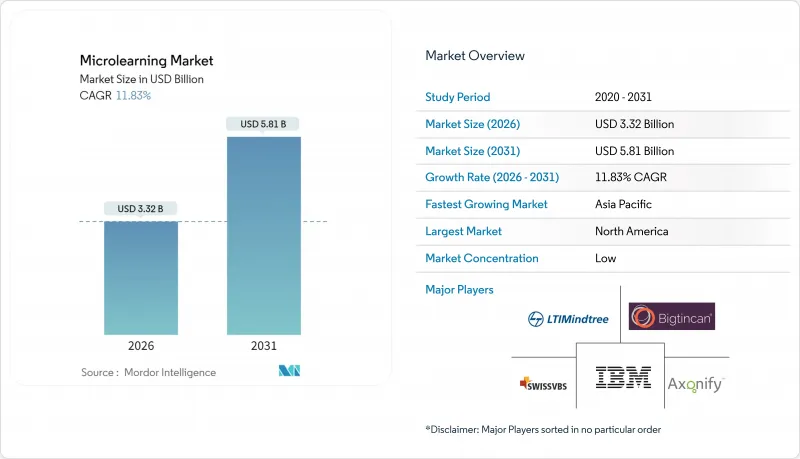
에 의하면, 마이크로러닝 시장 규모는 2026년에 33억 2,000만 달러로 추정되고, 2031년까지 연평균 복합 성장률(CAGR) 11.83%로 확대될 전망이며, 58억 1,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 구성 요소별(솔루션 및 서비스), 조직 규모별(대기업 및 중소기업), 도입 형태별온프레미스 및 클라우드), 최종 사용자별(소매, 제조, 통신 및 IT, 기타), 제공 형식별(동영상 기반 학습, 대화형 시뮬레이션, 팟캐스트 및 오디오북, 기타), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 마이크로러닝 시장 동향 및 인사이트
모바일 우선 직원 학습 플랫폼의 보급
현재 약 27억 명의 현장 직원 및 데스크리스 직원이 일상 업무에서 스마트폰에 의존하고 있으며, iOS 및 Android에서 기본적으로 실행되는 마이크로러닝 솔루션의 도입으로 데스크톱 환경으로 인한 병목 현상이 해소되고 있습니다. 음료 체인 ‘Chatime’은 근무 시작 전 브리핑 시간에 5분 미만의 모듈을 제공함으로써 수강생 이용률 91%를 달성했습니다. 또한 ‘Pet Supermarket’도 유사한 방식을 통해 79%의 수료율을 기록하며 이직률을 15% 감소시켰습니다. AWS의 예측에 따르면, 아시아태평양에서는 2025년까지 57억 건의 디지털 교육이 필요할 것으로 예상되며, 이러한 규모를 실현할 수 있는 것은 비동기형 모바일 제공 방식뿐입니다. 5G 커버리지가 확대됨에 따라 스마트폰에서 지연 없는 동영상 및 시뮬레이션이 가능해졌으며, 현장 기술자나 임상의에게도 몰입형 형식이 실용화되고 있습니다.
기술 기반의 적시(Just-in-Time) 교육에 대한 수요 증가
연간 교육 일정에서 역할 기반 교육으로 전환하는 기업이 늘어나고 있는 것이 마이크로러닝 시장 수요를 뒷받침하고 있습니다. 새로운 장비, 규정 또는 제품 기능을 습득해야 하는 직원들에게 반나절 워크숍보다 5분간의 복습이 더 유용합니다. 범용 커리큘럼을 기술 기반 학습 경로로 대체할 경우, 사내 이동 및 이직률이 최대 3배까지 향상된다는 사실이 입증되었습니다. 모든 모듈에 역량 관련 메타데이터를 부여함으로써, ERP나 CRM 시스템이 워크플로우의 변화를 감지하는 순간 플랫폼이 관련 컨텐츠를 표시할 수 있게 되어, 신입 사원의 생산성 달성까지 걸리는 시간을 단축할 수 있습니다.
레거시 컨텐츠를 마이크로 모듈로 변환할 때 발생하는 막대한 비용
Articulate사의 벤치마크 조사에 따르면, 기존 과정 1개를 마이크로 유닛으로 변환하는 데 10,000-5만 달러의 비용이 소요되며, 완성된 1시간당 최대 184시간의 개발 시간이 필요하다는 사실이 밝혀졌습니다. 100개의 코스로 구성된 라이브러리를 보유한 기업은 수년에 걸친 노력을 기울여야 하며, 레거시 플랫폼과 마이크로러닝 시장 플랫폼을 병행하여 운영해야 합니다. 전문 지식을 갖춘 인력 부족도 진행 속도를 더욱 늦추고 있기 때문에 구매자들은 리드 타임을 대폭 단축할 수 있는 ‘컨텐츠 애즈 어 서비스(CaaS)’ 번들을 제공하는 벤더를 선호하는 경향이 있지만, 이러한 서비스에는 업계 특유의 미묘한 차이가 반영되지 않을 가능성이 있습니다.
부문 분석
2025년 매출의 68.19%는 솔루션 라이선스에서 발생했으나, 서비스 부문은 2031년까지 연평균 성장률(CAGR) 13.43%로 성장하여 마이크로러닝 시장 전체를 능가할 것으로 예측됩니다. 조직이 플랫폼 전환을 진행함에 따라 컨텐츠 감사, 통합, 변경 관리를 외부에 위탁하는 경향이 강해지고 있으며, 자문 서비스와 기술을 세트로 제공하는 벤더가 선택되기 쉬워지고 있습니다. 컨설팅 계약에서는 역량 매핑, 학습 경로 재설계, API 구성이 이루어지는 반면, 지원 계약에서는 지속적인 업그레이드 및 헬프데스크 이용이 제공되어, 이는 예측 가능한 연간?常수익으로 이어집니다.
많은 대기업은 100개가 넘는 레거시 과정 카탈로그를 보유하고 있어, 사내 팀만으로는 신속하게 재작성하기 어려운 업무 부담이 되고 있습니다. Skillsoft나 Cornerstone과 같은 벤더들은 현재 ‘컨텐츠-어즈-어-서비스(CaaS)’를 포지셔닝하며, 도입 기간을 18개월에서 6개월로 단축함으로써 마이크로러닝이 학습의 깊이를 희생시킨다는 우려에 대응하고 있습니다. 그 결과, 전문 서비스 파이프라인이 확대되어 현금 흐름이 안정화되고 고객 락인 효과가 강화되고 있습니다.
2025년에는 대기업이 마이크로러닝 시장의 54.72% 점유율을 차지했으며, 더 큰 인재 개발(L&D) 예산과 IT 지원을 활용했습니다. 그러나 클라우드 구독을 통해 초기 인프라 비용이 절감됨에 따라 중소기업(SME) 시장은 2031년까지 연평균 14.59%의 성장률을 보일 것으로 예측됩니다. EdApp이나 TalentCards의 프리미엄 플랜을 통해 기업은 10명의 사용자로 시범 도입이 가능하며, AI 저작 기능을 통해 PDF나 표준 작업 절차서(SOP)를 모바일 호환 모듈로 변환할 수 있어 교육 설계의 병목 현상이 해소됩니다.
OECD 조사에 따르면, 유럽의 중소기업은 매출의 불과 1.2%만을 교육에 할당하고 있어, 저비용 고효율의 접근 방식이 지지를 받고 있습니다. 그러나 중소기업의 컨텐츠 대부분은 학습 전문가가 아닌 해당 분야 전문가에 의해 제작되어, 교육적 격차가 발생할 위험이 있습니다. 이에 대응하여 각 벤더사는 템플릿을 활용한 스토리보드 및 자동 평가 생성 기능을 제공함으로써, 예산을 늘리지 않고도 마이크로러닝 시장 경험을 성인 학습의 원칙에 부합하도록 하고 있습니다.
지역별 분석
북미는 2025년 매출의 37.61%를 차지했습니다. LMS 보급률이 높고, 벤더가 밀집해 있으며, 은행 및 의료 분야의 엄격한 규제로 인해 안정적이고 지속적인 지출이 예상됩니다. FFIEC가 2024년에 발표한 ‘은행 비밀법’ 지침 개정안에서는 적응형 및 역할 기반 교육이 강조되었으며, 이는 컴플라이언스 업무 흐름에서 마이크로러닝 솔루션의 유효성을 입증했습니다. 사모펀드의 관심은 코너스톤(Cornerstone)의 52억 달러 규모 비공개화 거래로 정점에 달했으며, 이는 향후 업계 재편에 대한 확신을 보여줍니다. 시장 포화가 임박한 역풍으로 작용하고 있으므로, 향후 성장은 AI를 통한 개인화 및 스킬 인텔리전스 모듈의 업셀에 달려 있습니다.
아시아태평양에서는 스마트폰 보급과 정부의 기술 향상 의무화가 맞물려 연평균 성장률(CAGR) 14.81%라는 가장 높은 성장률을 나타낼 것으로 예측됩니다. 싱가포르의 ‘디지털 엔터프라이즈 블루프린트’는 2025년까지 중소기업의 기술 도입률을 95%로 끌어올리는 것을 목표로 하고 있으며, 이미 2,000명의 근로자를 양성한 AI 과정에 자금을 지원하고 있습니다. 인도네시아의 ‘카르투 프라케르자’에는 1,430만 명의 시민이 등록되어 있으며, 단기 디지털 기술 강좌에 대해 32조 루피아(21억 달러)의 보조금이 지급되고 있습니다. AWS의 추정에 따르면, 2025년까지 이 지역의 8억 1,900만 명의 근로자가 새로운 디지털 기술을 필요로할 것으로 예상되며, 이는 마이크로러닝 시장에 막대한 잠재력이 있음을 시사합니다. 지역별 데이터 상주 요건으로 인해 인프라 비용은 상승하지만, 국내에 데이터센터를 보유한 벤더는 선구자로서의 우위를 점하고 있습니다.
유럽의 동향은 GDPR(EU 개인정보보호규정)에 의해 형성되고 있으며, 이 법에서는 학습 기록을 개인 데이터로 분류하고 있기 때문에 벤더는 서버를 유럽 경제 지역(EEA) 내에 설치해야 할 의무가 있습니다. Valamis와 같은 현지 기업들은 지역 내 호스팅을 활용하여 공공 부문 고객을 확보하고 있는 반면, 세계 기업들은 규제 준수를 위해 프랑크푸르트나 더블린 지역에 투자하고 있습니다. 독일의 이중 교육 모델에서는 견습생이 현장 순환 근무 사이에 이론 학습으로 마이크로러닝을 활용하도록 장려되고 있으며, 프랑스의 의학 교육 요건도 의료 분야 수요를 끌어올리고 있습니다. 라틴아메리카, 중동 및 아프리카는 여전히 초기 단계이지만, 다국적 기업들이 자회사 전반에 걸쳐 표준화된 프로그램을 전개하고, 출장 비용이나 대면 학습으로 인한 업무 중단 시간을 피하기 위해 마이크로러닝 시장을 활용하고 있어 미래가 기대됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the microlearning market size reached USD 3.32 billion in 2026 and is forecast to advance at an 11.83% CAGR to USD 5.81 billion by 2031.
This report is Segmented by Component (Solution, and Services), Organization Size (Large Enterprises, and Small and Medium-Sized Enterprises), Deployment Mode (On-Premise, and Cloud), End User (Retail, Manufacturing, Telecom and IT, and More), Delivery Format (Video-Based Learning, Interactive Simulation, Podcast and Audiobook, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Microlearning Market Trends and Insights
Proliferation of Mobile-First Workforce Learning Platforms
Roughly 2.7 billion frontline and deskless employees now rely on smartphones for daily tasks, and adoption of microlearning market solutions that launch natively on iOS and Android removes the desktop bottleneck. Beverage chain Chatime reached 91% learner uptake with sub-5-minute modules accessed during pre-shift briefings, while Pet Supermarket logged 79% completion rates and cut turnover by 15% using similar tactics. AWS projects Asia Pacific will require 5.7 billion digital training interventions by 2025, a scale only feasible with asynchronous mobile delivery. Broader 5G coverage is enabling latency-free video and simulation on phones, making immersive formats viable for field technicians and clinicians.
Growing Need for Skills-Based, Just-In-Time Training
Enterprises moving away from annual course calendars toward role-triggered interventions are fuelling microlearning market demand. Workers asked to master new equipment, regulations, or product features benefit more from a 5-minute refresher than a half-day workshop. Internal mobility and retention gains of up to 3 times have been documented when skills-based pathways replace generic curricula. Tagging every module with competency metadata lets platforms surface content the instant an ERP or CRM system detects a workflow change, shortening time-to-productivity for new hires.
High Cost of Transforming Legacy Content into Micro-Modules
Articulate benchmarking shows converting a single traditional course into micro-units' costs USD 10,000 to USD 50,000 and demands up to 184 development hours per finished hour. Enterprises with 100-course libraries confront multiyear efforts that force them to run legacy and microlearning market platforms in parallel. Scarce subject-matter experts further slow progress, prompting buyers to favour vendors offering content-as-a-service bundles that slash lead times but may lack industry-specific nuance.
Other drivers and restraints analyzed in the detailed report include:
- Gamification Enhancing Learner Engagement and Retention
- AI-Driven Personalization of Micro-Content
- Difficulty in Measuring ROI Versus Traditional L and D Approaches
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solution licenses generated 68.19% of 2025 revenue, yet services are projected to outstrip the broader microlearning market at a 13.43% CAGR to 2031. As organizations re-platform, they increasingly outsource content audits, integration, and change management, favouring vendors that bundle advisory with technology. Consulting engagements map competencies, redesign learning pathways, and configure APIs, while support contracts provide ongoing upgrades and helpdesk access that convert into predictable annual recurring revenue.
Many large enterprises maintain catalogues exceeding 100 legacy courses, a workload internal teams cannot re-author quickly. Vendors such as Skillsoft and Cornerstone now position content-as-a-service to shrink deployment from 18 months to 6 months, addressing worries that microlearning sacrifices depth. The result is expanding professional-services pipelines that stabilize cash flows and deepen customer lock-in.
Large enterprises held 54.72% of microlearning market share in 2025, leveraging bigger L&D budgets and IT support. However, SMEs are expected to grow at 14.59% through 2031 as cloud subscriptions remove upfront infrastructure costs. Freemium tiers from EdApp or TalentCards let firms pilot with ten users, while AI authoring converts PDFs and SOPs into mobile-ready modules, eliminating instructional-design bottlenecks.
The OECD found European SMEs allocate just 1.2% of revenue to training, so low-cost, high-impact interventions resonate. Yet subject-matter experts, not learning professionals, create most small-business content, risking pedagogical gaps. Vendors counter with template-driven storyboards and automated assessment generation that align microlearning market experiences with adult-learning principles without inflating budgets.
Complete Report Scope:
- By Component
- Solution
- Services
- Consulting and Implementation
- Support and Maintenance
- By Organization Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Deployment Mode
- On-Premise
- Cloud
- By End User
- Retail
- Manufacturing
- Banking, Financial Services and Insurance
- Telecom and IT
- Healthcare and Life Sciences
- Logistics
- Education
- Media and Entertainment
- By Delivery Format
- Video-Based Learning
- Interactive Simulations
- Podcasts and Audiobooks
- Quizzes and Assessments
- Infographics
- Micro-Blogs and Text Nuggets
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Southeast Asia
- Rest of Asia Pacific
- Middle East
- GCC
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Rest of Africa
- North America
Geography Analysis
North America generated 37.61% of 2025 revenue. High LMS penetration, dense vendor clusters, and stringent banking and healthcare regulations ensure steady recurring spend. The FFIEC's 2024 update to Bank Secrecy Act guidance emphasized adaptive, role-based training, validating microlearning solutions for compliance workflows. Private-equity interest peaked with Cornerstone's USD 5.2 billion take-private, signalling confidence in continued consolidation. Saturation is a looming headwind, so growth now hinges on upselling AI personalization and skills-intelligence modules.
Asia Pacific is forecast to record the fastest 14.81% CAGR as smartphone ubiquity meets government upskilling mandates. Singapore's Digital Enterprise Blueprint targets 95% SME tech adoption by 2025, funding AI courses that already trained 2,000 workers. Indonesia's Kartu Prakerja enrolled 14.3 million citizens, supplying IDR 32 trillion (USD 2.1 billion) in grants for bite-sized digital skills courses. AWS estimates 819 million regional workers need new digital abilities by 2025, heralding massive microlearning market potential. Regional data-residency rules raise infrastructure costs, but vendors with in-country data centers gain first-mover advantage.
Europe's trajectory is shaped by GDPR, which classifies learning records as personal data, compelling vendors to keep servers inside the European Economic Area. Homegrown providers such as Valamis leverage regional hosting to win public-sector accounts, while global players invest in Frankfurt and Dublin regions to comply. Germany's dual-training model encourages apprentices to use microlearning for theory between shop-floor rotations, and France's medical-education requirements are boosting demand in healthcare. Latin America, the Middle East, and Africa remain early-stage but show promise as multinationals deploy standardized programs across subsidiaries, using the microlearning market to avoid travel costs and classroom downtime.
- Axonify Inc.
- Cornerstone OnDemand Inc.
- IBM Corporation
- Bigtincan Holdings Ltd.
- Saba Software Inc.
- iSpring Solutions Inc.
- Epignosis LLC
- Qstream Inc.
- Mindtree Ltd.
- SwissVBS
- Skillsoft Corp.
- Docebo Inc.
- Articulate Global LLC
- EdApp (SafetyCulture)
- Gnowbe Pte. Ltd.
- TalentCards (Epignosis)
- Udemy Business
- Pluralsight LLC
- Valamis Group Oy
- Absorb LMS Software Inc.
- LearnUpon Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of Mobile-First Workforce Learning Platforms
- 4.2.2 Growing Need for Skills-Based, Just-in-Time Training
- 4.2.3 Gamification Enhancing Learner Engagement and Retention
- 4.2.4 AI-Driven Personalization of Micro-Content
- 4.2.5 Integration of Microlearning into Flow-of-Work Productivity Tools
- 4.2.6 Regulatory Push for Continuous Compliance Training in Highly Regulated Industries
- 4.3 Market Restraints
- 4.3.1 High Cost of Transforming Legacy Content into Micro-Modules
- 4.3.2 Difficulty in Measuring ROI Versus Traditional L&D Approaches
- 4.3.3 Data-Privacy and Security Concerns in Cloud-Based Learning Platforms
- 4.3.4 Content Fatigue from Over-Fragmentation of Learning Assets
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solution
- 5.1.2 Services
- 5.1.2.1 Consulting and Implementation
- 5.1.2.2 Support and Maintenance
- 5.2 By Organization Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium-Sized Enterprises
- 5.3 By Deployment Mode
- 5.3.1 On-Premise
- 5.3.2 Cloud
- 5.4 By End User
- 5.4.1 Retail
- 5.4.2 Manufacturing
- 5.4.3 Banking, Financial Services and Insurance
- 5.4.4 Telecom and IT
- 5.4.5 Healthcare and Life Sciences
- 5.4.6 Logistics
- 5.4.7 Education
- 5.4.8 Media and Entertainment
- 5.5 By Delivery Format
- 5.5.1 Video-Based Learning
- 5.5.2 Interactive Simulations
- 5.5.3 Podcasts and Audiobooks
- 5.5.4 Quizzes and Assessments
- 5.5.5 Infographics
- 5.5.6 Micro-Blogs and Text Nuggets
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia and New Zealand
- 5.6.4.6 Southeast Asia
- 5.6.4.7 Rest of Asia Pacific
- 5.6.5 Middle East
- 5.6.5.1 GCC
- 5.6.5.2 Turkey
- 5.6.5.3 Israel
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 North Africa
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Axonify Inc.
- 6.4.2 Cornerstone OnDemand Inc.
- 6.4.3 IBM Corporation
- 6.4.4 Bigtincan Holdings Ltd.
- 6.4.5 Saba Software Inc.
- 6.4.6 iSpring Solutions Inc.
- 6.4.7 Epignosis LLC
- 6.4.8 Qstream Inc.
- 6.4.9 Mindtree Ltd.
- 6.4.10 SwissVBS
- 6.4.11 Skillsoft Corp.
- 6.4.12 Docebo Inc.
- 6.4.13 Articulate Global LLC
- 6.4.14 EdApp (SafetyCulture)
- 6.4.15 Gnowbe Pte. Ltd.
- 6.4.16 TalentCards (Epignosis)
- 6.4.17 Udemy Business
- 6.4.18 Pluralsight LLC
- 6.4.19 Valamis Group Oy
- 6.4.20 Absorb LMS Software Inc.
- 6.4.21 LearnUpon Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


