|
시장보고서
상품코드
2124323
EaaS(Energy-as-a-Service) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Energy As A Service (EaaS) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
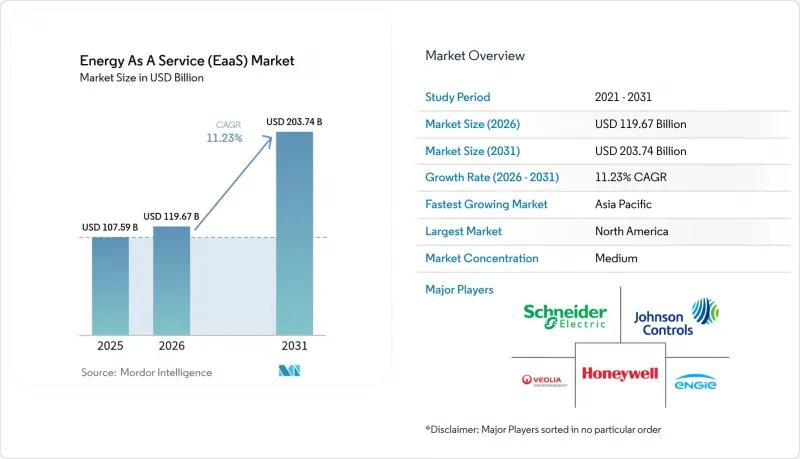
에 의하면, EaaS(Energy-as-a-Service) 시장 규모는 2025년에 1,075억 9,000만 달러로 평가되었고, 2026년 1,196억 7,000만 달러에서 2031년까지 2,037억 4,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 11.23%를 기록할 전망입니다.
본 보고서는 서비스 유형별(에너지 공급 서비스, 마이크로그리드-어-서비스, 에너지 인프라 서비스 등), 서비스 제공 모델별(사용량 기반 과금제, 리스 및 렌탈 모델 등), 기술별(분산형 발전, 전기차 충전 인프라 등), 최종 사용자별(상업 및 산업) 및 지역별(북미, 유럽, 아시아태평양, 남미 등)로 분류되어 있습니다.
세계의 EaaS(Energy-as-a-Service) 시장 동향 및 인사이트
기업의 탈탄소화 의무와 스코프 3에 대한 압력
캘리포니아주 SB 253 법안 등 온실가스 공개 의무화 규정에 따라, 매출액이 10억 달러를 초과하는 기업은 2027년부터 스코프 3 배출량 보고가 의무화되었으며, 이에 따라 조달 부서는 재생 가능 전력 및 검증된 배출량 산정을 우선시하고 있습니다. 다국적 기업 구매자들은 이러한 요건을 공급망 전체로 확대하고 있으며, 친환경 전력, 에너지 효율화, 투명한 보고를 결합한 턴키 방식의 ‘EaaS(Energy-as-a-Service)’ 시장 솔루션에 대한 수요를 높이고 있습니다. 금융 기관들도 대출 결정에 기후 리스크를 반영하고 있기 때문에 기업들은 서비스형 에너지 계약을 보다 친환경적인 대차대조표를 구축할 수 있는 길을 열어주는 편리한 ‘에너지 애즈 어 서비스(EaaS)’ 시장으로 인식하고 있습니다. 사내에 지속가능성 담당 직원을 두고 있지 않은 중견 기업들은 기술 선정과 모니터링을 모두 외부에 위탁할 수 있기 때문에 가장 큰 혜택을 보고 있습니다. 공시 기한이 다가옴에 따라 ‘EaaS(Energy-as-a-Service)’ 시장의 잠재 고객층은 모든 주요 부문에 걸쳐 확대되고 있습니다.
송전망의 불안정화가 마이크로그리드 도입을 촉진
노후화된 인프라, 이상 기후, 데이터센터의 확장이 기존 송전망에 부담을 주고 있습니다. 국제에너지기구(IEA)의 추산에 따르면, 2040년까지 8,000만 km의 송전선 개보수 또는 교체가 필요할 것으로 예측됩니다. 마이크로그리드는 중요한 부하를 독립적으로 운영하여 자가 공급을 가능하게 함으로써 정전 위험을 완화합니다. 캘리포니아주 에너지 위원회가 자금을 지원한 실증 실험에서는 정전 시에도 가동 시간을 유지하면서 에너지 비용을 20-60% 절감할 수 있음이 입증되었습니다. 기업들은 현재 마이크로그리드를 단순한 백업 자산이 아닌 시설 관리 전략에 통합된 구성 요소로 인식하고 있으며, 서비스 제공업체들은 수년에 걸친 성과 연계형 계약을 바탕으로 이를 제공합니다. 규제상의 취급은 관할 구역에 따라 다르지만, 성과 연계형 요금이나 계통 연계료 인하와 같은 정책 실험을 통해 ‘EaaS(Energy-as-a-Service)’ 시장에서의 새로운 수요 개척이 진행되고 있습니다.
장기 계약에 따른 락인(lock-in) 우려
표준적인 에너지 효율 성과 계약의 기간은 5-20년에 달하기 때문에 기술의 노후화나 운영상의 유연성에 대한 우려가 커지고 있습니다. 미국 에너지부는 고객 가치 보호 및 감사 대응 준비를 위해 엄격한 측정과 검증을 실시할 것을 권고하고 있습니다. 서비스 제공업체는 계약 기간 중 업그레이드 조항이나 계약 해지 기간을 설정하는 사례가 늘고 있지만, 이러한 조항은 가격 상승으로 이어질 가능성이 있습니다. 그 결과, 위험 회피 성향이 강한 잠재 고객은 계약 체결을 미룰 가능성이 있으며, 이로 인해 ‘EaaS(Energy-as-a-Service)’ 시장의 당면한 성장 가능성이 저하될 우려가 있습니다.
부문 분석
에너지 공급 서비스는 2025년 매출의 39.12%를 차지했으며, 이는 기업들이 복잡한 조달 프로세스를 관리하지 않고도 경쟁력 있는 가격으로 저탄소 전력을 확보하는 것을 우선시하고 있음을 반영합니다. 이 부문에서 ‘EaaS(Energy-as-a-Service)’가 시장 점유율에서 우위를 유지하고 있는 것은 전력 구매 번들 계약, 헤지 전략, 그리고 재생에너지 크레딧 관리 덕분입니다. ‘마이크로그리드-어-서비스(Microgrid-as-a-Service)’는 병원, 공항, 제조업 단지 등이 전력망 장애 시 아일랜드 모드에서의 내장애성을 요구함에 따라, 2031년까지 14.05%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 마이크로그리드용 ‘EaaS(Energy-as-a-Service)’ 시장 규모는 배터리 가격 하락과 인허가 절차 간소화에 힘입어 2026-2031년 2배 이상으로 성장할 것으로 예측됩니다. 운영·유지보수(O&M) 및 수명 주기 전반에 걸친 업그레이드를 포괄하는 서비스는 안정성이 높은 지속적인 수익원을 창출하여 공급업체의 입지를 더욱 공고히할 것입니다.
이와 동시에, 고객이 발전, 에너지 저장 및 첨단 제어 시스템의 원활한 통합을 요구함에 따라 에너지 인프라 서비스(엔지니어링, 계통 연계, 자산 모니터링)의 중요성이 높아지고 있습니다. ‘에너지-어즈-어-서비스(Energy-as-a-Service)’ 시장에서는 단일 계약으로 공급, 효율 최적화, 현장 발전을 아우르는 교차 판매 기회가 증가하고 있습니다. 탄탄한 소프트웨어 스택과 전국 규모의 현장 서비스 팀을 보유한 공급업체는 통합형 서비스를 통해 창출되는 시너지 효과를 반영하여 높은 평가를 받고 있습니다.
서비스 이용료형 계약은 변동이 심한 에너지 비용을 단일하고 예측 가능한 월별 비용 항목으로 전환하기 때문에 2025년 매출의 39.55%를 차지했습니다. 이러한 계약에는 일반적으로 성과 보장이 포함되어 있으며, 공급업체에 대한 보상이 실현된 절감액과 연동되므로 고객의 신뢰를 강화하고 있습니다. 리스 및 렌탈 모델은 계약 기간 단축과 간소화된 대차대조표 외 처리를 제공함으로써 연평균 성장률(CAGR) 18.02%로 성장세를 보이고 있으며, 리스 기간이 제한된 임차인이나 부동산 관리자에게 매력적입니다. ‘EaaS(Energy-as-a-Service)’ 업계에서는 향후 소유권 취득을 목표로 하는 지자체 대상으로 ‘건설·소유·운영·양도(BOOT)’ 방식이 때때로 채택되기도 하지만, 민간 부문 도입에서는 구독형 플랜이 주류를 이루고 있습니다. 기존의 ESCO 계약과 달리, 현대의 ‘서비스 대가형’ 계약에서는 수요 반응(Demand Response) 참여, 전기차 충전, 탄소 보고와 같은 모듈식 추가 서비스를 중시하고 있습니다.
성과 연계형 계약은 보장된 절감액을 바탕으로 수년에 걸쳐 상환할 수 있도록 허용하는 법적 체계에 뒷받침되어, 공공 및 기관 투자자 분야에서 여전히 널리 보급되어 있습니다. 기존의 ESCO 계약과 비교하여, 현대의 ‘Pay-for-Service’ 계약에서는 수요 반응(Demand Response) 참여, 전기차 충전, 탄소 보고 대시보드와 같은 모듈식 추가 기능이 중시되고 있습니다. 이러한 진화를 통해 ‘Energy as a Service’ 시장은 일회성 개보수 계획이 아닌, 확장성이 뛰어나고 기술을 활용한 솔루션으로서의 입지가 강화되고 있습니다.
지역별 분석
북미는 2025년, IRA(인플레이션 억제법)에 따른 3,700억 달러 규모의 경기 부양책, 주 차원의 에너지 저장 의무화, 그리고 성숙한 기업 조달 프로그램의 지원에 힘입어 전 세계 매출의 42.18%를 차지했습니다. ‘온실가스 감축 기금’은 저금리 자금을 소외된 지역사회로 유도하여, 고객 기반을 포춘 500대 기업 이외의 영역으로 확대되고 있습니다. 캐나다에서는 탄소 가격 책정 및 주 차원의 청정 에너지 입찰을 통해 지역의 성장세가 더욱 강화되고 있습니다. 스마트 계량 표준의 국경 간 상호 운용성과 오픈 데이터 정책 덕분에, EaaS(Energy-as-a-Service) 시장에 진출한 기업들의 플랫폼 확장성이 더욱 가속화되고 있습니다.
아시아태평양은 급속한 도시화와 지속적인 공공 부문 투자를 반영하여 2031년까지 연평균 성장률(CAGR)이 16.32%로 가장 빠른 성장세를 기록하고 있습니다. 중국의 여러 기가와트 규모의 분산형 발전 계획과 인도의 송전망 확충은 턴키 방식의 마이크로그리드 및 에너지 저장 솔루션에 큰 비즈니스 기회를 제공합니다. 일본과 한국에서는 첨단 예측 유지보수 분석과 결합된 재생에너지의 높은 보급률을 실현하고 있으며, 아세안(ASEAN) 국가 전체에서 재현 가능한 모델을 확립하고 있습니다. 일부 관할 구역에서는 자금 조달 비용이 여전히 높은 수준이지만, 혼합 금융 제도와 수출 신용 지원을 통해 위험이 완화되어 지역 EaaS(Energy-as-a-Service) 시장의 활성화가 촉진되고 있습니다.
유럽은 ‘Fit-for-55’ 탈탄소화 목표에 힘입어 여전히 큰 점유율을 유지하고 있습니다. 이 목표에 따라 배출량이 많은 기업은 재생 에너지 및 에너지 효율 보장을 계약해야 할 의무가 있습니다. 통합된 데이터 공유 체계를 통해 여러 국가에 걸친 사업 전개가 간소화되고 있지만, 각 회원국은 계량기 뒤쪽의 인센티브 설계에 대해 재량권을 보유하고 있어 실행상 복잡성을 초래하고 있습니다. 남미, 중동 및 아프리카는 전 세계 매출에서 차지하는 비중은 적지만 꾸준히 확대되고 있습니다. 환율 변동이나 정책의 불확실성이 도입을 저해하는 요인으로 작용하는 반면,모로코의 일일 82만 2,000m³ 규모 해수 담수화 플랜트(35년 기간의 양도 계약에 따라 태양광 발전과 에너지 저장을 결합한 시설)와 같은 획기적인 프로젝트는 자금 조달이 가능한 ‘에너지-어-서비스(Energy-as-a-Service)’ 시장 구조의 실현 가능성을 입증하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the energy as a service market size was valued at USD 107.59 billion in 2025 and estimated to grow from USD 119.67 billion in 2026 to reach USD 203.74 billion by 2031, at a CAGR of 11.23% during the forecast period (2026-2031).
This report is Segmented by Service Type (Energy Supply Services, Microgrid-As-A-Service, Energy Infrastructure Services, and More), Service-Delivery Model (Pay-For-Service, Leasing and Rental Models, and More), Technology (Distributed Generation, EV-Charging Infrastructure, and More), End User (Commercial and Industrial), and Geography (North America, Europe, Asia-Pacific, South America, and More).
Global Energy As A Service (EaaS) Market Trends and Insights
Corporate Decarbonization Mandates & Scope-3 Pressure
Mandatory greenhouse-gas disclosure rules, such as California's SB 253, require firms with revenue exceeding USD 1 billion to report Scope 3 emissions starting in 2027, prompting procurement teams to prioritize renewable electricity and verified emissions accounting. Multinational buyers extend these requirements along their supply chains, amplifying demand for turnkey Energy as a Service market solutions that bundle green power, energy efficiency, and transparent reporting. Financial institutions also factor climate risk into lending decisions, so companies perceive service-based energy contracts as a convenient Energy-as-a-Service market that expands the path to greener balance sheets. Mid-sized enterprises lacking in-house sustainability staff benefit the most, outsourcing both technology selection and monitoring. As disclosure deadlines approach, the addressable customer pool for the Energy as a Service market widens across every major sector.
Grid Volatility Driving Microgrid Adoption
Ageing infrastructure, extreme weather, and data center growth stress legacy grids; the International Energy Agency estimates that 80 million km of power lines will need refurbishment or replacement by 2040. Microgrids mitigate outage risk by allowing critical loads to island and self-supply. Demonstrations funded by the California Energy Commission have shown 20-60% energy cost savings while maintaining uptime during blackouts. Corporations now view microgrids not as backup assets, but as integrated components of their facility management strategies, and service providers supply them under multi-year pay-for-performance contracts. Regulatory treatment varies by jurisdiction, yet policy experimentation-such as performance-based tariffs and reduced interconnection fees-continues to unlock new demand pockets for the Energy as a Service market.
Long-Term Contract Lock-In Concerns
Standard Energy Savings Performance Contracts span 5-20 years, raising anxiety about technology obsolescence and operational flexibility. The U.S. Department of Energy advises rigorous measurement and verification to safeguard customer value and audit readiness. Service providers are increasingly inserting mid-term upgrade clauses or opt-out windows, but these features can raise pricing. Consequently, risk-averse prospects may delay signing, reducing immediate growth potential for the Energy as a Service market.
Other drivers and restraints analyzed in the detailed report include:
- Shift from CAPEX to OPEX in Fortune-1000 Facilities
- AI-Driven Energy Analytics Improving ROI
- Cyber-Security Liabilities on Third-Party Assets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Energy Supply Services generated 39.12% of 2025 turnover, reflecting enterprises' priority to secure competitively priced, low-carbon electricity without managing complex procurement processes. Within this segment, the Energy as a Service market share advantage stems from bundled power-purchase arrangements, hedging strategies, and management of renewable certificates. Microgrid-as-a-Service is projected to record the fastest 14.05% CAGR through 2031, as hospitals, airports, and manufacturing parks seek island-mode resiliency during grid disturbances. The Energy as a Service market size for microgrids is projected to more than double between 2026 and 2031, supported by falling battery prices and streamlined permitting. Services covering operations & maintenance, as well as lifecycle upgrades, add sticky recurring revenue streams, further entrenching providers.
In parallel, Energy Infrastructure Services-engineering, interconnection, and asset monitoring-gain importance as clients demand seamless integration of generation, storage, and advanced controls. The Energy as a Service market is seeing rising cross-sell opportunities, where a single contract now spans supply, efficiency optimization, and on-site generation. Providers with deep software stacks and nationwide field service crews command premium valuations, reflecting the synergistic value created by integrated offerings.
Pay-for-service agreements accounted for 39.55% of 2025 revenue, as they transform volatile utility expenses into a single, predictable monthly line item. These contracts typically bundle performance guarantees and align provider compensation with realized savings, reinforcing customer confidence. Leasing & Rental models gain traction at an 18.02% CAGR by offering shorter tenures and simplified off-balance-sheet treatment, which appeals to tenants or property managers with limited lease horizons. While the Energy as a Service industry occasionally employs Build-Own-Operate-Transfer structures for municipalities seeking eventual ownership, subscription plans are the dominant form of private-sector uptake.to legacy ESCO arrangements, modern Pay-for-Service contracts emphasize modular add-ons, such as demand-response participation, electric vehicle charging, and carbon reporting
Performance-based contracts remain prevalent in the public and institutional arena, supported by statutory frameworks that authorize multi-year repayment from guaranteed savings. Compared with legacy ESCO arrangements, modern Pay-for-Service contracts emphasize modular add-ons such as demand-response participation, electric-vehicle charging, and carbon-reporting dashboards. This evolution reinforces the Energy as a Service market's positioning as a scalable, tech-enabled solution rather than a one-off retrofit scheme.
Complete Report Scope:
- By Service Type
- Energy Supply Services
- Energy Efficiency and Optimisation Services
- Operation and Maintenance Services
- Energy Infrastructure Services
- Microgrid-as-a-Service
- By Service-Delivery Model
- Pay-for-Service (Subscription)
- Performance-based Contracting (ESCO/EPC)
- Build-Own-Operate-Transfer (BOOT)
- Leasing and Rental Models
- By Technology
- Distributed Generation (Solar PV, Wind, Combined Heat & Power and Fuel Cells)
- Energy Storage (Battery Storage, and Thermal Storage)
- Smart Energy Management & Analytics
- EV-Charging Infrastructure
- By End User
- Commercial (Data Centres, Retail & Shopping Malls, Healthcare Facilities, Educational Institutions, Hospitality and Others)
- Industrial (Heavy Manufacturing, Food & Beverage Processing, Chemicals & Pharmaceuticals, Mining & Metals and Others)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
North America retained 42.18% of global revenue in 2025, powered by the IRA's USD 370 billion stimulus, state-level storage mandates, and mature corporate procurement programs. The Greenhouse Gas Reduction Fund steers low-interest capital to disadvantaged communities, broadening the customer base beyond Fortune 500 enterprises. Canada reinforces regional momentum through carbon pricing and provincial clean-energy auctions. Cross-border interoperability of smart-metering standards and open-data policies further accelerates platform scalability for energy-as-a-service market participants.
The Asia-Pacific region records the fastest growth, with a 16.32% CAGR to 2031, reflecting rapid urbanization and sustained public-sector investment. China's multi-gigawatt distributed-generation schemes and India's transmission build-out unlock substantial opportunities for turnkey microgrid and storage offerings. Japan and South Korea deploy high-penetration renewables paired with advanced predictive maintenance analytics, establishing templates that are replicable across ASEAN nations. Although financing costs remain elevated in certain jurisdictions, blended-finance facilities and export-credit support mitigate risk and catalyze the regional Energy-as-a-Service market.
Europe maintains a sizable share, bolstered by the Fit-for-55 decarbonization targets that compel large emitters to contract for renewable power and energy efficiency guarantees. Harmonized data-sharing frameworks simplify multi-country rollouts, though each member state retains discretion over behind-the-meter incentive design, which introduces execution complexity. South America, the Middle East, and Africa together contribute a modest but growing slice of global revenue. Currency volatility and policy uncertainty temper uptake, yet landmark projects-such as Morocco's 822,000 m3/day desalination plant incorporating solar-plus-storage under a 35-year concession-demonstrate feasibility for bankable Energy as a Service market structures
- Schneider Electric SE
- Engie SA
- Honeywell International Inc.
- Veolia Environnement SA
- Electricite de France (EDF) SA
- Johnson Controls International plc
- Bernhard
- Enel SpA
- Sparkfund
- Siemens AG
- ABB Ltd.
- Centrica Business Solutions
- Ameresco
- NRG Energy
- Shell Energy
- Duke Energy Sustainable Solutions
- Orsted A/S
- TotalEnergies
- E.ON SE
- Brookfield Renewable
- Generate Capital
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Corporate decarbonisation mandates & Scope-3 pressure
- 4.2.2 Grid volatility driving micro-grid adoption
- 4.2.3 Shift from CAPEX to OPEX in Fortune-1000 facilities
- 4.2.4 AI-driven energy analytics improving ROI
- 4.2.5 Inflation Reduction Act & other green-funding pools
- 4.2.6 Rise of C&I battery storage "as-a-service" offers
- 4.3 Market Restraints
- 4.3.1 Long-term contract lock-in concerns
- 4.3.2 Cyber-security liabilities on third-party assets
- 4.3.3 Policy uncertainty on behind-the-meter incentives
- 4.3.4 Inflated WACC on energy infrastructure in EMs
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Service Type
- 5.1.1 Energy Supply Services
- 5.1.2 Energy Efficiency and Optimisation Services
- 5.1.3 Operation and Maintenance Services
- 5.1.4 Energy Infrastructure Services
- 5.1.5 Microgrid-as-a-Service
- 5.2 By Service-Delivery Model
- 5.2.1 Pay-for-Service (Subscription)
- 5.2.2 Performance-based Contracting (ESCO/EPC)
- 5.2.3 Build-Own-Operate-Transfer (BOOT)
- 5.2.4 Leasing and Rental Models
- 5.3 By Technology
- 5.3.1 Distributed Generation (Solar PV, Wind, Combined Heat & Power and Fuel Cells)
- 5.3.2 Energy Storage (Battery Storage, and Thermal Storage)
- 5.3.3 Smart Energy Management & Analytics
- 5.3.4 EV-Charging Infrastructure
- 5.4 By End User
- 5.4.1 Commercial (Data Centres, Retail & Shopping Malls, Healthcare Facilities, Educational Institutions, Hospitality and Others)
- 5.4.2 Industrial (Heavy Manufacturing, Food & Beverage Processing, Chemicals & Pharmaceuticals, Mining & Metals and Others)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 NORDIC Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Schneider Electric SE
- 6.4.2 Engie SA
- 6.4.3 Honeywell International Inc.
- 6.4.4 Veolia Environnement SA
- 6.4.5 Electricite de France (EDF) SA
- 6.4.6 Johnson Controls International plc
- 6.4.7 Bernhard
- 6.4.8 Enel SpA
- 6.4.9 Sparkfund
- 6.4.10 Siemens AG
- 6.4.11 ABB Ltd.
- 6.4.12 Centrica Business Solutions
- 6.4.13 Ameresco
- 6.4.14 NRG Energy
- 6.4.15 Shell Energy
- 6.4.16 Duke Energy Sustainable Solutions
- 6.4.17 Orsted A/S
- 6.4.18 TotalEnergies
- 6.4.19 E.ON SE
- 6.4.20 Brookfield Renewable
- 6.4.21 Generate Capital
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment