|
시장보고서
상품코드
2124381
호흡기질환 검사 시장 : 시장 점유율 분석, 업계 동향과 및 통계, 성장 예측(2026-2031년)Respiratory Disease Testing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
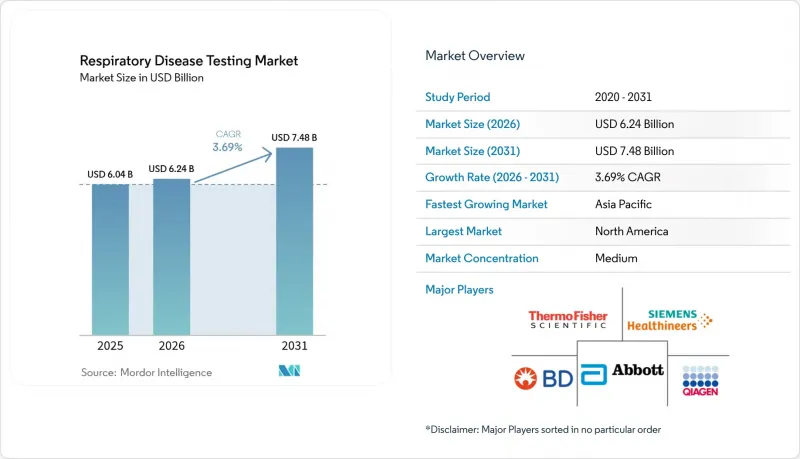
에 의하면, 호흡기질환 검사 시장 규모는 2025년 60억 4,000만 달러로 평가되었고, 2026년 62억 4,000만 달러에서 2031년까지 74억 8,000만 달러로 확대될 것으로 예측되며, 2026-2031년 CAGR 3.69%를 기록할 전망입니다.
본 보고서는 검사 유형별(영상 검사, 분자진단 검사, 기계적 검사, 혈액가스·전해질 검사), 질환별(천식·COPD, 결핵, 폐암 등), 최종 사용자별(병원 및 진료소 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 호흡기질환 검사 시장 동향 및 인사이트
대기질 규제에 따른 수요 급증
중국과 인도 전역에서 미세먼지 규제가 강화됨에 따라, 산업 종사자에 대한 폐기능 검사가 의무화되어 휴대용 기기 및 관련 일회용 소모품의 대량 구매가 촉진되고 있습니다. 기업들은 하드웨어, 교정 서비스, 클라우드 대시보드를 포함한 번들 계약을 선택하고 있으며, 이를 통해 공급업체는 지속적인 수익을 확보할 수 있게 되었습니다. 최신 폐기능 측정기에 내장된 실시간 AI 코칭 덕분에, 인력이 부족한 기술자에 대한 의존도가 낮아지면서 선별 검사가 2선 도시까지 확대되고 있습니다. 이러한 확장으로 인해 고용주의 건강 관리 프로그램에서 호흡기질환 검사 시장 점유율이 확대되고 있습니다. 아시아 주요 거점 근처에 제조 거점을 현지화하는 기기 제조업체들은 비용 측면에서의 우위와 더 신속한 규제 승인을 확보하고 있습니다.
포스트 코로나 시대의 다항목 호흡기 패널 비축
미국의 병원 비축 지원 보조금과 유럽의 일괄 구매로 인해, 2024-2025년 초 분자 검사 패널의 출하량은 5분의 1 가까이 증가했습니다. 2025년 중반까지 소비량은 도입 용량의 약 3분의 2 수준으로 정상화되어, 잉여 재고가 급격히 감소했습니다. 현재 검사 기관들은 설비 가동률을 유지하기 위해 호흡기, 소화기, 중추신경계 표적을 조합한 모듈식 증후군별 검사 패널로 무게중심을 옮기고 있습니다. 이러한 전환으로 인해 공급망의 취약성이 드러났고, 시약 제조업체들은 분석기에서 나오는 실시간 원격 측정 데이터와 연동된 자동 보충 프로그램 도입을 피할 수 없게 되었습니다. 이 서비스 모델은 호흡기질환 검사 시장에서 이제 필수 요건으로 자리 잡고 있습니다.
고도화된 분자진단 패널에 대한 보험 급여 측면의 역풍
CMS는 CPT 87631 호흡기 패널의 2025년 전국 상한액을 12% 인하했고, 민간 보험사들도 사전 승인 기준을 더욱 강화함에 따라 입원 환자 이외의 이용이 억제되고 있습니다. 검사 기관들은 더욱 엄격해진 비용 상한선에 부합하도록 3-5개 표적 검사로 등급을 낮추고 있어, 검체당 절대 수익을 감소시키고 있습니다. 이익률 압박으로 인해, 검사 건수가 많아 간접비를 분산할 수 있는 대규모 병원 네트워크와, 장비 투자 상각을 신속하게 진행할 수 없는 독립 클리닉 간의 격차가 확대되고 있습니다. 의료적 필요성을 입증하는 문서에 연동된 단계적 가격 책정이 단기적인 완화책으로 대두되고 있습니다.
부문별 분석
분자진단은 2025년 호흡기질환 검사 시장 매출의 48.82%를 차지했으며, 이는 자동화 PCR 및 등온 플랫폼에 대한 수십 년간의 투자가 결실을 맺고 있음을 보여줍니다. 그러나 가장 빠르게 성장하는 분야는 기계식 검사이며, 1차 진료 제공업체가 폐기능 검사를 정기 건강검진에 포함시키고 고용주가 새로운 규정 준수 규칙에 대응함에 따라 연평균 4.06%의 성장률을 보이고 있습니다. 이러한 상승 추세에 따라, 예측 기간 동안 기계식 검사의 호흡기질환 검사 시장 규모는 누적 5억 6,000만 달러 증가할 것으로 전망됩니다. 블루투스 지원 통합형 폐기능 측정기와 AI 코칭을 결합한 솔루션을 활용하는 공급업체는 판매 대수와 SaaS 이익률 양면에서 경쟁사를 앞설 것으로 예측됩니다.
표적화된 환급 정책이 이러한 전환을 뒷받침하고 있습니다. COPD 선별 검사에 대한 USPSTF의 B등급 권고에 따라, 보험사는 환자의 본인 부담금 없이 폐기능 검사 비용을 부담해야 할 의무가 있습니다. 이와 동시에, 저가의 병원체 특이적 PCR 검사가 광범위한 증후군별 패널 검사 시장을 잠식하고 있어, 분자진단 분야의 평균 판매 가격은 매년 약 4%에서 6%씩 하락하고 있습니다. 영상 검사는 AI를 통한 분류가 이루어지는 CT 워크플로우의 혜택을 지속적으로 누리고 있으며, 지역 의료 센터를 폐암 검진 프로그램에 참여시키고 하류 생검 의뢰를 확대하고 있지만, 호흡기질환 검사 시장의 절대적인 성장 속도 면에서는 기계식 검사법에 뒤처지고 있습니다.
지역별 분석
북미는 2025년에 전 세계 매출의 43.08%를 차지했습니다. 이는 높은 보험 가입률, 관대한 메디케어 코딩, 그리고 2년 동안 7개의 호흡기 플랫폼에 ‘획기적인 의료기기(Breakthrough Device)’ 지정을 부여한 FDA의 미처리 건 집중 처리에 힘입은 결과입니다. 보상액 삭감이 분자진단의 이익률을 억제하고 있는 반면, 시장 출시 속도가 빠르다는 장점 덕분에 혁신 파이프라인은 활기를 띠고 있습니다. 병원에서는 응급실의 트리아지 스테이션에 신속 PCR 분석기 도입이 확대되면서 항생제 과다 사용을 줄이는 동시에 증후군별 검사 카트리지에 대한 수요를 촉진하고 있습니다.
유럽은 성숙해 가고 있지만 혁신에 우호적인 호흡기질환 검사 시장 점유율을 차지하고 있으며, IVDR(체외진단용 의료기기 규정) 준수에 따른 혼란을 극복하고 제품 폭을 회복하고 있습니다. 독일과 영국의 폐암 선별 검사 시범 사업은 2028년까지 전국 규모의 프로그램으로 확대될 예정이며, CT 검사 및 바이오마커 검사에 대한 안정적인 수요가 예상됩니다. 한편, 각국의 의료보험사는 하이플렉스 PCR 검사에 검사 건수 상한을 부과하고 있으며, 이에 따라 검사 기관들은 임상적 유용성을 극대화하는 알고리즘 주도형 검사 활용으로 전환하고 있습니다.
아시아태평양은 7.27%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있으며, 2030년까지 절대액 기준으로 유럽을 추월할 전망입니다. 인도의 ‘아유슈만 바라트’ 제도에서는 결핵 분자진단 검사 및 폐 기능 검사 비용이 환급 대상이 되어, 3급 도시에서도 진단 서비스를 이용할 수 있게 되었습니다. 중국의 국가의료보장국은 2025년에 증후군 패널 검사의 지급 비율을 15% 인상하고, 성립 병원의 예산을 확대했습니다. 이와 병행하여 대기 오염 대책의 의무화로 인해 만성폐쇄성폐질환(COPD) 선별 검사 건수가 증가했으며, 호흡기질환 검사 시장에서 기계적 검사의 비중이 확대되고 있습니다.
중동 및 아프리카 및 남미는 여전히 규모는 작지만 큰 기회를 내포하고 있습니다. 걸프협력회의(GCC) 회원국들은 시설 내에 분자 검사실을 갖춘 주요 3차 의료 기관에 자금을 지원하고 있는 반면, 브라질의 민간 보험 시장은 신속 항원 검사 키트를 갖춘 소매 클리닉의 확장을 뒷받침하고 있습니다. 두 지역 모두 검사 키트의 대부분을 수입에 의존하고 있기 때문에 지역별 조립 거점을 설립하는 세계 OEM 제조업체에게는 규모의 경제를 기대할 수 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the respiratory disease testing market size is projected to expand from USD 6.04 billion in 2025 and USD 6.24 billion in 2026 to USD 7.48 billion by 2031, registering a CAGR of 3.69% between 2026 to 2031.
This report is Segmented by Test Type (Imaging Tests, Molecular Diagnostic Tests, Mechanical Tests, Blood-Gas & Electrolyte Tests), Disease (Asthma & COPD, Tuberculosis, Lung Cancer, and More), End User (Hospitals & Clinics, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). Market Forecasts are Provided in Terms of Value (USD).
Global Respiratory Disease Testing Market Trends and Insights
Air-Quality Regulation-Fuelled Demand Surge
Strengthening particulate-matter limits across China and India requires mandatory spirometry for industrial workers, driving bulk purchases of portable devices and associated disposables. Enterprises are choosing bundled contracts that include hardware, calibration services, and cloud dashboards, enabling vendors to lock in recurring revenue. Real-time AI coaching embedded in modern spirometers reduces dependence on scarce technicians and extends screening into tier-2 cities. This expansion is widening the footprint of the respiratory disease testing market among employer health programs. Device makers that localize manufacturing close to Asian hubs are capturing cost advantages and faster regulatory clearance.
Post-COVID Era Stockpiling of Multiplex Respiratory Panels
Hospital preparedness grants in the United States and bulk buys in Europe lifted molecular-panel shipments by nearly one-fifth during 2024 to early 2025. By mid-2025, consumption normalized to roughly two-thirds of installed capacity, triggering an abrupt drawdown of surplus inventory. Laboratories are now pivoting toward modular syndromic panels that combine respiratory, gastrointestinal, and central nervous system targets to retain capital utilization. The swing exposed supply-chain fragilities and prompted reagent makers to roll out auto-refill programs matched to real-time analyzer telemetry, a service model that is becoming table stakes in the respiratory disease testing market.
Reimbursement Headwinds for Advanced Molecular Panels
CMS lowered the 2025 national limitation amount for CPT 87631 respiratory panels by 12%, and private payers layered on prior-authorization hurdles, curbing uptake outside inpatient walls. Laboratories are downgrading to 3-to-5-target assays that fit tighter cost ceilings, eroding absolute revenue per sample. The margin squeeze is widening the gap between large hospital networks, which dilute overhead across higher volumes, and stand-alone clinics, which cannot amortize instrument investments as quickly. Tiered pricing tied to medical-necessity documentation is emerging as a short-term mitigation lever.
Other drivers and restraints analyzed in the detailed report include:
- Hospital Decanting to Home/POC Settings
- AI-Assisted Image & Spirometry Analytics Adoption
- Shortage of Trained Pulmonary-Lab Personnel
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Molecular diagnostics accounted for 48.82% of 2025 respiratory disease testing market revenue, underscoring decades of investment in automated PCR and isothermal platforms. Yet, mechanical tests are the fastest-growing slice, climbing 4.06% annually as primary-care providers bundle spirometry with routine checkups and employers meet new compliance rules. This upswing pushes the mechanical slice's respiratory disease testing market size toward an incremental USD 0.56 billion over the forecast horizon. Vendors capitalizing on integrated Bluetooth spirometers coupled with AI coaching stand to outpace peers on both unit volumes and SaaS margins.
Targeted reimbursement policies bolster the shift. A Grade B USPSTF endorsement for COPD screening mandates insurer coverage of spirometry without patient cost-sharing. In parallel, lower-priced pathogen-specific PCR assays are cannibalizing broad syndromic panels, compressing molecular average selling prices by roughly 4% to 6% each year. Imaging tests continue to benefit from AI-triaged CT workflows, drawing community centers into lung-cancer screening programs and expanding downstream biopsy referrals, but they trail mechanical modalities in absolute growth velocity within the respiratory disease testing market.
Complete Report Scope:
- By Test Type
- Imaging Tests
- Molecular Diagnostic Tests
- Mechanical Tests (PFT/Spirometry)
- Blood-Gas & Electrolyte Tests
- By Disease
- Asthma & COPD
- Tuberculosis
- Lung Cancer
- Influenza & RSV
- Other Respiratory Infections
- By End User
- Hospitals & Clinics
- Diagnostic Laboratories
- Home Care Settings
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 43.08% of global revenue in 2025, underpinned by high insurance penetration, generous Medicare coding, and an FDA backlog-clearing spree that granted Breakthrough Device status to seven respiratory platforms over two years. While reimbursement reductions temper molecular margins, speed-to-market advantages keep innovation pipelines vibrant. Hospitals increasingly deploy rapid PCR analyzers at emergency-department triage stations, cutting antibiotic overuse and reinforcing demand for syndromic cartridges.
Europe contributes a mature yet innovation-friendly share of the respiratory disease testing market, navigating IVDR compliance turbulence to restore product breadth. Lung-cancer screening pilots in Germany and the United Kingdom are scaling to nationwide programs by 2028, promising steady CT and biomarker volumes. Conversely, national health payors enforce volume caps on high-plex PCR, driving labs toward algorithm-driven test utilization that maximizes clinical utility.
Asia-Pacific posts the quickest 7.27% CAGR, set to overtake Europe on absolute dollars by 2030. India's Ayushman Bharat scheme now reimburses molecular TB testing and spirometry, bringing diagnostics to tier-3 towns. China's National Healthcare Security Administration boosted syndromic-panel payment rates by 15% in 2025, unlocking provincial hospital budgets. Parallel air-pollution mandates increase COPD screening volumes, swelling the mechanical-test subset of the respiratory disease testing market.
Middle East & Africa and South America remain smaller but opportunity-rich. Gulf Cooperation Council members are funding flagship tertiary hospitals with on-site molecular labs, while Brazil's private insurer market fuels retail-clinic expansion stocked with rapid antigen tests. Both regions import the bulk of their kits, presenting scale economies for global OEMs that establish regional assembly nodes.
- Abbott Laboratories
- Beckton Dickinson
- bioMerieux
- Danaher
- Dragerwerk
- Roche
- GE HealthCare Technologies Inc.
- Hill-Rom (Baxter International)
- Hologic
- MGC Diagnostics
- NDD Medical Technologies
- PerkinElmer
- Koninklijke Philips
- QIAGEN
- Quidel-Ortho Corporation
- Resmed
- Seegene
- Siemens Healthineers
- Thermo Fisher Scientific
- Vitalograph Ltd.
- Vyaire Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Air-Quality Regulation-Fuelled Demand Surge
- 4.2.2 Post-COVID Era Stockpiling of Multiplex Respiratory Panels
- 4.2.3 Hospital Decanting to Home/POC Settings
- 4.2.4 AI-Assisted Image & Spirometry Analytics Adoption
- 4.2.5 Digital-Diagnostic Data Mandates
- 4.2.6 Climate-Linked Pathogen Seasonality Shifts
- 4.3 Market Restraints
- 4.3.1 Reimbursement Headwinds for Advanced Molecular Panels
- 4.3.2 Shortage of Trained Pulmonary-Lab Personnel
- 4.3.3 Consumable-Grade Polysilicone Supply Bottlenecks
- 4.3.4 Antigen-Test Sensitivity Scrutiny by Regulators
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Test Type
- 5.1.1 Imaging Tests
- 5.1.2 Molecular Diagnostic Tests
- 5.1.3 Mechanical Tests (PFT/Spirometry)
- 5.1.4 Blood-Gas & Electrolyte Tests
- 5.2 By Disease
- 5.2.1 Asthma & COPD
- 5.2.2 Tuberculosis
- 5.2.3 Lung Cancer
- 5.2.4 Influenza & RSV
- 5.2.5 Other Respiratory Infections
- 5.3 By End User
- 5.3.1 Hospitals & Clinics
- 5.3.2 Diagnostic Laboratories
- 5.3.3 Home Care Settings
- 5.3.4 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Becton Dickinson & Company
- 6.3.3 bioMerieux SA
- 6.3.4 Danaher Corporation (Cepheid)
- 6.3.5 Dragerwerk AG & Co. KGaA
- 6.3.6 F. Hoffmann-La Roche AG
- 6.3.7 GE HealthCare Technologies Inc.
- 6.3.8 Hill-Rom (Baxter International)
- 6.3.9 Hologic Inc.
- 6.3.10 MGC Diagnostics Corporation
- 6.3.11 NDD Medical Technologies
- 6.3.12 PerkinElmer Inc.
- 6.3.13 Philips Healthcare
- 6.3.14 Qiagen N.V.
- 6.3.15 Quidel-Ortho Corporation
- 6.3.16 ResMed Inc.
- 6.3.17 Seegene Inc.
- 6.3.18 Siemens Healthineers AG
- 6.3.19 Thermo Fisher Scientific Inc.
- 6.3.20 Vitalograph Ltd.
- 6.3.21 Vyaire Medical Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment