|
시장보고서
상품코드
2124410
미국의 스마트 TV 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)US Smart TV - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
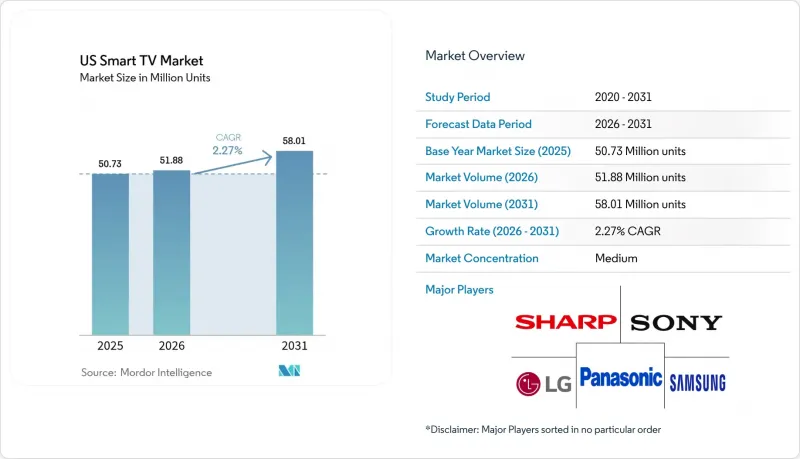
에 의하면, 미국 스마트 TV 시장 규모는 2025년에 5,073만 대라고 평가되어 2026년 5,188만 대로부터 2031년까지 5,801만 대에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 2.27%를 나타낼 전망입니다.
본 보고서는 화면 크기별(45인치 이하, 45-54인치, 55-64인치, 65-74인치, 75인치 이상), 해상도 유형별(HDTV, 풀HD, 4K UHD, 8K UHD),패널 기술별(LCD/LED, QLED, OLED, Mini-LED), 가격대별(500달러 미만, 500-999달러, 기타), 운영체제별(Roku OS, Google/Android TV, 기타), 지역별로 분류되어 있습니다. 시장 전망은 출하 대수(대) 기준으로 제시되어 있습니다.
미국 스마트 TV 시장 동향 및 인사이트
4K/8K로의 급속한 업그레이드 사이클
4K UHD는 이미 출하 대수의 절반 이상을 차지하고 있지만, 각 제조업체는 8K 대응 프로세서와 첨단 백라이트 기술을 주류로 자리 잡게 함으로써 기술 주기를 단축하고 있습니다. 2025년에 공개된 삼성의 RGB 미니 LED 프로토타입은 LCD와 동등한 비용을 유지하면서도 OLED 수준의 명암비를 실현할 것으로 기대됩니다. LG의 4층 스택형 OLED 아키텍처는 피크 밝기를 40% 향상시켜, 과거 프리미엄 모델의 보급을 늦추었던 HDR의 한계를 해소하고 있습니다. 이러한 비약적인 진화가 맞물려, 특히 스트리밍 서비스와 차세대 게임기를 통해 8K 네이티브 컨텐츠가 점차 제공됨에 따라 기존 소유자들의 조기 교체를 촉진하고 있습니다.
내장 스트리밍 기능과 앱 생태계
스마트 TV의 운영 체제는 현재 외장 스틱과 동등한 기능을 재현하고 있으며, 스토어 프론트, 결제, 타겟팅 광고를 TV 브랜드 아래로 통합하고 있습니다. Roku OS는 여전히 가장 큰 점유율을 차지하고 있지만, 검색 개인화가 시청 시간을 끌어올리는 가운데 Google TV가 가장 빠르게 점유율을 확대되고 있습니다. LG의 보고서에 따르면, 자사의 webOS 광고 기술을 통한 수익은 2024년에 1조 원을 넘어설 것으로 예상되며, 이는 플랫폼 경제가 하드웨어 이익률의 감소를 점점 더 상쇄하고 있음을 보여줍니다.
스마트폰·태블릿 시청으로 인한 캐니발리제이션
모바일 기기의 화면이 낮 시간대의 여가 시간을 점점 더 차지하게 되면서, 기존에는 대형 화면으로의 기기 교체를 정당화하던 ‘가족과 함께하는 시청’ 기회가 제한되고 있습니다. 연방거래위원회(FTC)의 2024년 조사에 따르면, 스트리밍 플랫폼이 모바일 기기용으로 UI 디자인을 과도하게 최적화하고 있어, 이것이 단독 이용 습관을 강화하고 있다는 사실이 부각되고 있습니다. 그러나 게임이나 고품질 영화 컨텐츠는 여전히 TV의 강점이며, 이러한 ‘캐니발리제이션 효과’를 완화하고 있습니다.
부문 분석
2025년, 55-64인치 대는 출하 점유율 34.02%로 1위를 유지하며, 주류 ‘스위트 스팟’으로서의 역할을 입증했습니다. 그러나 75인치 이상 부문은 연평균 성장률(CAGR) 2.69%로 가장 빠르게 성장할 전망이며, 미국 스마트 TV 시장 전체의 성장률을 상회할 것으로 보입니다. 얼리 어답터들은 몰입감 넘치는 게임 경험과 극장급 스트리밍을 이유로, 현재 프로모션 가격으로 2,000달러 미만에 구입할 수 있는 패널을 선택하고 있습니다. 삼성은 마이크로 LED 공급망과 적극적인 판로 홍보를 활용하여 초대형 시장 점유율의 약 3분의 1을 차지하고 있습니다. 엔트리급 45인치 미만 모델은 개인 시청용 저가형 태블릿과 베젤을 최소화하여 좁은 아파트에도 설치하기 쉬워진 중형 TV에 밀려 계속해서 점유율이 하락하고 있습니다.
설치 업체에 따르면, 무선 브레이크아웃 박스 덕분에 설치 시간이 40% 가까이 단축되어 기존 주택에서 75인치 화면의 벽걸이 설치가 빠르게 확산되고 있습니다. ENERGY STAR 데이터에 따르면, 1제곱인치당 전력 소비량은 패널 면적 증가 속도를 앞지르는 속도로 감소하고 있어, 에너지 절약에 민감한 구매자들의 전기 요금에 대한 우려를 완화시키고 있습니다. 이러한 동향을 종합해 볼 때, 대형 디스플레이는 앞으로도 미국 스마트 TV 시장의 주요 성장 동력으로 남아 있을 것으로 보입니다.
4K UHD는 2025년에 출하 점유율 54.02%에 달하며, 이미 필수 조건이 되었습니다. 아직 발전 단계에 있는 8K 부문은 소스 컨텐츠 부족을 보완해 주는 AI 업스케일링 엔진의 도움으로 연평균 성장률(CAGR) 3.17%를 나타낼 것으로 예측됩니다. 마이크로소프트의 ‘Xbox Series X’와 소니의 ‘PlayStation 5 Pro’는 모두 2025년 펌웨어 업데이트를 통해 8K 출력을 지원할 예정이며, 스트리밍 제공업체들도 제한된 시장에서 8K VOD 시범 운영을 시작하고 있습니다. 업셀 전략의 일환으로, 8K 패널과 단기 할부 계획을 결합함으로써 고가로 인한 구매 망설임을 완화하고, 얼리 어답터들이 3-4년마다 기기를 교체하도록 유도하고 있습니다. Full HD모델은 현재 주로 숙박 시설이나 가격을 최우선으로 하는 소매점의 주력 상품으로만 남아 있습니다.
OLED 제조업체들은 밝기 향상으로 인해 고품질 4K HDR에 비해 8K의 지각적 우위가 약해지고 있다고 주장하지만, 조사 데이터에 따르면 초기 게이머들은 벤치마크 결과를 자랑할 수 있다는 이유로 8K TV를 불균형적으로 많이 선택하고 있는 것으로 나타났습니다. 압축 코덱이 성숙해짐에 따라 8K 스트리밍의 대역폭 오버헤드는 감소할 것이며, 대규모 배포에 있어 마지막 기술적 장벽 중 하나가 제거될 것입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the US smart TV market size was valued at 50.73 million units in 2025 and estimated to grow from 51.88 million units in 2026 to reach 58.01 million units by 2031, at a CAGR of 2.27% during the forecast period (2026-2031).
This report is Segmented by Screen Size (Up To 45", 45-54", 55-64", 65-74", 75" & Above), Resolution Type (HDTV, Full HD, 4K UHD, 8K UHD), Panel Technology (LCD/LED, QLED, OLED, Mini-LED), Price Band (less Than USD 500, USD 500-999, and More), Operating System (Roku OS, Google/Android TV, and More), and Geography. The Market Forecasts are Provided in Terms of Volume (Units).
US Smart TV Market Trends and Insights
Rapid 4K/8K upgrade cycle
4K UHD already dominates more than half of shipments, yet manufacturers are shortening the technology cycle by mainstreaming 8K-ready processors and advanced backlighting. Samsung's RGB mini-LED prototypes shown in 2025 promise OLED-level contrast while holding LCD cost parity. LG's four-stack OLED architecture lifts peak brightness by 40%, solving HDR limitations that once slowed premium adoption. These step-changes jointly nudge existing owners toward earlier replacement, especially as streaming and next-gen consoles gradually expose 8K native content.
Built-in streaming and app ecosystems
Smart-TV operating systems now replicate the functionality of external sticks, bringing storefronts, payments, and targeted ads under the television brand. Roku OS still accounts for the largest footprint, but Google TV is the fastest riser as search personalization drives watch-time. LG reports that its webOS ad-tech revenue surpassed KRW 1 trillion in 2024, proof that platform economics increasingly offset hardware margin compression.
Smartphone/tablet viewing cannibalization
Mobile screens increasingly capture daytime entertainment minutes, limiting shared viewing occasions that traditionally justified large-screen upgrades. The Federal Trade Commission's 2024 study highlights how streaming platforms over-index their UI design for handheld devices, reinforcing single-user consumption habits. Yet gaming and premium cinematic content remain television strongholds, tempering the cannibalization effect.
Other drivers and restraints analyzed in the detailed report include:
- Surge in larger-than-65" purchases
- CTV advertising revenue sharing creates new business models
- Price compression from low-cost Chinese brands
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The 55-64 inch band retained a leading 34.02% shipment share in 2025, confirming its role as the mainstream sweet spot. However, the 75-inch-plus segment is set to grow fastest at 2.69% CAGR, outpacing overall US Smart TV market growth. Early adopters cite immersive gaming and theater-grade streaming as justification for purchasing panels that now cost under USD 2,000 at promotion. Samsung commands roughly one-third of ultra-large formats by leveraging its micro-LED supply chain and aggressive channel promotions. Entry-level sub-45-inch models continue sliding, squeezed by cheap tablets for personal viewing and by mid-sized sets that increasingly fit smaller apartments thanks to bezel minimization.
Installers report that wireless breakout boxes reduce setup time by almost 40%, accelerating acceptance of wall-mounted 75-inch screens in existing homes. ENERGY STAR data suggest power consumption per square inch is falling faster than panel area is rising, muting electricity-cost objections among energy-conscious buyers. Collectively, these trends mean that large-format displays will remain the headline growth driver inside the US Smart TV market.
4K UHD reached 54.02% shipment share in 2025, having already become table stakes. The nascent 8K segment is projected to post a 3.17% CAGR, aided by AI-upscaling engines that mask source-content scarcity. Microsoft's Xbox Series X and Sony's PlayStation 5 Pro both enabled 8K output in 2025 firmware updates, and streaming providers have begun test runs of 8K VOD in limited markets. Upsell tactics pair 8K panels with shorter finance plans to offset sticker shock, ensuring early adopters rotate into the pool every 3-4 years. Full-HD models now survive mainly in hospitality and price-first retail doorbusters.
OLED providers argue that brightness gains close the perceived advantage of 8K over high-quality 4K HDR, but survey data show that early gamers disproportionately choose 8K sets for their benchmarking bragging rights. As compression codecs mature, bandwidth overhead for 8K streams will fall, removing one of the last technical hurdles to mass deployment.
Complete Report Scope:
- By Screen Size
- Up to 45"
- 45-54"
- 55-64"
- 65-74"
- 75" and Above
- By Resolution Type
- HDTV
- Full HD
- 4K UHD
- 8K UHD
- By Panel Technology
- LCD/LED
- QLED
- OLED
- Mini-LED
- By Price Band
- less than USD 500
- USD 500-999
- USD 1,000-1,999
- More than USD 2,000
- By Operating System
- Roku OS
- Google/Android TV
- Tizen OS
- webOS
- Fire TV OS
- VIDAA U
List of Companies Covered in this Report:
- Samsung Electronics Co., Ltd.
- LG Electronics Inc.
- Sony Group Corporation
- TCL Electronics Holdings Ltd.
- VIZIO Holding Corp.
- Hisense Group Co., Ltd.
- Panasonic Holdings Corporation
- Sharp Corporation
- Koninklijke Philips N.V.
- Skyworth Group Ltd.
- Xiaomi Corp.
- Amazon.com Inc. (Fire TV Devices)
- Apple Inc. (Apple TV & tvOS Integrations)
- Haier Smart Home Co., Ltd.
- Funai Electric Co., Ltd. (Magnavox/Sanyo)
- Westinghouse Electric Corp.
- Sceptre Inc.
- Insignia Systems Inc. (Insignia TV)
- JVC Kenwood Corp.
- Pioneer Corp.
- Seiki Digital Inc.
- Element Electronics LLC
- Hitachi Ltd.
- LeEco (LeTV)
- Metz Consumer Electronics GmbH
- B&O A/S (Bang & Olufsen)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid 4K/8K upgrade cycle
- 4.2.2 Built-in streaming and app ecosystems
- 4.2.3 Surge in larger-than-65" purchases
- 4.2.4 CTV advertising-revenue sharing with OEMs
- 4.2.5 Gaming-optimized TV features (VRR, cloud gaming hubs)
- 4.2.6 Energy-efficiency tax incentives for "ENERGY STAR 9.0" sets
- 4.3 Market Restraints
- 4.3.1 Smartphone/tablet viewing cannibalization
- 4.3.2 Price compression from low-cost Chinese brands
- 4.3.3 OS-level data-privacy pushback curbing telemetry value
- 4.3.4 Supply-chain volatility in mini-LED backlights
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Industry Value-Chain Mapping
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Screen Size
- 5.1.1 Up to 45"
- 5.1.2 45-54"
- 5.1.3 55-64"
- 5.1.4 65-74"
- 5.1.5 75" and Above
- 5.2 By Resolution Type
- 5.2.1 HDTV
- 5.2.2 Full HD
- 5.2.3 4K UHD
- 5.2.4 8K UHD
- 5.3 By Panel Technology
- 5.3.1 LCD/LED
- 5.3.2 QLED
- 5.3.3 OLED
- 5.3.4 Mini-LED
- 5.4 By Price Band
- 5.4.1 less than USD 500
- 5.4.2 USD 500-999
- 5.4.3 USD 1,000-1,999
- 5.4.4 More than USD 2,000
- 5.5 By Operating System
- 5.5.1 Roku OS
- 5.5.2 Google/Android TV
- 5.5.3 Tizen OS
- 5.5.4 webOS
- 5.5.5 Fire TV OS
- 5.5.6 VIDAA U
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Vendor Market Ranking Analysis
- 6.5 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.5.1 Samsung Electronics Co., Ltd.
- 6.5.2 LG Electronics Inc.
- 6.5.3 Sony Group Corporation
- 6.5.4 TCL Electronics Holdings Ltd.
- 6.5.5 VIZIO Holding Corp.
- 6.5.6 Hisense Group Co., Ltd.
- 6.5.7 Panasonic Holdings Corporation
- 6.5.8 Sharp Corporation
- 6.5.9 Koninklijke Philips N.V.
- 6.5.10 Skyworth Group Ltd.
- 6.5.11 Xiaomi Corp.
- 6.5.12 Amazon.com Inc. (Fire TV Devices)
- 6.5.13 Apple Inc. (Apple TV & tvOS Integrations)
- 6.5.14 Haier Smart Home Co., Ltd.
- 6.5.15 Funai Electric Co., Ltd. (Magnavox/Sanyo)
- 6.5.16 Westinghouse Electric Corp.
- 6.5.17 Sceptre Inc.
- 6.5.18 Insignia Systems Inc. (Insignia TV)
- 6.5.19 JVC Kenwood Corp.
- 6.5.20 Pioneer Corp.
- 6.5.21 Seiki Digital Inc.
- 6.5.22 Element Electronics LLC
- 6.5.23 Hitachi Ltd.
- 6.5.24 LeEco (LeTV)
- 6.5.25 Metz Consumer Electronics GmbH
- 6.5.26 B&O A/S (Bang & Olufsen)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment