

|
시장보고서
상품코드
2124457
NATO의 탄약 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)NATO Ammunition - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 탄약 시장 규모는 2025년 87억 달러로 평가되었습니다. 2026년에는 90억 6,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 4.4%로 성장을 지속하여, 2031년에는 112억 3,000만 달러에 이를 것으로 예측됩니다.
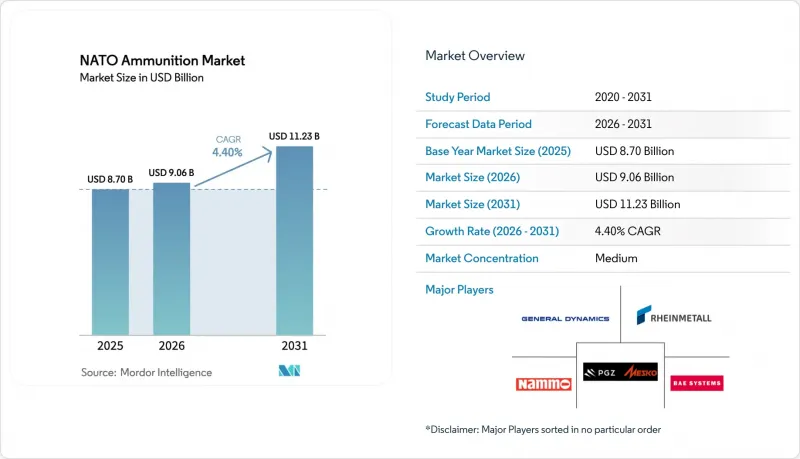
본 보고서는 구경(소구경, 중구경, 대구경, 기타), 제품(탄환·카트리지, 포탄·박격포탄, 항공폭탄·수류탄),유도 방식(유도식·비유도식), 최종 사용자(군, 법 집행 기관, 기타), 플랫폼(육상, 해상, 항공), 지역(미국, 캐나다, 영국, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
NATO의 탄약 시장 동향 및 인사이트
NATO의 국방비 지출 강화 노력
회원국의 국방 예산은 냉전 종식 이후 가장 빠른 속도로 증가하고 있습니다. 2024년에는 32개 동맹국 중 23개국이 GDP의 2%라는 국방비 기준을 달성했습니다. 이는 10년 전에는 불과 6개국에 불과했던 것과 비교해 상당한 증가세를 보인 것입니다. 2024년 유럽의 국방 지출은 18% 증가했으며, 추가 자금의 상당 부분이 포병용, 소형 무기용, 방공용 탄약에 할당되었습니다. 2035년까지 GDP의 5%를 목표로 할 가능성에 대한 논의가 진전된다면, 연간 추가로 1,000억 유로(1,172억 2,000만 달러)의 자금이 확보될 가능성이 있으며, 그중 15-20%가 탄약 조달에 배정될 전망입니다. 폴란드의 국방비가 GDP의 4.7%를 차지하고 있다는 사실은 이러한 추세를 여실히 보여주고 있으며, 폴란드는 155mm 및 소구경 탄약 생산에 막대한 투자를 하고 있습니다. 한편, 남부 회원국들은 여전히 해군 관련 우선 과제에 주력하고 있어, NATO의 탄약 생산 계획을 수립할 때 공급업체들은 이러한 지역 간 수요 격차를 해소해야 합니다.
우크라이나 분쟁 이후 비축량 보충
키예프에 대한 지원으로 인해 동맹의 비축량은 대폭 감소하여 계획 수준에 미치지 못하고 있습니다. 2024년 중반까지 미국은 200만 발 이상의 155mm 포탄을 수송했기 때문에 2024년 말까지 월 10만 발의 포탄을 생산하는 긴급 증산 계획이 수립되었습니다. 독일의 비축량은 3만 발 미만으로 떨어졌기 때문에 라인메탈사와 22만 발의 포탄을 조달하는 85억 유로(99억 6,000만 달러) 규모의 계약이 체결되었으며, 2026년부터는 연간 70만 발의 기준치가 설정되었습니다. 동맹국들은 ‘저스트-인-타임(JIT)’ 재고 모델에서 벗어나 90-180일 분량의 비축량을 유지하는 방향으로 전환하고 있으며, 이러한 움직임으로 인해 2027년까지 기준선 수요가 약 40% 증가할 것으로 예측됩니다. 이러한 비축량 보충 노력은 첨단 기술 도입을 가속화하고 있습니다. 각국 정부는 기존 탄약에 비해 비용이 20-30% 더 비싸음에도 불구하고, 비감응탄이나 프로그래밍 가능한 탄약을 통한 비축 보충을 우선시하고 있기 때문입니다.
발화약·화약·기폭제의 원료 부족
니트로셀룰로오스와 안티모니의 세계적 공급은 여전히 저조한 상태입니다. 안티모니 수출의 70%를 중국이 차지하고 있으며, 정기적인 수출 규제로 인해 2022년 이후 프라이머 가격은 40-60% 상승했습니다. 서유럽에서는 추진제 분말을 생산하는 공장이 제한적이며, 새로운 생산 능력을 확보하려면 환경 허가 취득에 3-5년이 소요됩니다. 제너럴 다이내믹스(General Dynamics)는 2024년 추진제 생산 확대에 5,000만 달러를 배정했으나, 완전한 가동 능력에 도달하는 것은 2027년 이후가 될 것으로 전망됩니다. 각 생산 업체들은 소형 무기용 훈련탄보다 155mm 포탄 생산을 우선시하고 있으며, 이로 인해 단기적으로는 NATO의 탄약 시장공급 부족이 초래되고 있습니다.
부문별 분석
155mm 포탄에 의한 화력 지원이 전술적 중요성을 다시금 높이고 있는 만큼, 대구경 탄약은 2031년까지 연평균 성장률(CAGR) 6.10%로 성장하여 다른 구경 범주의 성장률을 상회할 것으로 예측됩니다. 나토(NATO)의 대구경 탄약 시장은 미 육군이월10만 발의 생산을 유지할 계획이라는 점에 힘입어 지지를 받고 있으며, 이는 과거 최고치를 크게 상회하는 수준입니다. 소구경 탄약은 2025년에 44.87%의 시장 점유율을 유지했지만, 무연 탄약으로의 의무적인 전환으로 인해 이익률 압박에 직면해 있습니다.
단가 차이는 예산 배분의 우선순위에 영향을 미칩니다. 일반 탄환의 단가는 1.50달러 미만인 반면, 155mm 고폭탄은 3,000-8,000달러, 엑스칼리버 정밀유도탄은 6만 8,000달러를 초과합니다. 이러한 비용에도 불구하고, 40km 사거리에서 대구경 포탄의 살상력은 치열한 전투가 벌어지는 기동 경로에서 여전히 매우 중요합니다. 중구경 포탄의 성장은 고르지 않으며, 푸마(Puma) IFV나 브래들리 A4의 포 성능 향상과 같은 차량 업그레이드 주기에 의해 주도되고 있습니다.
포탄 및 박격포탄은 독일, 미국, 폴란드로부터의 최소 생산량을 보장하는 다년 계약에 힘입어 2026년부터 2031년까지 연평균 성장률(CAGR) 5.90%를 나타낼 것으로 예측됩니다. 총탄 및 카트리지는 여전히 최대 처리량을 차지하고 있으며, 2025년 매출의 45.93%를 차지했습니다. 그러나 환경 규제 대응 비용 및 잉여 재고 매각으로 인해 수요 동향은 둔화되는 추세입니다.
공급망 구조에는 큰 차이가 있습니다. 소구경 탄약은 레이크시티와 같은 수직 통합형 시설에서 생산되는 반면, 포탄의 탄피, 화약, 기폭 장치는 병목 현상이 발생하기 쉬운 3단계 구조의 네트워크에 의존하고 있습니다. 2024년에 9억 6,100만 달러 규모로 체결된 미국 155mm 포탄의 무기한 납품 계약은 위험 분산의 좋은 사례이며, 이를 통해 육군은 재협상 없이 생산량을 조정할 수 있게 되었습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 주요 요약
제3장 주요 업계 동향
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the NATO ammunition market size is expected to grow from USD 8.7 billion in 2025 to USD 9.06 billion in 2026 and is forecasted to reach USD 11.23 billion by 2031 at a 4.4% CAGR over 2026-2031.
This report is Segmented by Caliber (Small, Medium, Large, and Others), Product (Bullets and Cartridges, Artillery Shells and Mortars, and Aerial Bombs and Grenades), Guidance (Guided and Unguided), End-User (Military, Law-Enforcement, and More), Platform (Land, Naval, and Airborne), and Geography (United States, Canada, United Kingdom, and More). The Market Forecasts are Provided in Terms of Value (USD).
NATO Ammunition Market Trends and Insights
Heightened NATO Defense-Spending Commitments
Member-state budgets are increasing at the fastest rate since the end of the Cold War. In 2024, twenty-three out of thirty-two allies met the 2% of GDP defense spending benchmark, a significant rise from just six a decade earlier. European defense expenditures grew by 18% in 2024, with artillery, small arms, and air-defense munitions receiving a substantial share of the additional funds. Discussions around a potential 5% GDP target by 2035 could unlock a further EUR 100 billion (USD 117.22 billion) annually, with 15-20% of this likely allocated to ammunition procurement. Poland's 4.7% of GDP defense spending highlights this trend, with significant investments in 155 mm and small-caliber ammunition production. Meanwhile, southern-flank members remain focused on naval priorities, creating regional demand disparities that suppliers must address when planning NATO ammunition production runs.
Inventory Replenishment After Ukraine Conflict
Transfers to Kyiv have significantly depleted alliance stockpiles, falling below planned levels. By mid-2024, the US had shipped over 2 million 155 mm rounds, prompting a surge plan to produce 100,000 shells per month by the end of 2024. Germany's stockpile dropped below 30,000 rounds, leading to an EUR 8.5 billion (USD 9.96 billion) contract with Rheinmetall for 220,000 shells and a 700,000-round annual baseline starting in 2026. Allies are shifting away from just-in-time inventory models in favor of maintaining 90-180 day reserves, a move expected to increase baseline demand by approximately 40% through 2027. This replenishment effort is accelerating the adoption of advanced technologies, as governments prioritize refilling stockpiles with insensitive or programmable rounds, despite their 20-30% higher costs compared to legacy munitions.
Press-Powder and Primer Feed-Stock Shortages
The global supply of nitrocellulose and antimony remains constrained. China accounts for 70% of antimony exports, and periodic export restrictions have driven primer prices up by 40-60% since 2022. In the West, only a limited number of plants produce propellant powder, and establishing new capacity requires 3-5 years for environmental permitting. General Dynamics allocated USD 50 million in 2024 to expand propellant production, but full operational capacity is not expected until 2027. Producers are prioritizing allocations, focusing on 155 mm shells over small-arms training rounds, which has tightened the NATO ammunition market in the short term.
Other drivers and restraints analyzed in the detailed report include:
- Multiyear Framework Contracts for 155 mm Rounds
- Allied Call-Off Options for Smart Cartridge Fuzes
- Range-Environmental Restrictions on Lead Propellants
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Large-caliber rounds are projected to grow at a 6.10% CAGR through 2031, surpassing growth in other caliber categories as 155 mm fire support regains doctrinal importance. The NATO ammunition market for large-caliber munitions is bolstered by the US Army's plan to sustain production of 100,000 shells per month, significantly exceeding historical peaks. Small-caliber ammunition, while maintaining a 44.87% market share in 2025, faces margin pressures due to mandatory transitions to lead-free cartridges.
Unit cost differences influence budgeting priorities. Conventional ball rounds cost less than USD 1.50, while high-explosive 155 mm shells range from USD 3,000 to USD 8,000, and Excalibur precision-guided variants exceed USD 68,000. Despite these costs, the lethality of large-caliber rounds at a 40 km range remains critical in contested maneuver corridors. Mid-caliber growth is uneven, driven by vehicle upgrade cycles such as the Puma IFV and Bradley A4 cannon enhancements.
Artillery shells and mortars are expected to grow at a 5.90% CAGR from 2026 to 2031, supported by multi-year contracts from Germany, the US, and Poland that secure minimum production volumes. Bullets and cartridges continue to generate the highest throughput, accounting for 45.93% of 2025 revenue. However, environmental compliance costs and surplus stock sell-offs are flattening demand trends.
Supply chain structures vary significantly. Small-caliber ammunition is produced in vertically integrated facilities, such as Lake City, whereas artillery cases, fills, and fuzes rely on a three-tier network that is susceptible to bottlenecks. US 155 mm indefinite-delivery contracts worth USD 961 million in 2024 demonstrate risk pooling, enabling the Army to adjust production without the need for renegotiation.
Complete Report Scope:
- By Caliber
- Small Caliber
- Medium Caliber
- Large Caliber
- Others
- By Product
- Bullets and Cartridges
- Artillery Shells and Mortars
- Aerial Bombs and Grenades
- By Guidance
- Guided
- Unguided
- By End-User
- Military
- Law-Enforcement
- Civil and Sport Shooting
- By Platform
- Land Platform
- Naval Platform
- Airborne Platform
- By Geography
- United States
- Canada
- United Kingdom
- France
- Germany
- Italy
- Poland
- Spain
- Turkey
- Rest of NATO Countries
List of Companies Covered in this Report:
- Rheinmetall AG
- BAE Systems plc
- General Dynamics Corporation
- Nammo AS
- Winchester Ammunition (Olin Corporation)
- CBC Global Ammunition
- MESKO S.A.
- KNDS N.V.
- Northrop Grumman Corporation
- Global Ordnance LLC
- FN HERSTAL
- The Kinetic Group
- Elbit Systems Ltd.
- Saab AB
- Makine ve Kimya Endustrisi A.S.
- Sellier & Bellot a.s. (Colt CZ Group SE)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
- 1.3 Research Methodology
2 EXECUTIVE SUMMARY
3 KEY INDUSTRY TRENDS
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Heightened NATO defense-spending commitments
- 4.2.2 Inventory replenishment after Ukraine conflict
- 4.2.3 Multiyear framework contracts for 155 mm rounds
- 4.2.4 Allied call-off options for smart cartridge fuzes
- 4.2.5 Accelerated NSPA procurement processes
- 4.2.6 Shift toward insensitive-munition fillers
- 4.3 Market Restraints
- 4.3.1 Press-powder and primer feed-stock shortages
- 4.3.2 Ageing case-line tooling at legacy factories
- 4.3.3 Tightened ITAR/export-control bottlenecks
- 4.3.4 Range-environmental restrictions on lead propellants
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Caliber
- 5.1.1 Small Caliber
- 5.1.2 Medium Caliber
- 5.1.3 Large Caliber
- 5.1.4 Others
- 5.2 By Product
- 5.2.1 Bullets and Cartridges
- 5.2.2 Artillery Shells and Mortars
- 5.2.3 Aerial Bombs and Grenades
- 5.3 By Guidance
- 5.3.1 Guided
- 5.3.2 Unguided
- 5.4 By End-User
- 5.4.1 Military
- 5.4.2 Law-Enforcement
- 5.4.3 Civil and Sport Shooting
- 5.5 By Platform
- 5.5.1 Land Platform
- 5.5.2 Naval Platform
- 5.5.3 Airborne Platform
- 5.6 By Geography
- 5.6.1 United States
- 5.6.2 Canada
- 5.6.3 United Kingdom
- 5.6.4 France
- 5.6.5 Germany
- 5.6.6 Italy
- 5.6.7 Poland
- 5.6.8 Spain
- 5.6.9 Turkey
- 5.6.10 Rest of NATO Countries
6 COMPETITIVE LANDSCAPE
- 6.1 Strategic Moves
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Rheinmetall AG
- 6.3.2 BAE Systems plc
- 6.3.3 General Dynamics Corporation
- 6.3.4 Nammo AS
- 6.3.5 Winchester Ammunition (Olin Corporation)
- 6.3.6 CBC Global Ammunition
- 6.3.7 MESKO S.A.
- 6.3.8 KNDS N.V.
- 6.3.9 Northrop Grumman Corporation
- 6.3.10 Global Ordnance LLC
- 6.3.11 FN HERSTAL
- 6.3.12 The Kinetic Group
- 6.3.13 Elbit Systems Ltd.
- 6.3.14 Saab AB
- 6.3.15 Makine ve Kimya Endustrisi A.S.
- 6.3.16 Sellier & Bellot a.s. (Colt CZ Group SE)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 Key Strategic Questions for Satellite CEOs


