|
시장보고서
상품코드
2124526
IT 커넥터 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)IT Connector - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
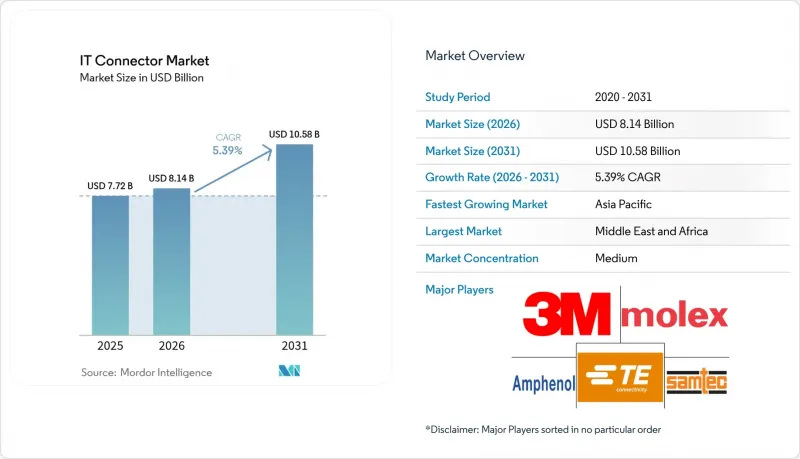
에 의하면, 2026년 IT 커넥터 시장 규모는 81억 4,000만 달러로 추정되고 2025년 77억 2,000만 달러에서 확대해, 2031년에는 105억 8,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 5.39%로 성장할 것으로 전망됩니다.
본 보고서는 커넥터 유형(PCB 커넥터, IDC 커넥터 등), 장착 구성(보드-투-보드 등), 데이터 전송 속도 등급(10 Gbps 이하, 10-25Gbps 등), 최종 사용자 산업(IT 및 통신 등),용도(서버·스토리지 등), 소재(표준형 열가소성 수지, 무할로겐 화합물), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 IT 커넥터 시장 동향 및 인사이트
하이퍼스케일 데이터센터에서의 고속 상호 연결 수요 급증
대역폭을 대량으로 소비하는 AI 클러스터는 레인당 224Gbps를 초과하는 수준으로 전환되고 있으며, 커넥터 설계자들은 좁은 서버 트레이 내에서 삽입 손실과 온도 상승을 줄여야 할 필요가 있습니다. Molex사는 224Gbps PAM4 링크용 광트랜시버의 급속한 보급을 예로 들며, 현재 열 방출이 신호 무결성만큼 중요하다고 지적하고 있습니다. 이러한 노력은 PAM-6/PAM-8 변조 방식의 평가부터 전기 채널을 단축하는 구리선과 광섬유의 코패키징 도입에 이르기까지 다방면에 걸쳐 있습니다. 각 하이퍼스케일러 기업들은 매년 120-130곳의 신규 사이트를 가동할 계획이며, 건설 일정을 6주로 단축하는 동시에 신속하게 키트화 및 조립이 가능한 고밀도 커넥터 시스템을 우선적으로 채택하고 있습니다.
5G/6G 네트워크의 급속한 확산이 RF 커넥터 채택을 촉진
베트남 등 시장에서 진행 중인 2.6GHz 및 3.5GHz 대역 주파수 경매가 미드밴드 매크로셀 및 스몰셀의 확장을 뒷받침하고 있습니다. Massive-MIMO 무선 장비는 4T4R에서 32T32R로 규모가 확대되고 있으며, 이로 인해 광섬유 수를 줄이는 소형 VSFF 인터페이스로의 전환이 촉진되고 있습니다. 각 커넥터 공급업체들은 프론트 홀 셸프 내 포트 밀도를 4배로 높이는 SN급 실적로 이에 대응하고 있는 반면, 캐리어 중립적인 호스트 사업자들은 2028년까지 87억 달러 규모에 달할 것으로 예상되는 분산형 안테나 시스템(DAS)의 구축을 확대되고 있습니다.
구리·희귀금속 가격 변동이 BOM 비용을 상승시켜
구리 및 팔라듐 가격의 급등으로 인해, 파나소닉이 2025년 1월에 발표한 플렉서블 PCB 가격 인상 등 여러 부품 가격 조정 통지가 발령되고 있습니다. 고속 커넥터에는 두꺼운 구리 합금이나 귀금속 도금이 사용되기 때문에 불과 5%의 가격 상승만으로도 매출 총이익률을 압박할 가능성이 있습니다. 각 공급업체는 연간 공급 계약을 체결하고 대체 도금 인증을 추진하는 한편, 삽입·제거 주기를 저해하지 않으면서 질량을 줄일 수 있도록 접점 빔의 재설계에 주력하고 있습니다.
부문별 분석
2025년 IT 커넥터 시장 규모 중 PCB 커넥터는 44.60%를 차지했으며, 이는 마더보드, 스토리지 플레인, 산업용 컨트롤러 등 폭넓은 분야에서 보급되고 있음을 반영합니다. 견고한 핀의 신뢰성, 검증된 결합 사이클, 그리고 광범위한 부품 생태계 덕분에 이 카테고리는 대량 생산 용도에서 확고한 입지를 구축하고 있습니다. 이 부문은 CHIPS 법에 힘입어 PCB 조립의 국내 복귀로 인한 혜택을 여전히 누리고 있으며, 이로 인해 파인 피치 메자닌 포맷에 대한 국내 수요가 증가하고 있습니다.
IO/고속 백플레인 및 플러그인형 커넥터 그룹은 채널당 112 Gbps를 지원할 수 있는 QSFP-DD 800 및 OSFP Xtreme 케이지로의 데이터센터 업그레이드에 힘입어 연평균 성장률(CAGR) 5.55%를 나타낼 것으로 예측됩니다. RF/VSFF 커넥터는 5G 스몰 셀의 고밀도화의 혜택을 받고 있는 반면, 원형 및 직사각형 하우징은 가혹한 환경 하의 산업용 제어에 여전히 필수적입니다. 마이크로 미니어처 제품의 경우, 로봇 수술이나 큐브샛 등 1mm의 공간 절약이 큰 가치를 지닌 이용 사례가 발견되고 있습니다.
보드 대 보드(Board-to-Board) 연결은 2025년에 35.40%의 점유율을 차지하며, 모듈식 하위 어셈블리의 주력 제품으로 자리매김했습니다. 스택형 메자닌 및 카드 에지형은 OEM 업체들이 노트북이나 스위치블레이드 내부의 엄격한 Z축 높이 제한을 충족하는 데 도움이 되고 있습니다. 한편, 와이어-투-보드(WTB) 연결은 전기차(EV) 배터리 팩이나 가전제품에서 유지보수를 간소화하는 하네스가 설계자들에게 선호됨에 따라 연평균 성장률(CAGR) 6.05%로 확대되고 있습니다.
와이어-투-와이어 어셈블리는 기판 공간이 제한된 모터 구동 장치나 HVAC 압축기용으로 계속해서 채택되고 있습니다. 소형화 추세는 현재 모든 실장 방식으로 확산되고 있습니다. 모렉스의 견고한 소형화 시리즈는 IP67 등급의 밀폐성을 유지하면서 실적를 20-55% 줄여, 로봇 공학이나 실외용 통신 장비의 하우징과 같은 요구 사항을 직접 충족하고 있습니다.
지역별 분석
2025년에는 아시아태평양이 시장 매출의 45.50%를 차지하며 시장을 주도했습니다. 이는 중국의 수직 통합형 전자 산업 기반과 인도의 급성장하는 통신 백본이 주도한 결과입니다. 중국 본토의 커넥터 제조업체들은 신뢰성 향상을 목표로 한 각 성의 우대 조치의 혜택을 받고 있으며, 국내 커넥터 부문은 2024년에 전년 대비 126억 위안 증가할 것으로 예측됩니다. 일본과 한국은 첨단 파운드리 라인 내 코패키지드 옵틱스의 조기 도입을 통해 기여하고 있습니다.
북미는 2위를 차지했습니다. 'CHIPS and Science Act'에 따라 이미 TSMC 애리조나 공장에 66억 달러, 인텔에 85억 달러가 투입되어, 224Gbps PAM4의 열 요구 사항을 준수하는 첨단 기판 및 커넥터 케이지의 지역 밀착형 생태계를 뒷받침하고 있습니다. 또한, 항공우주 및 방위 프로그램도 높은 수익률을 가져다주는 견고한 원형 MIL 규격 준수 제품군을 주도하고 있습니다.
유럽은 자동차, 인더스트리 4.0, 의료 분야에서 그 강점을 발휘하고 있습니다. 무할로겐 플라스틱으로의 전환 추진에 따라 많은 OEM이 친환경 하우징의 조기 도입자가 되고 있습니다. 한편, 중동 및 아프리카에서는 하이퍼스케일러에 의한 지역 클라우드 존 구축과, 특히 사우디아라비아 및 UAE에서 정부가 스마트 시티용 광섬유 사업권을 부여함에 따라 연평균 성장률(CAGR) 5.92%가 예상됩니다. 남미 지역은 브라질의 통신 사업과 아르헨티나의 산업 자동화 프로젝트를 중심으로, 견조하지만 다소 낮은 성장률을 보이고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, IT connector market size in 2026 is estimated at USD 8.14 billion, growing from 2025 value of USD 7.72 billion with 2031 projections showing USD 10.58 billion, growing at 5.39% CAGR over 2026-2031.
This report is Segmented by Connector Type (PCB Connectors, IDC Connectors, and More), Mounting Configuration (Board-To-Board, and More), Data-Rate Class (<=10 Gbps, 10-25 Gbps, and More), End-User Industry (IT and Telecom, and More), Application (Servers and Storage, and More), Materials (Standard Thermoplastics, Halogen-Free Compounds), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global IT Connector Market Trends and Insights
Surging demand for high-speed interconnects in hyperscale data centers
Bandwidth-hungry AI clusters are transitioning beyond 224 Gbps per lane, forcing connector designers to mitigate insertion loss and thermal rise inside cramped server trays. Molex cites rapid uptake of optical transceivers for 224 Gbps PAM4 links, noting that heat removal is now as critical as signal integrity. Activities range from evaluating PAM-6 / PAM-8 modulation to deploying co-packaged copper and optics that shorten electrical channels. Hyperscalers plan to bring 120-130 new sites online every year, compressing build schedules to six weeks and favoring high-density connector systems that can be kitted and assembled rapidly.
Rapid 5G / 6G network roll-outs elevating RF connector adoption
Spectrum auctions in markets such as Vietnam for the 2.6 GHz and 3.5 GHz bands are fueling mid-band macro and small-cell deployments. Massive-MIMO radios are scaling from 4T4R to 32T32R, spurring the shift to compact VSFF interfaces that compress fiber counts. Connector vendors are responding with SN-class footprints that quadruple port density inside front-haul shelves, while carrier-neutral host operators expand distributed antenna systems valued at USD 8.7 billion by 2028.
Copper and rare-metal price volatility raising BOM costs
Surging copper and palladium prices have triggered multiple component price notices, such as Panasonic's January 2025 flex PCB increase. High-speed connectors use thick copper alloys and precious-metal platings, so even a 5% upswing can erode gross margins. Vendors are locking annual supply contracts, qualifying alternative platings, and redesigning contact beams to lower mass without compromising insertion cycles.
Other drivers and restraints analyzed in the detailed report include:
- Automotive zonal EE architectures boosting high-speed connectors
- Growth of co-packaged optics accelerating IO connector innovation
- Thermal-mechanical reliability limits at high data rates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PCB connectors accounted for 44.60% of the IT connector market size in 2025, reflecting their ubiquity across motherboards, storage planes, and industrial controllers. Robust pin integrity, proven mating cycles, and broad component ecosystems keep this category entrenched in volume applications. The segment still benefits from the CHIPS Act-driven reshoring of PCB assembly, which lifts domestic demand for fine-pitch mezzanine formats.
The IO/high-speed backplane-and-pluggable group is forecast to grow at 5.55% CAGR, propelled by data center upgrades to QSFP-DD 800 and OSFP Xtreme cages capable of 112 Gbps per channel. RF/VSFF connectors benefit from 5G small-cell densification, while circular and rectangular housings remain essential for harsh-duty industrial controls. Microminiature options are seeing new use cases in robotic surgery and CubeSats that reward every millimeter saved.
Board-to-board held a 35.40% share in 2025 and remains the workhorse for modular sub-assemblies. Stacked mezzanine and card-edge variants help OEMs meet tight Z-height restrictions inside laptops and switch blades. However, wire-to-board is advancing at 6.05% CAGR as designers favor harnesses that simplify maintenance in EV battery packs and household appliances.
Wire-to-wire assemblies continue to service motor drives and HVAC compressors where board real estate is limited. The miniaturization trend now extends across all mounting styles; Molex's rugged miniaturized series offers 20-55% footprint reduction while retaining IP67 sealing, directly addressing robotics and outdoor telecom enclosures.
Complete Report Scope:
- By Connector Type
- PCB Connectors
- IDC Connectors
- IO/High-Speed Backplane and Pluggable
- Circular and Rectangular
- RF/VSFF (SN, CS, MMC)
- Microminiature/Nano Connectors
- By Mounting Configuration
- Board-to-Board
- Wire-to-Board
- Wire-to-Wire/Cable Assemblies
- By Data-Rate Class
- <=10 Gbps
- 10-25 Gbps
- 25-56 Gbps
- >=56 Gbps/PAM4 112 G
- By End-user Industry
- IT and Telecom (incl. Data Centers)
- Consumer Electronics and Computing
- Automotive and e-Mobility
- Industrial Automation/IIoT
- Healthcare and Medical Devices
- By Application
- Servers and Storage
- 5G/6G Base-Stations
- EV Powertrain and ADAS
- Factory Robotics and PLCs
- By Material
- Standard Thermoplastics
- Halogen-free/Eco-friendly Compounds
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- ASEAN
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia Pacific dominated with 45.50% market revenue in 2025, led by China's vertically integrated electronics base and India's fast-growing telecom backbone. Mainland connector producers benefit from provincial incentives aimed at reliability upgrades, with the domestic connector sector forecast to add RMB 12.6 billion year-on-year during 2024. Japan and South Korea contribute through the early adoption of co-packaged optics inside advanced foundry lines.
North America ranks second. The CHIPS and Science Act has already channeled USD 6.6 billion to TSMC Arizona and USD 8.5 billion to Intel, underpinning a localized ecosystem for advanced substrates and connector cages compliant with 224 Gbps PAM4 thermal requirements. Aerospace and defense programs also pull through rugged circular MIL-spec variants that command premium margins.
Europe plays to its strengths in automotive, Industry 4.0, and medical. The push for halogen-free plastics has turned many OEMs into early adopters of eco-class housings. Meanwhile, the Middle East and Africa is set for 5.92% CAGR as hyperscalers install regional cloud zones and governments award smart-city fiber concessions, particularly in Saudi Arabia and the UAE. South America shows steady but lower expansion, weighted toward Brazilian telecom and Argentine industrial automation projects.
- 3M Company
- TE Connectivity Ltd.
- Molex Inc. (Koch)
- Amphenol Corporation
- Samtec Inc.
- Hirose Electric Co., Ltd.
- Aptiv PLC
- Yazaki Corporation
- Hon Hai Precision (FOXCONN)
- Phoenix Contact GmbH and Co. KG
- Harting Technology Group
- JST Mfg. Co., Ltd.
- WAGO Kontakttechnik
- Rosenberger Hochfrequenztechnik
- Bel Fuse Inc.
- Kyocera Corporation
- Luxshare Precision Industry
- JAE (Japan Aviation Electronics)
- Fischer Connectors SA
- CONEC Elektronische Bauelemente GmbH
- Omnetics Connector Corp.
- Wurth Elektronik GmbH and Co. KG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Demand for High-Speed (>25 Gbps) Interconnects in Hyperscale Data Centers
- 4.2.2 Rapid 5G/6G Network Roll-outs Elevating RF and VSFF Connector Adoption in Asia
- 4.2.3 Automotive Zonal EE Architectures Boosting High-Speed Board-to-Board Connectors in EVs
- 4.2.4 Growth of Co-Packaged Optics Accelerating IO Connector Innovation
- 4.2.5 Edge-AI and Industrial IoT Driving Rugged, Sealed Connectors in Factory Automation (EU Focus)
- 4.2.6 United States CHIPS Act-Backed On-Shore PCB Production Lifts Domestic Connector Demand
- 4.3 Market Restraints
- 4.3.1 Copper and Rare-Metal Price Volatility Raising BOM Costs
- 4.3.2 Thermal-Mechanical Reliability Limits at >=112 Gbps PAM4
- 4.3.3 Lengthy Automotive PPAP Cycles Slowing Connector Design-ins
- 4.3.4 Regulatory Push for Halogen-Free Plastics Increasing Re-qualification Costs (EU)
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Connector Type
- 5.1.1 PCB Connectors
- 5.1.2 IDC Connectors
- 5.1.3 IO/High-Speed Backplane and Pluggable
- 5.1.4 Circular and Rectangular
- 5.1.5 RF/VSFF (SN, CS, MMC)
- 5.1.6 Microminiature/Nano Connectors
- 5.2 By Mounting Configuration
- 5.2.1 Board-to-Board
- 5.2.2 Wire-to-Board
- 5.2.3 Wire-to-Wire/Cable Assemblies
- 5.3 By Data-Rate Class
- 5.3.1 <=10 Gbps
- 5.3.2 10-25 Gbps
- 5.3.3 25-56 Gbps
- 5.3.4 >=56 Gbps/PAM4 112 G
- 5.4 By End-user Industry
- 5.4.1 IT and Telecom (incl. Data Centers)
- 5.4.2 Consumer Electronics and Computing
- 5.4.3 Automotive and e-Mobility
- 5.4.4 Industrial Automation/IIoT
- 5.4.5 Healthcare and Medical Devices
- 5.5 By Application
- 5.5.1 Servers and Storage
- 5.5.2 5G/6G Base-Stations
- 5.5.3 EV Powertrain and ADAS
- 5.5.4 Factory Robotics and PLCs
- 5.6 By Material
- 5.6.1 Standard Thermoplastics
- 5.6.2 Halogen-free/Eco-friendly Compounds
- 5.7 Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Russia
- 5.7.2.7 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 South Korea
- 5.7.3.4 India
- 5.7.3.5 ASEAN
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 South America
- 5.7.4.1 Brazil
- 5.7.4.2 Argentina
- 5.7.4.3 Rest of South America
- 5.7.5 Middle East and Africa
- 5.7.5.1 Saudi Arabia
- 5.7.5.2 United Arab Emirates
- 5.7.5.3 Turkey
- 5.7.5.4 South Africa
- 5.7.5.5 Rest of Middle East and Africa
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 3M Company
- 6.4.2 TE Connectivity Ltd.
- 6.4.3 Molex Inc. (Koch)
- 6.4.4 Amphenol Corporation
- 6.4.5 Samtec Inc.
- 6.4.6 Hirose Electric Co., Ltd.
- 6.4.7 Aptiv PLC
- 6.4.8 Yazaki Corporation
- 6.4.9 Hon Hai Precision (FOXCONN)
- 6.4.10 Phoenix Contact GmbH and Co. KG
- 6.4.11 Harting Technology Group
- 6.4.12 JST Mfg. Co., Ltd.
- 6.4.13 WAGO Kontakttechnik
- 6.4.14 Rosenberger Hochfrequenztechnik
- 6.4.15 Bel Fuse Inc.
- 6.4.16 Kyocera Corporation
- 6.4.17 Luxshare Precision Industry
- 6.4.18 JAE (Japan Aviation Electronics)
- 6.4.19 Fischer Connectors SA
- 6.4.20 CONEC Elektronische Bauelemente GmbH
- 6.4.21 Omnetics Connector Corp.
- 6.4.22 Wurth Elektronik GmbH and Co. KG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment