|
시장보고서
상품코드
2124558
산업용 레이저 시스템 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Industrial Laser System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
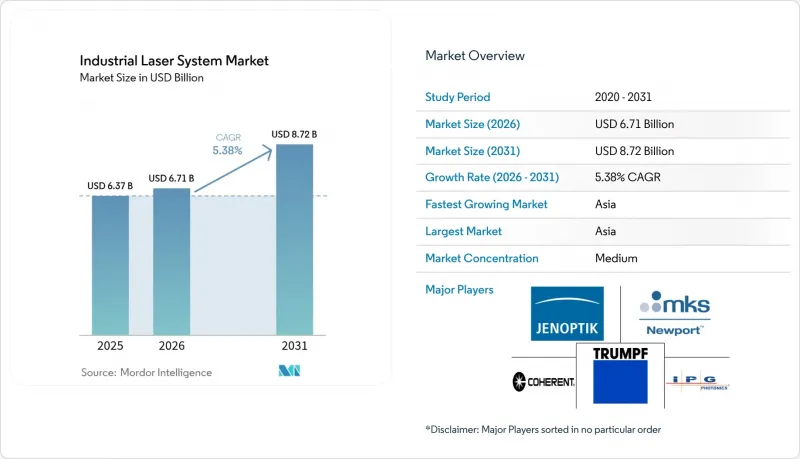
에 의하면, 산업용 레이저 시스템 시장 규모는 2025년 63억 7,000만 달러로 평가되었습니다. 2026년에는 67억 1,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 5.38%로 성장을 지속하여, 2031년에는 87억 2,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 레이저의 유형(파이버 레이저, 고체 레이저 등), 출력 범위(저출력(1kW 미만),중출력(1-6 kW) 등), 용도(절단, 용접·브레이징, 마킹·조각 등), 최종 사용자 산업(반도체 및 전자, 자동차, 의료기기 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 산업용 레이저 시스템 시장 동향 및 인사이트
자동차 제조 분야에서 기계식에서 레이저식으로의 금속 절단 방식의 급속한 전환
각 자동차 제조업체는 섀시 및 배터리 인클로저의 생산 주기를 단축하고, 절단면 품질을 향상시키며, 스크랩을 최소화하기 위해 파이버 레이저 라인의 표준화를 추진하고 있습니다. 독일의 한 공장에서는 플라즈마 커터를 6kW 파이버 레이저 장비로 교체한 결과, 가공 시간이 40% 단축되었다고 보고되었습니다. 아시아의 전기차 제조업체들도 이에 발맞추어, 계속 증가하는 차량 생산 대수에 대응하면서 경량화로 높은 평가를 받고 있는 알루미늄·강철 하이브리드 설계를 지원하기 위해 수 kW급 장비를 도입하고 있습니다. 이와 유사한 동향은 유럽에서 2035년 내연기관의 단계적 폐지에 대비하는 공급업체들에게도 미치고 있으며, 산업용 레이저 시스템 시장 전체의 장기적인 수요를 확고히 하고 있습니다.
5G/AI 칩 제조의 보급으로 인해 서브미크론 바홀용 레이저에 대한 수요가 증가하고 있습니다.
3nm 및 2nm의 첨단 노드에서는 다층 기판에서 신호의 무결성을 유지하기 위해 펨토초 드릴링 기술이 필요합니다. 대만, 한국, 미국에서는 100fs 펄스로 열영향 영역을 피할 수 있는 고정밀 플랫폼의 도입이 진행되고 있습니다. 광학 부품 제조업체들이 생산 능력 확대에 어려움을 겪고 있어 납기 기간이 1년 이상으로 길어지고 있지만, 칩 파운드리 업체들은 계속해서 여러 대의 장비를 계약하고 있으며, 이는 산업용 레이저 시스템 시장의 확대로 이어지고 있습니다.
자본 집약적인 6kW 초과 시스템은 Tier 2 수탁 제조업체로의 보급을 제한하고 있습니다.
현재 고출력 유닛의 가격은 50만 달러 이상이며, 인프라(칠러, 3상 배선, 클래스 1 인클로저 등) 비용으로 인해 그 지출이 2배로 늘어날 수도 있습니다. 동남아시아, 라틴아메리카, 동유럽의 중소 제조업체들은 환율 변동과 리스 옵션 부족에 직면해 있어, OEM이 더 두꺼운 판재 절단을 추진하고 있음에도 불구하고 도입 속도는 둔화되고 있습니다. 그 결과, 생산성 향상이 명백함에도 불구하고 산업용 레이저 시스템 시장의 일부 부문에서는 여전히 수요가 충분히 충족되지 못하고 있는 상황입니다.
부문별 분석
2025년에는 파이버 광원이 매출의 51.25%를 차지했습니다. 이는 견고한 구조, 높은 벽면 콘센트 효율, 모션 플랫폼과의 손쉬운 통합을 반영한 결과입니다. 이러한 우위는 시간당 가동 시간을 중시하는 자동차 업계나 반도체 제조 공장에서 두드러지게 나타납니다. 이테르븀 다이오드의 지속적인 가격 하락에 힘입어, 파이버 시스템 분야의 산업용 레이저 시스템 시장 규모는 연평균 성장률(CAGR) 5.25%로 확대될 것으로 예측됩니다. 초고속 레이저 시장 규모는 작지만, 전자, 의료, 디스플레이 분야의 고객들이 200 fs 미만의 펄스 폭을 채택함에 따라 연평균 성장률(CAGR) 6.05%로 확대되고 있습니다. 냉각 기술의 혁신과 OPCPA 펌핑 아키텍처 덕분에 평균 출력이 향상되어, 과거에는 연속파(CW) 장치가 선호되었던 대량 생산의 처리량이 가능해졌습니다.
고체·디스크형 아키텍처는 특수 합금이나 두꺼운 구리 절단에 적합한 틈새 파장을 지원하는 반면, CO2 장치는 장파장 특성으로 인해 금속 절단 효율이 떨어지기 때문에 두꺼운 아크릴이나 목재 용도로만 제한됩니다. 직접 다이오드 어레이는 빔 품질의 허용 범위가 넓고, 50%의 전기 효율로 운영 비용을 절감할 수 있는 클래딩 가공, 경화 처리 및 폴리머 용접 작업에 대응하고 있습니다. 엑시머 시스템은 반도체 리소그래피 및 카테터용 천공 가공에 계속해서 활용되고 있지만, 양자 캐스케이드 설계는 현재 연구 개발 단계에 있습니다. 다만, 향후 10년 후반에는 중적외선 어블레이션 시장을 개척할 가능성이 있습니다. 전반적으로 이러한 동향으로 인해 산업용 레이저 시스템 시장의 기술 다양성은 높은 수준을 유지하고 있습니다.
1-6kW급 시스템은 설비 투자 비용과 판금 가공 속도의 균형이 잘 잡혀 있어, 2025년 매출의 거의 절반을 차지했습니다. 자동차 부품 하청업체들은 2mm 두께의 강판을 30m/min의 속도로 가공할 수 있으며 가격도 합리적인 4kW 커터를 선호하고 있습니다. 이 출력 대역에서 산업용 레이저 시스템 시장 점유율은 고출력 기종이 등장하더라도 안정적으로 유지될 것으로 예측됩니다. 6kW를 초과하는 플랫폼은 두께 100mm의 강판을 한 번의 패스로 가공해야 하는 조선소, 교량 건설 현장, 중장비 제조업체 덕분에 연평균 성장률(CAGR) 5.85%로 성장하고 있습니다. 조기 도입 기업들로부터는 높은 설비 투자 비용을 2년 이내에 회수할 수 있을 정도의 인력 절감 효과가 보고되고 있습니다.
1 kW 미만의 나노초·연속파 레이저 장치는 속도보다 열 제어가 우선시되는 인쇄 회로 기판, 센서 하우징, 스텐트 가공에 사용됩니다. 각 OEM 업체들은 이러한 저출력 헤드를 갈바노미터 스캐너와 결합함으로써, 10µm의 위치 정밀도를 유지하면서 500 mm/s의 조각 속도를 실현하고 있습니다. 이러한 각 요소가 결합되어 모든 재료의 두께와 생산성 목표에 적합한 레이저가 제공되며, 산업용 레이저 시스템 시장 전반에 걸쳐 광범위한 출력 범위가 유지되고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 45.70%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.35%를 나타낼 것으로 전망됩니다. 중국의 ‘중국 제조 2025’ 정책은 반도체 메가팹, 전기차 생산 라인, 태양광 발전소에 자금을 지원하고 있으며, 이러한 시설에서는 절단 및 용접에 고휘도 파이버 시스템이 채택되고 있습니다. 한국 및 일본의 디스플레이 제조업체들은 OLED 및 마이크로 LED 프로젝트를 추진하기 위해 펨토초 플랫폼을 발주하고 있습니다. 동남아시아의 수탁 제조업체들은 정부의 수입 관세 감면 조치에 힘입어 가전제품 케이스 가공용으로 1-3kW급 커터를 채택하고 있습니다. 현지 서비스 네트워크, 풍부한 엔지니어 인력, 그리고 광범위한 공급망을 통해 자본 효율성이 높은 수준으로 유지되며, 산업용 레이저 시스템 시장에서의 선도적 입지가 강화되고 있습니다.
유럽에서는 독일, 이탈리아, 스웨덴을 중심으로 도입이 가속화되고 있습니다. 프리미엄 브랜드들이 알루미늄 화이트 바디 및 배터리 인클로저로의 전환을 추진함에 따라, 차량 1대당 레이저 탑재량이 증가하고 있습니다. EU의 ‘Fit-for-55’ 규제는 터빈 블레이드의 텍스처링 및 수소 대응 파이프라인의 용접을 의무화하고 있으며, 이 두 가지 모두 고출력 레이저 수요를 뒷받침하고 있습니다. 스웨덴과 프랑스의 배터리 기가팩토리 건설에서는 인라인 X선 검사와 연동된 레이저 용접 라인이 채택되고 있는 반면, 툴루즈와 함부르크의 항공우주 거점에서는 구조용 브래킷을 위한 레이저 분말 침적 용융(LPBF) 기술에 대한 투자가 진행되고 있습니다. 전반적으로 정책, 지속가능성 목표, 그리고 엔지니어링의 전통이 어우러져 유럽은 산업용 레이저 시스템 시장의 중심적 지위를 유지하고 있습니다.
북미에서는 국방, 항공우주 및 국내 반도체 산업의 리쇼어링(reshoring) 노력에 힘입어 꾸준한 성장이 나타나고 있습니다. ‘CHIPS and Science Act’에 따라 비아홀 가공 공구에 대한 자본 인센티브가 제공되며, 미국 국방부는 메가와트급 파이버 레이저 시연 장비에 자금을 지원하고 있습니다. 멕시코의 1차 자동차 부품 공급업체들은 OEM의 추적성 기준을 충족하기 위해 4kW 장치로의 전환을 추진하고 있는 반면, 캐나다의 광산기계 제조업체들은 담금질 및 템퍼링 처리된 강판을 가공하기 위해 20kW 장비를 도입하고 있습니다. 라틴아메리카 및 중동 및 아프리카는 여전히 신흥 시장 기회로 남아 있습니다. 브라질의 농업 기계, 사우디아라비아의 해수 담수화 플랜트, 남아프리카공화국의 철도 차량 공장에서는 중출력 레이저의 시범 도입이 진행되고 있지만, 자금 조달 문제와 현장 서비스 체계의 부족으로 인해 보급률은 여전히 낮은 수준에 머물러 있습니다. 그럼에도 불구하고, 산업용 레이저 시스템 시장 전체에서 그 성장 가능성은 널리 인정받고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the industrial laser system market size is expected to grow from USD 6.37 billion in 2025 to USD 6.71 billion in 2026 and is forecast to reach USD 8.72 billion by 2031 at 5.38% CAGR over 2026-2031.
This report is Segmented by Laser Type (Fiber Lasers, Solid-State Lasers, and More), Power Range (Low Power (Less Than 1 KW), Medium Power (1-6 KW), and More), Application (Cutting, Welding and Brazing, Marking and Engraving, and More), End-User Industry (Semiconductor and Electronics, Automotive, Medical Devices, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Laser System Market Trends and Insights
Rapid transition from mechanical to laser-based metal cutting in automotive manufacturing
Automakers are standardizing fiber laser lines to shorten chassis and battery-enclosure cycles, boost edge quality, and minimize scrap. German plants report 40% shorter processing time when swapping plasma cutters for 6 kW fiber units. Asian EV producers follow with multi-kilowatt installations that keep pace with rising vehicle output while supporting aluminum-steel hybrid designs prized for lightweighting. The same trend reaches suppliers preparing for Europe's 2035 internal-combustion phase-out, cementing long-term demand across the industrial laser system market.
Proliferation of 5G/AI chip fabrication demanding sub-micron via-hole lasers
Advanced nodes at 3 nm and 2 nm require femtosecond drilling to preserve signal integrity in multilayer substrates. Taiwan, South Korea, and the United States are installing high-precision platforms whose 100-fs pulses avoid heat-affected zones. Delivery lead times have stretched past one year because optical-component makers struggle to expand capacity, yet chip foundries continue signing multi-tool contracts that widen the industrial laser system market.
Capital-intensive >6 kW systems limit penetration into tier-2 job shops
High-power units now cost upward of USD 500,000, and the infrastructure-chillers, three-phase wiring, Class 1 enclosures-can double that outlay. Smaller fabricators in Southeast Asia, Latin America, and Eastern Europe face currency swings and scarce leasing options, slowing adoption even as OEMs push for thicker-plate cutting. As a result, segments of the industrial laser system market remain under-served despite clear productivity gains
Other drivers and restraints analyzed in the detailed report include:
- Battery-pack welding needs in e-mobility gigafactories-Europe-led
- Growing adoption of ultrafast lasers for OLED and micro-LED processing-Asia
- Stringent IEC/EN 60825-1 safety re-certification costs for retrofitted lines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fiber sources accounted for 51.25% of revenue in 2025, reflecting their rugged build, high wall-plug efficiency, and easy integration with motion platforms. Their dominance is visible in automotive and semiconductor fabs that depend on hour-by-hour uptime. The industrial laser system market size for fiber systems is expected to expand at 5.25% CAGR, supported by ongoing price drops in ytterbium diodes. Ultrafast lasers, despite a smaller base, add 6.05% CAGR as electronics, medical, and display customers adopt pulse widths under 200 fs. Cooling innovations and OPCPA pumping architectures raise average power, enabling mass-production throughput that once favored continuous-wave tools.
Solid-state and disc architectures serve niche wavelengths that suit exotic alloys or thick copper cutting, whereas CO2 units retreat to thick acrylic or wood applications because their long wavelength lacks efficiency in metals. Direct-diode arrays address cladding, hardening, and polymer welding tasks where beam quality tolerance is higher and 50% electrical efficiency lowers operating cost. Excimer systems persist in semiconductor lithography and catheter hole drilling, while quantum cascade designs sit in R&D but could unlock mid-IR ablation markets later in the decade. Collectively, these dynamics keep technology diversity high within the industrial laser system market.
Systems rated 1-6 kW generated almost half of 2025 revenue as they balance capital cost against sheet-metal speed. Automotive sub-contractors favor 4 kW cutters that process 2 mm steel at 30 m/min while remaining affordable. The industrial laser system market share for this band is projected to remain stable even as high-power units gain ground. Platforms above 6 kW grow 5.85% CAGR thanks to shipyards, bridge yards, and heavy-equipment makers that need 100 mm-thick steel processing in single passes. Early adopters report labor savings that compensate for higher capex within two years.
Below 1 kW, nanosecond and continuous-wave tools process printed circuit boards, sensor housings, and stents where heat control trumps speed. OEMs pair these low-power heads with galvanometer scanners to achieve 500 mm/s engraving while holding 10 µm positional accuracy. Together, the tiers ensure every material thickness and productivity target has a matching laser, maintaining a broad power-range spectrum across the industrial laser system market.
Complete Report Scope:
- By Laser Type
- Fiber Lasers
- Solid-State Lasers
- Nd:YAG
- Disc Lasers
- CO2 Lasers
- Excimer Lasers
- Direct Diode Lasers
- Other Lasers (Ultrafast, QCW, QCL)
- By Power Range
- Low Power (Less than 1 kW)
- Medium Power (1-6 kW)
- High Power (Above 6 kW)
- By Application
- Cutting
- 2D Cutting
- 3D Cutting
- Welding and Brazing
- Marking and Engraving
- Drilling and Micro-Processing
- Surface Treatment (Cladding, Hardening, Texturing)
- Additive Manufacturing
- Cutting
- By End-user Industry
- Automotive
- Semiconductor and Electronics
- Aerospace and Defense
- Medical Devices
- Energy (Battery, Solar)
- Heavy Machinery and Tools
- Jewelry and Artisanal
- Others (Packaging, General Mfg.)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Nordics
- Rest of Europe
- South America
- Brazil
- Rest of South America
- Asia-Pacific
- China
- Japan
- India
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Gulf Cooperation Council Countries
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific commanded 45.70% of 2025 revenue and is projected at a 6.35% CAGR through 2031. China's "Made-in-China 2025" policy funds semiconductor mega-fabs, EV lines, and photovoltaic plants that turn to high-brightness fiber systems for cutting and welding. South Korean and Japanese display makers order femtosecond platforms to advance OLED and micro-LED projects. Southeast Asian contract manufacturers embrace 1-3 kW cutters for appliance chassis, aided by government import-duty relief. Local service networks, surplus engineering talent, and extensive supply chains keep capital efficiency high, reinforcing leadership in the industrial laser system market
Europe follows with strong installation momentum anchored in Germany, Italy, and Sweden. Automotive laser content per vehicle rises as premium brands shift toward aluminum body-in-white and battery enclosures. EU "Fit-for-55" rules require turbine blade texturing and hydrogen-ready pipeline welding; both favor high-power lasers. Battery gigafactory build-outs in Sweden and France adopt laser welding lines synced with inline X-ray inspection, while aerospace hubs in Toulouse and Hamburg invest in laser powder bed fusion for structural brackets. Overall, policy, sustainability targets, and engineering heritage combine to keep Europe central to the industrial laser system market.
North America shows steady expansion propelled by defense, aerospace, and domestic semiconductor reshoring efforts. The CHIPS and Science Act frees capital incentives for via-hole drilling tools, and the Pentagon funds megawatt fiber laser demonstrators. Tier-1 automotive suppliers in Mexico transition to 4 kW units to meet OEM traceability standards, while Canadian mining-equipment builders install 20 kW machines to process quenched-and-tempered plate. Latin America and the Middle East & Africa remain emerging opportunities: Brazilian agri-machinery, Saudi desalination plants, and South African railcar factories pilot mid-power lasers, yet penetration stays low due to financing gaps and limited field service. Nonetheless, growth potential is recognized across the wider industrial laser system market.
- TRUMPF GmbH + Co. KG
- Coherent Corp.
- IPG Photonics Corporation
- Han's Laser Technology Industry Group Co., Ltd.
- Jenoptik AG
- nLIGHT, Inc.
- II-VI Incorporated
- Newport Corporation (MKS Instruments)
- Lumentum Holdings Inc.
- Fanuc Corporation
- Prima Industrie S.p.A.
- Bystronic Laser AG
- Amada Co., Ltd.
- Miyachi Unitek (Amada Weld Tech)
- Rofin-Sinar Technologies
- GWEIKE Laser
- Trotec Laser GmbH
- Epilog Laser
- ACSYS Lasertechnik GmbH
- Alpha Laser GmbH
- Lasea S.A.
- LaserStar Technologies Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Transition from Mechanical to Laser?Based Metal Cutting in Automotive Manufacturing
- 4.2.2 Proliferation of 5G/AI Chip Fabrication Demanding Sub-Micron Via-Hole Lasers
- 4.2.3 Battery-Pack Welding Needs in e-Mobility Gigafactories-Europe-Led
- 4.2.4 Growing Adoption of Ultrafast Lasers for OLED and Micro-LED Processing-Asia
- 4.2.5 Laser-Based Additive Manufacturing in Aerospace Lightweighting-U.S.-Centric
- 4.2.6 EU "Fit-for-55" Drives Laser Surface-Texturing for Energy-Efficient Turbines
- 4.3 Market Restraints
- 4.3.1 Capital-Intensive Above 6 kW Systems Limit Penetration into Tier-2 Job-Shops
- 4.3.2 Stringent IEC/EN 60825-1 Safety Re-Certification Costs for Retrofitted Lines
- 4.3.3 Heat-Affected Zone (HAZ) Micro-Cracking in Next-Gen Battery Foils
- 4.3.4 Volatile Rare-Earth (Yb, Nd) Supply Chain from China Elevates Laser BOM Cost
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Laser Type
- 5.1.1 Fiber Lasers
- 5.1.2 Solid-State Lasers
- 5.1.2.1 Nd:YAG
- 5.1.2.2 Disc Lasers
- 5.1.3 CO2 Lasers
- 5.1.4 Excimer Lasers
- 5.1.5 Direct Diode Lasers
- 5.1.6 Other Lasers (Ultrafast, QCW, QCL)
- 5.2 By Power Range
- 5.2.1 Low Power (Less than 1 kW)
- 5.2.2 Medium Power (1-6 kW)
- 5.2.3 High Power (Above 6 kW)
- 5.3 By Application
- 5.3.1 Cutting
- 5.3.1.1 2D Cutting
- 5.3.1.2 3D Cutting
- 5.3.2 Welding and Brazing
- 5.3.3 Marking and Engraving
- 5.3.4 Drilling and Micro-Processing
- 5.3.5 Surface Treatment (Cladding, Hardening, Texturing)
- 5.3.6 Additive Manufacturing
- 5.3.1 Cutting
- 5.4 By End-user Industry
- 5.4.1 Automotive
- 5.4.2 Semiconductor and Electronics
- 5.4.3 Aerospace and Defense
- 5.4.4 Medical Devices
- 5.4.5 Energy (Battery, Solar)
- 5.4.6 Heavy Machinery and Tools
- 5.4.7 Jewelry and Artisanal
- 5.4.8 Others (Packaging, General Mfg.)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Nordics
- 5.5.2.5 Rest of Europe
- 5.5.3 South America
- 5.5.3.1 Brazil
- 5.5.3.2 Rest of South America
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South-East Asia
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Gulf Cooperation Council Countries
- 5.5.5.1.2 Turkey
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 TRUMPF GmbH + Co. KG
- 6.4.2 Coherent Corp.
- 6.4.3 IPG Photonics Corporation
- 6.4.4 Han's Laser Technology Industry Group Co., Ltd.
- 6.4.5 Jenoptik AG
- 6.4.6 nLIGHT, Inc.
- 6.4.7 II-VI Incorporated
- 6.4.8 Newport Corporation (MKS Instruments)
- 6.4.9 Lumentum Holdings Inc.
- 6.4.10 Fanuc Corporation
- 6.4.11 Prima Industrie S.p.A.
- 6.4.12 Bystronic Laser AG
- 6.4.13 Amada Co., Ltd.
- 6.4.14 Miyachi Unitek (Amada Weld Tech)
- 6.4.15 Rofin-Sinar Technologies
- 6.4.16 GWEIKE Laser
- 6.4.17 Trotec Laser GmbH
- 6.4.18 Epilog Laser
- 6.4.19 ACSYS Lasertechnik GmbH
- 6.4.20 Alpha Laser GmbH
- 6.4.21 Lasea S.A.
- 6.4.22 LaserStar Technologies Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment