|
시장보고서
상품코드
2124631
유량계 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Flow Meters - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
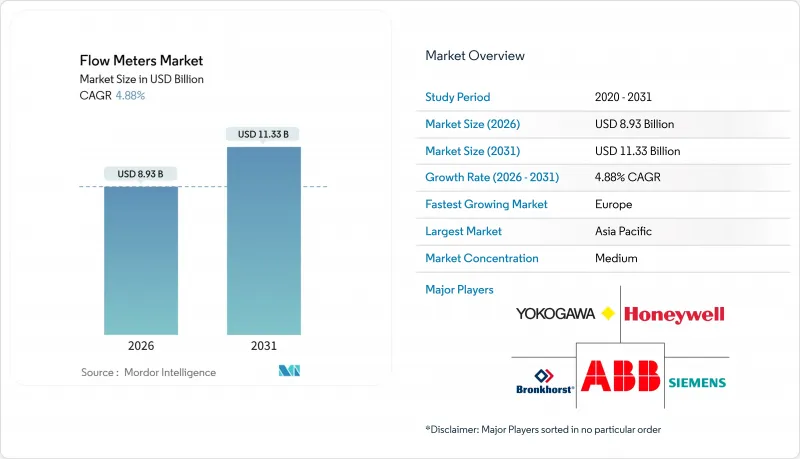
에 의하면, 유량계 시장 규모는 2026년에 89억 3,000만 달러로 평가되고 2031년까지 113억 3,000만 달러에 이를 것으로 예측됩니다.
이는 예측 기간 동안 연평균 성장률(CAGR)이 4.88%임을 나타냅니다.
본 보고서는 기술별(용적식, 질량식), 설치 방식별(인라인형, 클램프온형, 삽입형), 유체 유형별(액체, 기체, 증기), 최종 사용자 산업(석유 및 가스,상하수도, 화학, 전력, 식품 및 음료, 의약품), 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 제시되어 있습니다.
세계의 유량계 시장 동향 및 인사이트
실시간 유량 분석을 실현하는 IoT 지원 공정 자동화
산업 현장에서는 각 장치가 1초 간격의 데이터 스트림을 제공하는 엣지 컴퓨팅 노드가 될 수 있도록 유량계 업그레이드가 진행되고 있습니다. 요코가와(Yokogawa)의 OpreX와 같은 플랫폼은 드리프트와 캐비테이션을 분석하여 설정값의 ±0.5%를 유지하기 위해 제어 밸브를 자동으로 조정합니다. 제약 업계의 연속 생산 라인에서는 미국 식품의약국(FDA)의 공정 분석 기술 지침 범위 내를 유지하기 위해 유사한 피드백 루프가 활용되고 있습니다. 지멘스는 자사의 초음파 유량계에 내장된 예측 분석 기능을 통해 2025년까지 화학 플랜트의 예정되지 않은 가동 중단 시간을 22% 줄일 수 있다고 발표했습니다. 또한, 실시간 가시화 기능은 기업용 소프트웨어와도 연동되어 있으며, 한 유럽 음료 제조업체는 전자기 유량계를 SAP S/4HANA와 연동하여 원자재 손실을 14% 줄였습니다.
전 세계 상수도 및 하수도 인프라에 대한 투자
누수로 인해 처리된 물의 25%에서 40%를 잃고 있는 상수도 유틸리티자들은 기계식 계량기를 배터리 구동식 초음파 및 전자기식 계량기로 교체하고 있습니다. 중국은 2025년까지 100개 도시의 네트워크를 디지털화하기 위해 1,500억 위안(210억 달러)을 예산에 편성했습니다. 인도의 ‘Jal Jeevan Mission’에서는 선불식 계량기가 도입되어, 자이푸르에서는 18개월 만에 비수익 수돗물 비율이 42%에서 28%로 감소했습니다. 미국에서는 ‘초당적 인프라 법안’에 따라 550억 달러가 1시간 단위로 데이터를 수집할 수 있는 첨단 계량 시스템 도입에 배정되었습니다. 유럽의 한 컨설팅 회사의 추산에 따르면, 스마트 계량기로 감지되지 않았던 물 손실이 해소되면 연간 80억 유로의 회수가 예상됩니다.
첨단 코리올리식 및 초음파식 계량기의 높은 설비 투자 비용
구매 가격은 전자기식이나 와류식 대체 제품에 비해 3배에서 10배나 높아, 자금 사정에 어려움을 겪는 상수도 유틸리티자들이 교체를 미루는 요인이 되고 있습니다. 4인치 코리올리식 계량기의 가격은 1만 2,000-1만 8,000달러인 반면, 같은 크기의 전자기식 계량기는 2,500-4,000달러입니다. 전용 설치, 방진 대책, 제로 조정 등의 절차로 인해 설치 비용에 추가로 3,000-5,000달러가 더해집니다. 라이프사이클 비용의 관점에서는 고가형 계량기가 유리하지만, 조달 담당 팀은 초기 비용에 중점을 두는 경우가 많습니다. 자본 지출을 운영비로 전환하고 도입을 가속화하기 위해, 구독형 ‘미터-어-서비스(Meter-as-a-Service)’와 같은 서비스가 등장하고 있습니다.
부문별 분석
질량식 측정법은 2025년에 26억 달러를 차지하며 연평균 성장률(CAGR) 7.4%로 확대되고 있습니다. 수소 혼합이나 이산화탄소 포집 및 저장(CCS)에서는 밀도 변화에 영향을 받지 않는 직접적인 질량 측정이 요구되므로, 유량계 시장이 그 혜택을 받고 있습니다. 코리올리식 유량계는 액화 CO₂ 거래량 측정에서 표준적인 선택지로 자리 잡고 있으며, 노르웨이의 노던 라이츠(Northern Lights) CCS 프로젝트가 대표적인 사례입니다. 이 프로젝트에서는 100바의 압력 하에서 ±0.05%의 불확실도를 실현하며 가동되고 있습니다. 초음파식 유량계는 수소의 체적비가 20%에 달하고,도 ±1.5%의 정확도를 유지할 수 있어, 가스 공급 분야에서 터빈식 유량계를 대체하고 있습니다.
용적식 기술은 도시 상수도망의 전자기 유량계에 힘입어 2025년 매출의 28.9%를 계속 차지했습니다. 차압식 오리피스 플레이트는 10-20 직경 길이의 직관을 필요로 하지만, 증기 배관에서는 여전히 일반적입니다. 열식 질량 센서는 저유량으로 인해 터빈식 유량계의 성능이 저하되는 바이오가스나 압축 공기 루프에서 빠르게 보급되고 있습니다. 용적식 유량계는 연료 주입이나 고점도 액체의 배치 처리에서 여전히 사용되고 있습니다. 와류 유량계는 발전소의 증기용으로 중저가 대에서 유지보수 부담이 적은 대안으로 자리 잡고 있습니다. 이러한 동향은 전반적으로 디지털 트윈 소프트웨어와 원활하게 통합되는 고정밀도 및 자가 진단 기능을 갖춘 장치로의 유량계 업계 내 구조적 전환을 여실히 보여주고 있습니다.
인라인형 하드웨어는 2025년 매출의 48.2%를 차지했지만, 기존 시설(브라운필드)에서는 배관을 절단할 경우 가동 중단으로 인한 손실이 발생하기 때문에 성장률은 4.2%로 완만합니다. 대조적으로, 클램프온형은 5.9%의 성장률로 확대되고 있으며, 감압 없이 설치가 가능합니다. 북미의 중류 사업자는 클램프온형 초음파 계측 장치를 사용하여 8주 만에 120개의 배관을 개조함으로써, 인라인형 대안에 비해 비용을 62% 절감했습니다. 배관에 삽입하는 방식, 즉 배관의 일부를 교체하지 않는 삽입형 프로브는 대구경 상수도 본관에서 틈새 수요를 찾아내고 있습니다.
배터리 기술의 혁신으로 현장에서의 수명이 10-15년으로 연장되었으며, 유량계가 무선 IoT 노드로 기능하게 되었습니다. 안전 무결성 레벨 2(SIL 2) 기능 안전 인증 획득에 따라 대상 시장은 원자력 발전소 및 제약 공장으로 확대되고 있습니다. 그럼에도 불구하고, 거래량 측정 지점에서는 여전히 ±0.1%의 정확도를 보장하는 인라인식 유량계가 주류를 이루고 있습니다. 현재 유량계 시장은 기계적 구조와 마찬가지로 허용 오차에 따라 세분화되어 있으며, 최종 사용자는 비용, 정확도, 가동 중단 시간 방지를 종합적으로 고려하여 선택하고 있습니다.
지역별 분석
아시아태평양은 중국의 1,500억 위안 규모의 스마트 상수도 이니셔티브와 인도의 누수 감지 의무화에 힘입어 2025년 매출의 38.9%를 차지했습니다. 일본은 화학 및 전자 플랜트에서 엣지 컴퓨팅 분석을 활용하고 있으며, 한국은 확대되는 반도체 팹에 열질량 센서를 도입하고 있습니다. 또한, 호주의 대규모 수소 시범 파이프라인과 말레이시아의 LNG 수출 확대도 성장에 기여하고 있습니다.
유럽은 연평균 성장률(CAGR) 5.3%로 성장을 주도할 것으로 전망됩니다. 독일의 수소 혼합 규제로 인해 수백만 대의 계량기가 초음파 기술로 전환되고 있으며, 덴마크의 지역 난방 네트워크에서는 유럽연합(EU)의 에너지 효율 규정을 준수하기 위해 열량계가 도입되고 있습니다. 또한, 영국은 누수율을 50% 감축하겠다는 목표를 내걸고 있으며, 이것이 스마트 계량기 조달을 촉진하고 있습니다. 더불어, 노르웨이의 CCS(이산화탄소 포집 및 저장) 프로젝트와 프랑스의 수소 충전소가 카스토디-트랜스퍼용 코리올리 유량계 수요를 가속화하고 있습니다.
북미는 4.6%의 성장률을 보이고 있는데, 이는 미국이 상수도 인프라에 550억 달러를 투자하고, 중류 석유 사업자들이 카스토디 미터의 현대화를 추진하고 있는 것이 배경입니다. 중동에서는 해수 담수화에 막대한 투자가 이루어지고 있으며, 급수 및 농축액 모니터링에 전자기식 계측기가 활용되고 있습니다. 남미에서는 브라질의 유틸리티 민영화로 인해 스마트 미터에 대한 자금 조달이 가능해져 전망이 개선되고 있습니다. 한편, 아프리카에서는 남아프리카공화국의 선불식 지자체용 계량기 설치나 나이지리아의 대량 공급용 계량기 시범 도입 등 지역별로 진전이 나타나고 있습니다. 이러한 지역별 프로그램들이 종합적으로 유량계 시장의 광범위한 세계 기반을 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the flow meters market size is valued at USD 8.93 billion in 2026 and is projected to reach USD 11.33 billion by 2031, reflecting a 4.88% CAGR over the forecast period.
This report is Segmented by Technology (Volumetric, and Mass), Mounting (In-Line, Clamp-On, and Insertion), Fluid Type (Liquid, Gas, and Steam), End-User Industry (Oil and Gas, Water and Wastewater, Chemicals, Power, Food and Beverage, and Pharmaceuticals), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, Africa). Market Forecasts are Provided in Value (USD).
Global Flow Meters Market Trends and Insights
IoT-Enabled Process Automation For Real-Time Flow Analytics
Industrial sites are upgrading meters so that each device becomes an edge-computing node delivering one-second interval data streams. Platforms such as Yokogawa OpreX analyze drift and cavitation, then automatically adjust control valves to maintain +-0.5% set-points. Pharmaceutical continuous-manufacturing lines rely on the same feedback loops to stay within U.S. Food and Drug Administration process analytical technology guidelines. Siemens disclosed that predictive analytics embedded in its ultrasonic meters cut unscheduled chemical-plant downtime by 22% in 2025. Real-time visibility also links with enterprise software; a European beverage producer tied electromagnetic meters to SAP S/4HANA and trimmed raw-material waste by 14%.
Global Water And Wastewater Infrastructure Investments
Utilities losing 25% to 40% of treated water to leaks are replacing mechanical meters with battery-powered ultrasonic and electromagnetic alternatives. China earmarked CNY 150 billion (USD 21 billion) in 2025 to digitize networks across 100 cities. India's Jal Jeevan Mission introduced prepaid meters that lowered non-revenue water from 42% to 28% in Jaipur within 18 months. In the United States, USD 55 billion from the Bipartisan Infrastructure Law channels funding toward hourly-data advanced metering installations. European consulting estimates show potential recovery of EUR 8 billion annually if smart meters eliminate undetected losses.
High CAPEX Of Advanced Coriolis And Ultrasonic Meters
Acquisition prices run three to ten times higher than electromagnetic or vortex alternatives, prompting cash-constrained utilities to delay upgrades. A 4-inch Coriolis meter can cost USD 12,000-18,000, compared with USD 2,500-4,000 for an electromagnetic counterpart. Specialized mounting, vibration-isolation, and zeroing steps add another USD 3,000-5,000 to commissioning. Lifecycle economics favor premium meters, but procurement teams often concentrate on upfront budgets. Subscription-based meter-as-a-service offerings are emerging to convert capital expense into operating expense and accelerate adoption.
Other drivers and restraints analyzed in the detailed report include:
- Energy-Sector Safety And Accuracy Compliance Mandates
- Brownfield Demand For Battery-Powered Clamp-On Retrofits
- Cyber-Security Exposure Of Wireless Smart Meters
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Mass-based methods accounted for USD 2.6 billion in 2025 and are advancing at a 7.4% CAGR. The flow meters market benefits as hydrogen blending and carbon-capture sequestration demand direct mass measurement immune to density shifts. Coriolis meters have become the default choice for liquefied CO2 custody transfer, illustrated by the Northern Lights CCS project in Norway, which operates at 100 bar with +-0.05% uncertainty. Ultrasonic designs are displacing turbines in gas distribution because they keep +-1.5% accuracy when hydrogen reaches 20% of volume.
Volumetric technologies still hold 28.9% of 2025 revenue, anchored by electromagnetic meters in municipal water networks. Differential-pressure orifice plates remain common in steam lines, though they require 10-20 diameters of straight pipe. Thermal mass sensors are flourishing in biogas and compressed-air loops, where low flow rates compromise turbine performance. Positive-displacement units persist in fuel-dispensing and viscous-liquid batching. Vortex meters offer a mid-price, low-maintenance option for power-plant steam. Collectively, these trends underscore a structural rotation inside the flow meters industry toward high-accuracy, self-diagnosing devices that integrate seamlessly with digital-twin software.
In-line hardware represented 48.2% of 2025 revenue but is growing at a slower 4.2% pace because brownfield sites face downtime penalties if pipes are cut. Clamp-on variants, by contrast, are expanding at 5.9% and permit installation without depressurization. A North American midstream operator retrofitted 120 lines in eight weeks using clamp-on ultrasonic devices at 62% lower cost than in-line alternatives. Insertion probes, which penetrate but do not replace pipe sections, are finding niches in large-diameter water mains.
Battery innovations extend field life to 10-15 years, letting meters act as wireless IoT nodes. Functional-safety certification for Safety Integrity Level 2 has widened the addressable market to nuclear and pharmaceutical plants. Still, custody-transfer points continue to rely on in-line meters that deliver +-0.1% certainty. The flow meters market now segments by tolerance as much as by mechanics, with end users balancing cost, accuracy and downtime avoidance.
Complete Report Scope:
- By Technology
- Volumetric
- Differential Pressure
- Electromagnetic
- Ultrasonic
- Turbine
- Positive Displacement
- Vortex
- Mass
- Coriolis
- Thermal Mass
- Volumetric
- By Mounting/Installation
- In-Line
- Clamp-On/External
- Insertion
- By Fluid Type
- Liquid
- Gas
- Steam
- By End-User Industry
- Oil and Gas
- Water and Wastewater
- Chemical and Petrochemical
- Power Generation
- Food and Beverage
- Pulp and Paper
- Pharmaceuticals and Biotechnology
- Metals and Mining
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific accounted for 38.9% of 2025 revenue, powered by China's CNY 150 billion smart-water initiative and India's leak-detection mandates. Japan leverages edge-computing analytics in chemical and electronics plants, while South Korea fits thermal mass sensors in expanding semiconductor fabs. Growth also reflects large-scale hydrogen pilot pipelines in Australia and LNG export expansion in Malaysia.
Europe is forecast to lead growth at a 5.3% CAGR. Germany's hydrogen-blend rule moves millions of meters to ultrasonic technology, Denmark's district-heating networks install heat meters to comply with European Union energy-efficiency regulations, and the United Kingdom pursues a 50% leakage-reduction goal that stimulates smart-meter procurement. Additionally, Norway's CCS projects and France's hydrogen stations accelerate demand for custody-transfer Coriolis devices.
North America grows at 4.6% as the United States directs USD 55 billion to water infrastructure and midstream oil operators modernize custody meters. The Middle East invests heavily in desalination, using electromagnetic devices to monitor feedwater and brine. South America's prospects improve after Brazilian utility privatizations unlock smart-meter funding, while Africa shows selective progress with prepaid municipal installations in South Africa and pilot bulk-supply meters in Nigeria. Collectively, these regional programs underpin a broad global baseline for the flow meters market.
- Azbil Corporation
- Badger Meter Inc.
- Bronkhorst High-Tech BV
- Brooks Instrument (ITW)
- Christian Burkert GmbH and Co. KG
- Danfoss A/S
- Dwyer Instruments LLC
- Emerson Electric Co.
- Endress+Hauser AG
- Honeywell International Inc.
- Keyence Corporation
- KROHNE Messtechnik GmbH
- Schneider Electric SE
- Sensirion AG
- Siemens AG
- SICK AG
- TSI Incorporated
- Yokogawa Electric Corporation
- ABB Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 IoT-enabled Process Automation for Real-Time Flow Analytics
- 4.2.2 Global Water and Wastewater Infrastructure Investments
- 4.2.3 Energy-Sector Safety and Accuracy Compliance Mandates
- 4.2.4 Brownfield Demand for Battery-Powered Clamp-On Retrofits
- 4.2.5 Multiphase-Flow Metering Needs in CCUS Projects
- 4.2.6 District Heating/Cooling Smart-Meter Roll-Outs
- 4.3 Market Restraints
- 4.3.1 High CAPEX of Advanced Coriolis and Ultrasonic Meters
- 4.3.2 Skilled-Calibration and Maintenance Talent Shortage
- 4.3.3 Cyber-Security Exposure of Wireless Smart Meters
- 4.3.4 Semiconductor Shortages for Ultrasonic Transducers
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Volumetric
- 5.1.1.1 Differential Pressure
- 5.1.1.2 Electromagnetic
- 5.1.1.3 Ultrasonic
- 5.1.1.4 Turbine
- 5.1.1.5 Positive Displacement
- 5.1.1.6 Vortex
- 5.1.2 Mass
- 5.1.2.1 Coriolis
- 5.1.2.2 Thermal Mass
- 5.1.1 Volumetric
- 5.2 By Mounting/Installation
- 5.2.1 In-Line
- 5.2.2 Clamp-On/External
- 5.2.3 Insertion
- 5.3 By Fluid Type
- 5.3.1 Liquid
- 5.3.2 Gas
- 5.3.3 Steam
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Water and Wastewater
- 5.4.3 Chemical and Petrochemical
- 5.4.4 Power Generation
- 5.4.5 Food and Beverage
- 5.4.6 Pulp and Paper
- 5.4.7 Pharmaceuticals and Biotechnology
- 5.4.8 Metals and Mining
- 5.4.9 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Egypt
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Azbil Corporation
- 6.4.2 Badger Meter Inc.
- 6.4.3 Bronkhorst High-Tech BV
- 6.4.4 Brooks Instrument (ITW)
- 6.4.5 Christian Burkert GmbH and Co. KG
- 6.4.6 Danfoss A/S
- 6.4.7 Dwyer Instruments LLC
- 6.4.8 Emerson Electric Co.
- 6.4.9 Endress+Hauser AG
- 6.4.10 Honeywell International Inc.
- 6.4.11 Keyence Corporation
- 6.4.12 KROHNE Messtechnik GmbH
- 6.4.13 Schneider Electric SE
- 6.4.14 Sensirion AG
- 6.4.15 Siemens AG
- 6.4.16 SICK AG
- 6.4.17 TSI Incorporated
- 6.4.18 Yokogawa Electric Corporation
- 6.4.19 ABB Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment