|
시장보고서
상품코드
2124632
미국의 스쿨버스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States School Bus - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
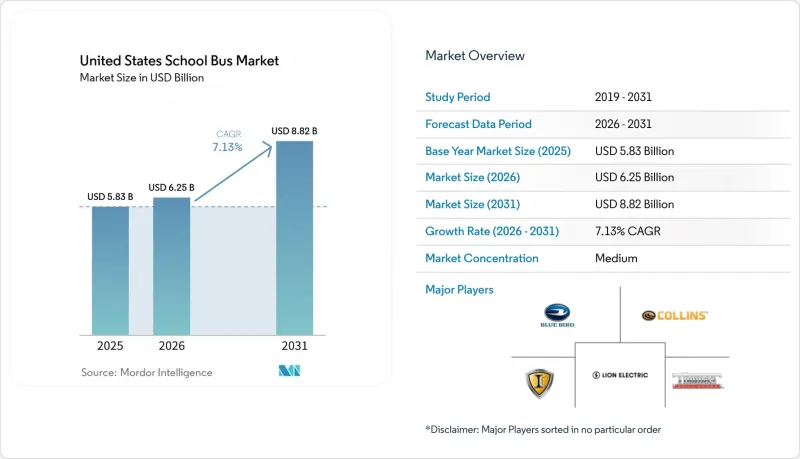
에 의하면, 미국의 스쿨버스 시장 규모는 2025년에 58억 3,000만 달러로 평가되었습니다. 2026년 62억 5,000만 달러에서 2031년까지 88억 2,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 7.13%를 나타낼 전망입니다.
본 보고서는 디자인 유형(유형 A(컷어웨이), 유형 B, 기타), 파워트레인 유형(내연기관, 하이브리드, 전기),소유 형태(학군 소유 차량군, 계약업체 소유 차량군), 좌석 수(30석 미만, 30-60석, 30석 이상)별로 분류되어 있습니다. 시장 예측은 금액(달러) 및 수량(대수)으로 제시되어 있습니다.
미국의 스쿨버스 시장 동향 및 인사이트
EPA의 ‘클린 스쿨버스 프로그램’에 따른 연방 자금의 급증
연방 의회는 차량의 전기화를 가속화하기 위해 5년간(2022-2026 회계연도)에 걸쳐 50억 달러를 배정했습니다. 또한, 2024년 9월에 이루어진 제3차 자금 배분에서는 디젤 차량에서 전기차로 전환함에 따른 가격 차이의 상당 부분을 충당할 수 있는 9억 6,500만 달러의 리베이트가 지급되었습니다. 이 인센티브 제도는 무공해 차량에 크게 치우쳐 있으며, 각 학군은 기존의 10년이라는 교체 주기를 3-5년으로 단축하도록 권장받고 있습니다. 공정성 관련 규정에 따라, 리베이트의 불균형적으로 큰 비중이 특히 지원이 필요한 농촌 지역 및 원주민 커뮤니티에 배분되고 있으며, 이로 인해 제조업체의 고객 기반이 확대되고 있습니다. OEM의 수주 잔고는 현재 24개월 분에 달하며, 이는 2027년 내내 수요의 모멘텀이 지속될 것임을 시사합니다. 또한, 이러한 자금 지원 속도는 금융 파트너에게 장기적인 전망을 제공하며, 미국의 스쿨버스 시장을 뒷받침하는 새로운 ‘Depot-as-a-Service(서비스형 차고)’ 방식의 서비스 제공을 촉진하고 있습니다.
노후화된 국내 차량(11년 이상)이 교체 수요를 견인
2024년까지 미국의 스쿨버스의 상당 부분이 11년을 초과했습니다. 이는 2008년부터 2012년까지의 경기 침체에 따른 지출 연기 결과입니다. 이러한 노후화된 버스의 유지 관리 비용은 점점 더 높아지고 있어, 많은 관계자들이 조기 폐차를 검토하고 있습니다. 녹이 슨 부분의 부식, 디젤 미립자 필터 고장, 차체 피로 등의 문제가 특히 오하이오주, 미시간주, 펜실베이니아주 등에서 긴급 폐차로 이어지고 있습니다. 중고 스쿨버스 시장이 활기를 띠고 있어, 그 재판매 가치를 통해 배터리식 모델로의 전환에 따른 추가 비용의 상당 부분을 상쇄할 가능성이 있습니다. 이러한 수요의 급증은 완충 역할을 하여, 미국의 스쿨버스 시장을 학생 수 변동으로부터 보호하고 있습니다.
농촌 지역의 충전 인프라 부족
많은 비도시 지역 카운티에서는 적정 거리 내에 직류 급속 충전소가 없어, 지방 학군들은 대형 배터리 팩에 투자할 수밖에 없는 실정입니다. 이러한 상황은 버스의 주행 거리를 대폭 단축시킬 수 있는 영하의 겨울 날씨로 인해 더욱 악화되고 있습니다. 게다가 지역 변전소가 공급할 수 있는 전력은 모든 버스를 정비하는 차고에 필요한 전력의 절반도 채 되지 않는 경우가 빈번합니다. 연방 정부의 NEVI 자금은 간선 도로를 중심으로 지원되고 있지만, 차고로의 ‘라스트 마일’ 접근에 대한 자금 지원은 대체로 간과되고 있습니다. 송전망 업그레이드에는 막대한 비용이 소요될 수 있으며, 이는 농촌 지역의 전기화 노력을 저해하고, 특히 도시나 교외 이외의 지역에서 미국의 스쿨버스 시장의 성장 전망을 둔화시키고 있습니다.
부문별 분석
2025년 인도 대수의 79.12%를 차지한 C형 기존 버스는 2031년까지 연평균 성장률(CAGR) 9.02%로 미국 전체 스쿨버스 시장보다 빠른 속도로 성장할 것으로 예측됩니다. 54-84명의 승객 정원, 뛰어난 조종성, 그리고 프론트 엔진 설계는 교외 지역에서 흔히 볼 수 있는 밀도가 제각각인 노선에 적합합니다. C형 섀시는 전기차로 개조하기 쉬우며, 후방 엔진 방식의 D형 모델에 비해 필요한 배터리 팩 용량이 작고, 한랭지에서의 성능도 뛰어납니다.
D형 노선버스는 명목상 시장 점유율을 차지하고 있으며, 노선당 승객 수가 80명을 넘는 고밀도 도시 노선에서 주류를 이루고 있습니다. 그러나 상당한 가격 프리미엄과 차고 공간 제약으로 인해 더 광범위한 보급은 제한되고 있습니다. 30석 미만의 레이아웃을 갖춘 유형 A 컷어웨이형은 지방이나 특별한 요구가 있는 틈새 시장을 충족시키고 있으며, 상당한 연평균 성장률(CAGR)로 확대될 전망입니다. 상용 밴 섀시를 채택하여 연비가 향상되고 유지비도 절감되어, 대체 에너지로의 전환을 추진하는 소규모 학군에게 매력적인 도입 진입점이 되고 있습니다. 따라서 설계의 다양화가 미국의 스쿨버스 시장의 꾸준한 성장 기반이 되고 있습니다.
하이브리드 차량 및 전기자동차는 2031년까지 연평균 성장률(CAGR) 36.45%를 나타낼 것으로 예측되지만, 2025년 시점에서는 내연 기관이 미국의 스쿨버스 시장 점유율의 88.35%를 차지했습니다. 특히 캘리포니아주와 뉴욕주에서는 연방 정부의 보조금과 주 정부의 인센티브가 결합되면서 전기 파워트레인의 가격 격차가 점차 줄어들고 있습니다. 배출 제로 달성 시한이 명확히 정해져 있는 연안 주에서는 전기 버스 도입이 증가하고 있는 반면, 남동부나 그레이트 플레인스 지역에서는 연료 가격이 저렴하고 충전 인프라가 제한적이기 때문에 디젤 차량이 여전히 굳건한 입지를 유지하고 있습니다. 재생 가능 디젤과의 호환성 및 첨단 배기가스 후처리 기술 덕분에 기존 엔진의 수명이 연장되고 있으며, 전력망 구축이 뒤처진 지역에서는 과도기적 전략으로 기능하고 있습니다.
전기 버스 제조업체들은 ‘바이 아메리카(Buy American)’ 크레딧을 획득하기 위해 중서부 지역에 생산을 집중하고 있으며, 배터리 공급업체들도 물류 비용을 최소화하기 위해 해당 지역에 거점을 마련하고 있습니다. 라이온 일렉트릭의 졸리엣 공장은 연간 생산량을 대폭 확대하는 것을 목표로 하고 있으며, 2028년까지 취득 비용을 절감할 가능성이 있는 규모의 경제 효과가 시사되고 있습니다. 이에 대응하여 디젤 차량 제조업체들은 가동 주기에 최적화된 엔진을 도입하여 미세먼지 배출량을 대폭 줄이는 동시에, 수소화 식물성 기름와의 호환성을 실현하고 있습니다. 한편, 각 학군이 제로 배출 기술로 직접 전환함에 따라 하이브리드 차량의 존재감은 점차 희미해지고 있습니다. 이러한 변화는 인센티브 확보를 극대화할 뿐만 아니라 배터리 플랫폼에 대한 투자를 촉진하여 미국의 스쿨버스 시장 전체의 성장세를 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTHAccording to Mordor Intelligence, the United States school bus market size was valued at USD 5.83 billion in 2025 and estimated to grow from USD 6.25 billion in 2026 to reach USD 8.82 billion by 2031, at a CAGR of 7.13% during the forecast period (2026-2031).
This report is Segmented by Design Type (Type A (Cut-Away), Type B, and More), Powertrain Type (Internal Combustion Engine and Hybrid and Electric), Ownership Model (District-Owned Fleets and Contractor-Owned Fleets), and Seating Capacity (Less Than 30 Seats, 30-60 Seats, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
United States School Bus Market Trends and Insights
Federal Funding Surge via EPA Clean School Bus Program
Congress allocated USD 5 billion over five years (FY 2022-2026) to accelerate fleet electrification, and the third funding round in September 2024 awarded USD 965 million in rebates that cover a notable share of the diesel-to-electric price gap . The incentive structure is heavily skewed toward zero-emission vehicles, prompting districts to compress traditional 10-year replacement cycles into 3-to-5-year windows. Equity provisions direct a disproportionate share of rebates to high-need rural and tribal communities, broadening the customer base for manufacturers. OEM order books now stretch up to 24 months, signalling sustained demand momentum through 2027. The funding cadence also gives financing partners long-term visibility, spurring new depot-as-a-service offerings that anchor the United States school bus market.
Aging National Fleet (Above 11 yrs) Pushing Replacement Demand
By 2024, a significant portion of the United States school buses surpassed the 11-year mark, a consequence of deferred spending following the 2008-2012 recession. Maintenance on these aging buses has become increasingly costly, prompting many to consider accelerated scrappage. Issues like rust-belt corrosion, diesel particulate filter failures, and frame fatigue are leading to emergency retirements, especially in states like Ohio, Michigan, and Pennsylvania. A thriving market for used buses has emerged, with resale values potentially offsetting a substantial portion of the added costs for districts transitioning to battery models. This demographic surge provides a buffer, shielding the United States school bus market from fluctuations in enrollment.
Sparse Rural Charging Infrastructure
Rural districts are compelled to invest in oversized battery packs, as many non-metropolitan counties find themselves without a DC fast-charging station within a reasonable distance. The situation is exacerbated by sub-zero winters, which can significantly diminish the bus range. Moreover, local substations frequently provide less than half of the power required for a depot servicing a full fleet of buses. While federal NEVI funds focus on highway corridors, they largely overlook funding for last-mile depot access. Upgrading the grid can involve substantial costs, hindering rural electrification efforts and dampening growth prospects for the United States school bus market, especially in areas beyond urban and suburban locales.
Other drivers and restraints analyzed in the detailed report include:
- Stringent On-board Safety Mandates Accelerating Fleet Renewal
- Low-NOx "Other Fuels" Demand in Non-attainment Counties
- High Upfront Cost of E-Buses Despite Incentives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Type C conventional buses accounted for 79.12% of 2025 deliveries and are projected to expand faster than the wider United States school bus market at a 9.02% CAGR through 2031. Their 54-84 passenger capacity, maneuverability, and front-engine design suit the mixed-density routes common in suburban districts. Electric conversions are easier on Type C frames, requiring smaller battery packs and offering better cold-weather performance than rear-engine Type D models.
Type D transit buses hold a nominal share and dominate dense urban corridors where routes exceed 80 passengers. The steep price premium and depot space limitations constrain broader uptake. Type A cutaways, with under-30-seat layouts, fill rural and special-needs niches and will grow at a notable CAGR. Their commercial van chassis improves fuel economy and lowers maintenance costs, providing an attractive entry point for small districts transitioning to alternative energy. Design diversification, therefore, underpins steady growth within the United States school bus market.
Hybrid and electric units are forecast to grow at a 36.45% CAGR through 2031, although internal-combustion engines retained 88.35% of the United States school bus market share in 2025. The premium price tag on electric powertrains is narrowing as federal rebates stack with state incentives, especially in California and New York. Electric deployments increased in coastal states that have firm zero-emission deadlines, while diesel remains entrenched in the Southeast and Great Plains due to cheaper fuel and limited charging infrastructure. Renewable diesel compatibility and advanced emissions after-treatment are extending the runway for traditional engines, offering a bridge strategy where grid readiness lags.
Electric bus makers are clustering production in the Midwest to capture Buy America credits, and battery suppliers are co-locating to minimize logistics costs. Lion Electric's Joliet plant aims for significant annual output, hinting at potential scale efficiencies that might reduce acquisition costs by 2028. In response, diesel offerings have introduced duty-cycle-optimized engines, achieving a notable reduction in particulate emissions and compatibility with hydrotreated vegetable oil. Meanwhile, hybrids are becoming less relevant as districts leap directly to zero-emission technologies. This shift not only maximizes incentive capture but also channels investments into battery platforms, bolstering the overall momentum of the United States school bus market.
Complete Report Scope:
- By Design Type
- Type A (Cut-away)
- Type B
- Type C (Conventional)
- Type D (Transit-Style)
- By Powertrain Type
- Internal Combustion Engine (IC Engine)
- Hybrid and Electric
- By Ownership Model
- District-Owned Fleets
- Contractor-Owned Fleets
- By Seating Capacity
- Less than 30 Seats
- 30-60 Seats
- Above 60 Seats
List of Companies Covered in this Report:
- Blue Bird Corporation
- Daimler Truck North America LLC (Thomas Built)
- Navistar Inc. (IC Bus)
- Collins Bus Corporation
- Lion Electric Company
- GreenPower Motor Company Inc.
- Micro Bird Inc. (Girardin)
- BYD Motors USA
- Van-Con, Inc.
- Starcraft Bus
- Trans Tech Bus
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Federal Funding Surge via EPA Clean School Bus Program
- 4.2.2 Aging National Fleet (Above 11 yrs) Pushing Replacement Demand
- 4.2.3 Stringent On-board Safety Mandates Accelerating Fleet Renewal
- 4.2.4 Low-NOx "Other Fuels" Demand in Non-attainment Counties
- 4.2.5 Vehicle-to-Grid (V2G) Revenue Potential for School Districts
- 4.2.6 Depot Micro-grid and Solar Pairing Lowers Electric TCO
- 4.3 Market Restraints
- 4.3.1 Sparse Rural Charging Infrastructure
- 4.3.2 High Upfront Cost of E-Buses Despite Incentives
- 4.3.3 Scarcity of High-Voltage Maintenance Technicians
- 4.3.4 Medium-Duty Chassis Supply Bottlenecks
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory & Funding Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Design Type
- 5.1.1 Type A (Cut-away)
- 5.1.2 Type B
- 5.1.3 Type C (Conventional)
- 5.1.4 Type D (Transit-Style)
- 5.2 By Powertrain Type
- 5.2.1 Internal Combustion Engine (IC Engine)
- 5.2.2 Hybrid and Electric
- 5.3 By Ownership Model
- 5.3.1 District-Owned Fleets
- 5.3.2 Contractor-Owned Fleets
- 5.4 By Seating Capacity
- 5.4.1 Less than 30 Seats
- 5.4.2 30-60 Seats
- 5.4.3 Above 60 Seats
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves & Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Blue Bird Corporation
- 6.4.2 Daimler Truck North America LLC (Thomas Built)
- 6.4.3 Navistar Inc. (IC Bus)
- 6.4.4 Collins Bus Corporation
- 6.4.5 Lion Electric Company
- 6.4.6 GreenPower Motor Company Inc.
- 6.4.7 Micro Bird Inc. (Girardin)
- 6.4.8 BYD Motors USA
- 6.4.9 Van-Con, Inc.
- 6.4.10 Starcraft Bus
- 6.4.11 Trans Tech Bus
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment