

|
시장보고서
상품코드
2124650
북미의 농업용 화학제품 포장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Agricultural Chemical Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
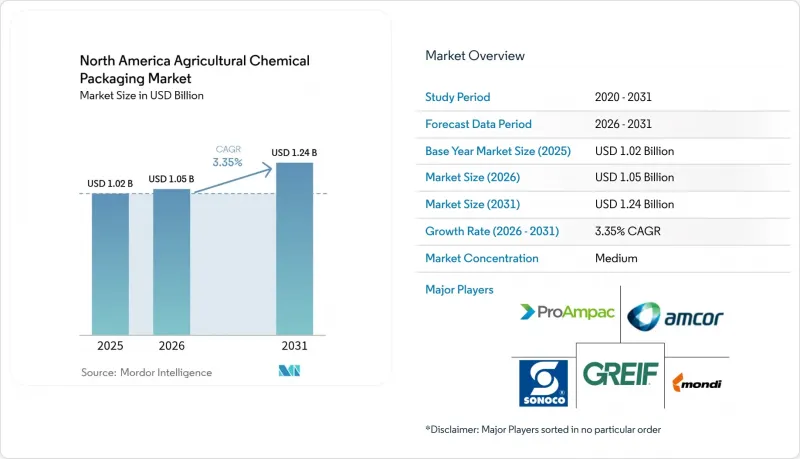
에 의하면, 북미의 농업용 화학제품 포장 시장 규모는 2025년 10억 2,000만 달러로 평가되었습니다. 2026년에는 10억 5,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 3.35%로 성장을 지속하여, 2031년에는 12억 4,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 소재별(플라스틱, 종이 및 판지, 기타), 제품 유형별(봉지·파우치, 용기·캔, 기타),용도별(비료, 농약, 기타), 용량 범위별(20리터 이하, 21-200리터, 200리터 초과), 지역(미국, 캐나다, 멕시코)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
북미의 농업용 화학제품 포장 시장 동향 및 인사이트
서방형 및 수용성 필름의 채택 확대
서방형 포장은 유효 성분의 효능을 연장하고 노동 투입량을 줄여주므로, 북미의 대규모 농장이 요구하는 업무 효율화 수요에 부응하고 있습니다. 수용성 필름은 살포 탱크 내에서 완전히 용해되어 용기 폐기에 따른 번거로움을 해소함으로써 안전성과 밭에서의 생산성을 향상시킵니다. 제초제나 살균제 살포의 경우, 투여 정밀도가 수확량과 규제 준수에 직접적인 영향을 미치기 때문에 이러한 이점을 가장 크게 누리고 있습니다. 농가들이 GPS 유도 시스템이나 가변 살포율 지도에 대응하는 패키지를 선호함에 따라, 정밀 농업용 소프트웨어가 그 보급을 가속화하고 있습니다. 그 결과, 포장은 단순한 수동적 용기에서 농장 관리 워크플로우에 통합된 디지털 통합형 살포 구성 요소로 변화하고 있습니다.
지속가능성을 원동력으로 한 재활용 가능하고 바이오 소재로의 전환
미국 5개 주의 EPR(확대 생산자 책임) 규정에서는 재활용 소재나 재생 가능 소재를 포함한 재료에 대해 환경 친화적인 요금 우대 조치가 마련되어 있으며, 이를 통해 가공업체들은 폴리젖산(PLA), 폴리하이드록시아르카노에이트(PHA) 및 기타 바이오 수지로의 전환을 촉진받고 있습니다. 네브래스카주에 위치한 Citroniq사의 1,200만 달러 규모의 폴리프로필렌 생산 라인 등, 상업 규모의 공장에서공급이 증가함에 따라 비용 프리미엄은 점차 줄어들고 있습니다. 브랜드의 지속가능성에 대한 공약도 하류 부문에 대한 압박을 강화하고 있으며, 탄소 발자국 공개 및 재활용 가능성은 생산자 및 농업 자재 판매업체에게 중요한 구매 기준이 되고 있습니다. 현재 연구 개발(R&D) 분야에서는 기존 수지와 동등한 수분·산소·자외선 차단 성능을 구현하는 데 주력하고 있으며, 이를 통해 안정성에 민감한 제초제나 생물학적 제제가 여러 시즌에 걸친 보관 기간 동안에도 안정적인 상태를 유지할 수 있게 됩니다.
유엔 및 미국 교통부(DOT)의 위험물 규제 강화
드럼통 및 IBC(중간 벌크 용기)에 대한 성능 시험 강화로 인해 제품 라인당 5만-10만 달러의 인증 비용이 증가하고 있으며, 소규모 가공업체로서는 이러한 부담을 감당하기 어려운 상황입니다. 규정을 준수하지 않는 재고의 단계적 폐지는 공급망을 혼란에 빠뜨리고 있으며, 틈새 시장 공급업체들이 확립된 적합성 평가 실험실과 시험 예산을 보유한 기업들에 의한 인수를 요구함으로써 업계 재편을 가속화하고 있습니다.
부문별 분석
플라스틱은 높은 내화학성과 뛰어난 비용 효율성 덕분에 2025년 북미의 농업용 화학제품 포장 시장의 64.65%를 차지했습니다. 이 부문의 연평균 성장률(CAGR)은 완만한 수준을 유지하고 있지만, EPR(확대 생산자 책임) 인센티브와 농장 차원의 지속가능성 노력에 힘입어 바이오 및 복합 소재가 4.35%의 성장률로 이를 상회하고 있습니다. 복합 라미네이트는 기계적 강도와 박막화의 가능성을 모두 갖추고 있어, 내천자성을 저해하지 않으면서 폴리머 사용량을 최대 15%까지 줄일 수 있습니다. 비식품용 바이오매스 유래 바이오베이스 폴리프로필렌은 습기 및 산소 차단 기준을 충족하는 사례가 늘어나고 있어, 고가대의 특수 제초제 및 생물학적 제제 포장재로서의 입지를 확립해 가고 있습니다.
수요의 다양화가 진행되고 있습니다. 비료의 경우 비용 효율을 높이기 위해 견고한 HDPE 재질의 용기가 사용되는 반면, 살아있는 미생물 제품에는 산소 제거 기능을 갖춘 다층 구조가 요구됩니다. 그 결과, 각 컨버터 기업들은 정책 변경이나 고객 구성의 변동에 대비한 헤지 수단으로 소재 포트폴리오의 다양화를 도모하고 있습니다. 북미의 농업용 화학제품 포장 시장에서 바이오 소재가 차지하는 규모는 여전히 틈새 시장 수준이지만, 조달 과정에서 지속가능성 평가 기준이 표준화됨에 따라 조기에 진출한 기업들은 사양 면에서 우위를 점하고 있습니다.
2025년에는 봉지와 파우치가 매출의 43.92%를 차지했습니다. 이는 기존 충전 라인에 대응하고, 평평한 상태로 출하할 수 있으며, 수용성 필름 및 서방형 필름에 대응하기 때문입니다. 그러나 벌크 중개업자들이 운송비와 인건비를 절감하기 위해 취급량을 통합함에 따라, IBC는 2031년까지 연평균 성장률(CAGR) 4.67%로 가장 높은 성장세를 기록하고 있습니다. QR 플레이트와 저전력 센서를 장착한 디지털 대응형 IBC 덕분에 컨테이너는 단순한 정적 보관물에서 유통 네트워크 내의 능동적인 가시화 노드로 변모하고 있습니다.
유연한 중간 벌크 컨테이너(FIBC)와 경질 콤보 토트는 특히 팔레트 적재 시 안정성이 중요한 입상 비료 분야에서 용도가 확대되고 있습니다. 한편, 파우치는 분무 탱크 내에서의 분산성을 향상시키는 계면활성제를 내장한 다층 구조로 진화하고 있습니다. 북미의 농업용 화학제품 포장 시장에서 파우치의 점유율은 정밀한 투여에 있어 그 역할 덕분에 여전히 중요한 위치를 차지하고 있지만, 한편으로 IBC 풀링 프로그램이 가져다주는 서비스 기반의 경제성은 폐기물 감축 크레딧과 비용 예측 가능성을 추구하는 대형 소매업체들의 관심을 끌고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the North America agricultural chemical packaging market size is expected to grow from USD 1.02 billion in 2025 to USD 1.05 billion in 2026 and is forecast to reach USD 1.24 billion by 2031 at 3.35% CAGR over 2026-2031.
This report is Segmented by Material Type (Plastic, Paper and Paperboard, and More), Product Type (Bags and Pouches, Containers and Cans, and More), Application Type (Fertilizers, Pesticides, and More), Capacity Range (<= 20 L, 21 - 200 L, > 200 L), and Geography (United States, Canada, and Mexico). The Market Forecasts are Provided in Terms of Value (USD).
North America Agricultural Chemical Packaging Market Trends and Insights
Growth in Controlled-Release and Water-Soluble Film Adoption
Controlled-release packaging extends active ingredient efficacy and lowers labor inputs, answering the operational efficiency needs of large North American farms. Water-soluble films dissolve entirely in spray tanks and remove container-disposal headaches, improving safety and field productivity. Herbicide and fungicide applications benefit most because dosing precision directly affects yields and regulatory compliance. Precision-farming software accelerates uptake, as farmers favor packs that align with GPS-guided systems and variable-rate maps. As a result, packaging shifts from passive containment to a digitally integrated delivery component embedded in farm management workflows.
Sustainability-Driven Shift to Recyclable and Bio-Based Formats
EPR rules in five U.S. states impose eco-modulated fees that reward materials with recycled or renewable content, nudging converters toward polylactic acid (PLA), polyhydroxyalkanoate (PHA), and other bio-based resins. Cost premiums are narrowing as commercial-scale plants, such as Citroniq's USD 12 million polypropylene line in Nebraska, increase supply. Brand sustainability pledges add downstream pressure, making carbon-footprint disclosure and recyclability critical purchase criteria for growers and input distributors. R&D now focuses on matching the moisture, oxygen, and UV barriers of conventional resins so that sensitive herbicides and biologicals remain stable throughout multi-season storage.
Tightening UN and DOT Hazardous-Goods Regulations
Enhanced performance tests for drums and IBCs raise certification expenses by USD 50,000-100,000 per product line, a burden that smaller converters struggle to absorb. Inventory phase-outs of non-compliant stock disrupt supply chains and accelerate consolidation as niche suppliers seek acquisition by firms with established compliance laboratories and testing budgets.
Other drivers and restraints analyzed in the detailed report include:
- Precision-Farming Demand for Smaller-Dose, High-Barrier Packs
- Bulk-Container Re-usability Programs by Large Distributors
- Volatile Polymer and Metal Feedstock Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastic captured 64.65% of the North America agricultural chemical packaging market in 2025 owing to its high chemical resistance and favorable cost-to-performance ratio. The segment's CAGR remains modest as bio-based and composite substrates outpace at 4.35%, propelled by EPR incentives and farm-level sustainability pledges. Composite laminates marry mechanical strength with downgauging potential, cutting polymer mass by up to 15% without forfeiting puncture resistance. Bio-based polypropylene sourced from non-food biomass increasingly meets moisture and oxygen protection criteria, positioning it for premium-priced specialty herbicide and biological packs.
Demand heterogeneity is widening: fertilizers rely on rugged HDPE jugs for cost efficiency, whereas living microbial products require oxygen-scavenging multilayers. Consequently, converters diversify material portfolios to hedge against policy changes and customer mix volatility. The North America agricultural chemical packaging market size devoted to bio-based formats is still niche, but early movers gain specification lock-ins as sustainability scorecards become standard in procurement.
Bags and pouches delivered 43.92% revenue in 2025 because they fit existing filling lines, ship flat, and support water-soluble or controlled-release films. Yet IBCs register the highest 4.67% CAGR through 2031 as bulk intermediaries consolidate volumes to trim freight and labor. Digital-ready IBCs, fitted with QR plates or low-power sensors, shift containers from static storage to active visibility nodes in distributor networks.
Flexible intermediate bulk containers (FIBCs) and rigid combo totes broaden applications, especially for granular fertilizers where pallet-layer stability matters. Conversely, pouches evolve toward multilayer formats with built-in surfactants that improve spray-tank dispersion. The North America agricultural chemical packaging market share of pouches stays meaningful due to their role in precision dosing, yet the service-based economics of pooled IBC programs attract large retailers seeking waste-reduction credits and cost predictability.
Complete Report Scope:
- By Material Type
- Plastic
- Paper and Paperboard
- Metal
- Composite and Bio-Based Materials
- By Product Type
- Bags and Pouches
- Containers and Cans
- Intermediate Bulk Containers (IBCs)
- Drums
- Other Product Types
- By Application Type
- Fertilizers
- Pesticides
- Herbicides
- Biologicals and Plant Growth Regulators
- By Capacity Range
- <= 20 L
- 21 - 200 L
- > 200 L
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Amcor plc
- Greif Inc.
- Mondi plc
- Sonoco Products Company
- ProAmpac LLC
- LC Packaging International BV
- Mauser Packaging Solutions Holding Co.
- Silgan Holdings Inc.
- NNZ B.V.
- International Paper Company
- Smurfit WestRock
- Sealed Air Corporation
- Uflex Limited
- Constantia Flexibles Group GmbH
- Schutz GmbH & Co. KGaA
- Hoover CS LLC
- FlexPak Services LLC
- Intertape Polymer Group Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in Controlled-Release and Water-Soluble Film Adoption
- 4.2.2 Sustainability-Driven Shift to Recyclable and Bio-Based Formats
- 4.2.3 Precision-Farming Demand for Smaller-Dose, High-Barrier Packs
- 4.2.4 Bulk-Container Re-usability Programs by Large Distributors
- 4.2.5 Digitally Traceable Packaging for Stewardship and Compliance
- 4.2.6 Investments in North-American Resin and Conversion Capacity
- 4.3 Market Restraints
- 4.3.1 Tightening UN/DOT Hazardous-Goods Regulations
- 4.3.2 Volatile Polymer and Metal Feedstock Prices
- 4.3.3 Farmer Push-Back on Packaging Waste Fees
- 4.3.4 Distributor Destocking Cycles Post-2023
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Intensity of Competitive Rivalry
- 4.5.5 Threat of Substitute Products
- 4.6 The Impact of Macroeconomic Factors on the Market
- 4.7 Regulatory Landscape
- 4.8 Technological Outlook
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Plastic
- 5.1.2 Paper and Paperboard
- 5.1.3 Metal
- 5.1.4 Composite and Bio-Based Materials
- 5.2 By Product Type
- 5.2.1 Bags and Pouches
- 5.2.2 Containers and Cans
- 5.2.3 Intermediate Bulk Containers (IBCs)
- 5.2.4 Drums
- 5.2.5 Other Product Types
- 5.3 By Application Type
- 5.3.1 Fertilizers
- 5.3.2 Pesticides
- 5.3.3 Herbicides
- 5.3.4 Biologicals and Plant Growth Regulators
- 5.4 By Capacity Range
- 5.4.1 <= 20 L
- 5.4.2 21 - 200 L
- 5.4.3 > 200 L
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Amcor plc
- 6.4.2 Greif Inc.
- 6.4.3 Mondi plc
- 6.4.4 Sonoco Products Company
- 6.4.5 ProAmpac LLC
- 6.4.6 LC Packaging International BV
- 6.4.7 Mauser Packaging Solutions Holding Co.
- 6.4.8 Silgan Holdings Inc.
- 6.4.9 NNZ B.V.
- 6.4.10 International Paper Company
- 6.4.11 Smurfit WestRock
- 6.4.12 Sealed Air Corporation
- 6.4.13 Uflex Limited
- 6.4.14 Constantia Flexibles Group GmbH
- 6.4.15 Schutz GmbH & Co. KGaA
- 6.4.16 Hoover CS LLC
- 6.4.17 FlexPak Services LLC
- 6.4.18 Intertape Polymer Group Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


