|
시장보고서
상품코드
2124655
페니실린 의약품 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Penicillin Drug - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
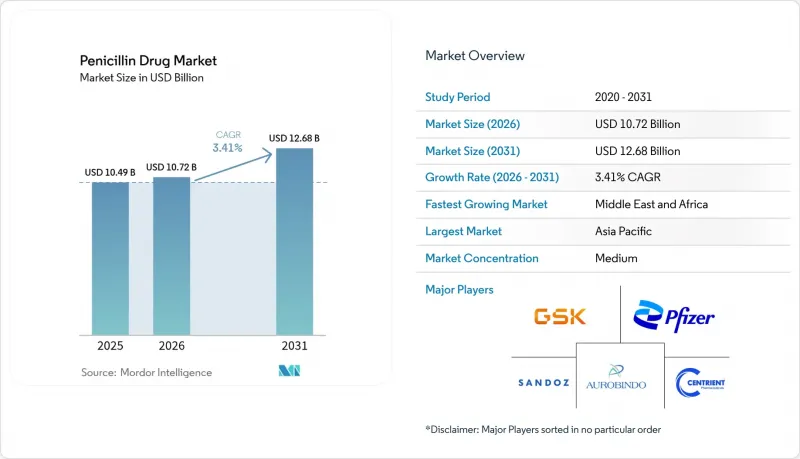
에 의하면, 페니실린 의약품 시장 규모는 2025년 104억 9,000만 달러로 평가되었습니다. 2026년 107억 2,000만 달러에서 2031년까지 126억 8,000만 달러로 확대되고 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 3.41%를 나타낼 전망입니다.
본 보고서는 원료별(천연, 반합성), 제품 유형별(아미노페니실린, 페니실린 분해 효소 내성, 항슈도모나스, β-락타마제 억제제 함유, 광범위 스펙트럼), 투여 경로별(경구, 비경구, 외용),항균 스펙트럼(협역 등), 유통 채널(병원 등), 지역(북미 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 페니실린 의약품 시장 동향 및 인사이트
세균성 감염증 유병률 증가
현재 호흡기 감염증, 요로 감염증, 피부 감염증이 페니실린 처방의 70% 이상을 차지하고 있으며, 델리나 자카르타 등 대도시의 대기 오염 수준 악화에 따라 그 발생률은 상승하고 있습니다. 아목시실린은 합병증이 없는 폐렴에 대한 경험적 치료의 주력으로 계속 사용되고 있지만, OECD 국가들의 인구 고령화에 따라 65세 이상 요로감염(UTI)의 발생률은 3배로 증가했습니다. 인플루엔자 유행기에는 이차적 세균성 폐렴이 계속해서 발생하고 있으며, 2024년부터 2025년 인플루엔자 시즌에는 미국에서 아목시실린-클라불란산염 처방 건수가 18% 급증했습니다. 이러한 추세로 인해, 특히 진단용 미생물 검사가 충분히 이루어지지 않는 지역에서 외래 진료에서 페니실린의 중요성이 확고해지고 있습니다.
신흥 시장에서 합리적인 가격의 제네릭 의약품에 대한 수요 증가
1회 투여당 가격이 0.10-0.50달러 범위인 만큼, 본인 부담금이 총 의료비의 40%를 초과하는 지역에서는 제네릭 페니실린이 필수 의약품 목록의 최상위에 자리 잡고 있습니다. 인도는 2024년에 4만 2,000메트르톤의 페니실린 원료를 수출했는데, 그중 60%는 사하라 이남 아프리카 및 동남아시아로 향했습니다. 브라질에서는 2025년에 37건의 신규 제네릭 의약품 등록이 승인되어, 이는 7년 만에 가장 많은 수치였습니다. 2026년 초, 중국산 아목시실린 캡슐은 1,000단위당 8달러에 거래되어 2023년 대비 3분의 1 하락했으나, 이것이 지방 약국의 판매량을 지탱하고 있습니다.
심화되는 항생제 내성(AMR)
2024년, 유럽연합(EU) 전역의 폐렴구균 페니실린 내성률은 18.3%에 달하고, 2020년 대비 3.6포인트 상승했습니다. 인도의 데이터에 따르면, 현재 지역사회에서 유래한 대장균에 의한 요로감염의 42%가 ESBL 유전자를 보유하고 있어 아목시실린의 사용이 제한되고 있습니다. 미국에서는 페니실린 내성 폐렴구균과 관련된 사망자 수가 연간 3,600명에 달할 전망입니다. 이에 대응하여 약물 적정 사용 프로그램이 도입되어 중환자실에서의 페니실린 경험적 투여가 억제됨에 따라, 수익성이 높은 판매량이 감소하고 있습니다.
부문별 분석
2025년 매출의 64.78%를 반합성 제제가 차지했으며, 5.26%의 연평균 성장률(CAGR)에 힘입어 페니실린 의약품 시장은 천연 유래 제제를 능가하는 성장세를 유지하고 있습니다. 아목시실린과 암피실린을 합치면 처방의 60% 이상을 차지하고 있는 반면, 벤자틴 페니실린 G는 류마티스성 심장 질환의 치료 프로그램을 뒷받침하고 있습니다. 샌드사가 2024년에 6-아미노페니실린산의 생산 능력을 20% 확대할 계획인 것은 지속적인 투자를 뒷받침하고 있습니다.
천연 페니실린은 매독 및 류마티스열 치료에 여전히 필수적이지만, 발효 공정의 제약과 혁신의 지연으로 인해 성장 여지는 제한적입니다. 그럼에도 불구하고, 기부자로부터 자금을 지원받은 예방 투여를 통해 특히 아프리카와 동남아시아에서 안정적인 틈새 시장을 확보하고 있습니다.
2025년 매출에서 아미노페니실린계 항생제가 차지하는 비중은 41.63%였으나, B-락타마제 억제제와 복합제가 5.88%로 가장 높은 성장률을 보였습니다. EMA가 2025년에 고용량 아목시실린-클라불란산염 제제를 승인하면, 복약 순응도가 향상될 전망입니다. 중환자실(ICU)의 슈도모나스균 치료에서는 피페라실린·타조박탐이 여전히 주류를 이루는 반면, 티칼실린·클라불란산염 등의 광범위 항균제는 카르바페넴계 항균제 절약을 위한 치료법에 대한 스튜어드십 수요를 뒷받침하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 34.57%를 차지했습니다. 인도의 MIP(의약품 가격 지수) 및 API(원료의약품)에 관한 인센티브로 인해 생산은 현지 유력 기업으로 이동하고 있습니다. 한편, 중국에서는 처방 지침이 엄격해짐에 따라 페니실린의 경험적 투여량은 감소했으나, 적정 사용 지표는 개선되었습니다. 일본의 초고령화 사회로 인해 요로감염(UTI) 및 폐렴의 발생률은 여전히 높은 수준을 유지하고 있습니다. 호주에서는 약사의 처방 권한이 지역 사회에서의 의약품 사용을 촉진하고 있습니다.
미국에서는 연쇄상구균의 신속 진단으로 인해, 독일에서 제네릭 의약품 가격이 15% 인하되었음에도 불구하고, 협역 스펙트럼 페니실린 V로의 회귀가 진행되고 있습니다. 영국의 ‘Pharmacy First’ 정책으로 인해 항균제 전체 사용량이 감소하는 가운데도 경구용 약물의 성장은 유지되고 있는 반면, 프랑스와 스페인에서는 계몽 캠페인을 통해 페니실린 사용량을 두 자릿수 비율로 줄였습니다.
중동 및 아프리카는 6.36%라는 가장 빠른 성장률을 보이고 있습니다. ‘사우디 비전 2030’은 120곳의 새로운 1차 진료 센터와 20곳의 3차 의료 기관에 자금을 지원하여 항균제의 보급 범위를 확대되고 있습니다. 아랍에미리트(UAE)에서는 원격의료와 연계된 전자 약국이 대면 진료를 필요로 하지 않는 경구용 의약품 조제를 가속화하고 있습니다. 르완다의 예방 투여 계획은 주변 국가들에게 참고할 만한 모델을 제공합니다.
남미에서는 브라질이 제네릭 의약품 승인 절차를 효율화하고, 아르헨티나가 수입 흐름을 정상화함에 따라 시장이 회복세를 보이고 있습니다. 브라질에서는 2025년에 37건의 제네릭 의약품이 등록되었으며, ‘파르마시아 포풀라르’의 적용 범위가 고용량 복합제까지 확대되었습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the penicillin drug market size is projected to expand from USD 10.49 billion in 2025 and USD 10.72 billion in 2026 to USD 12.68 billion by 2031, registering a CAGR of 3.41% between 2026 to 2031.
This report is Segmented by Source (Natural, Semisynthetic), Product Type (Aminopenicillin, Penicillinase-Resistant, Antipseudomonal, B-Lactamase-Inhibitor Combinations, Extended-Spectrum), Route of Administration (Oral, Parenteral, Topical), Spectrum of Activity (Narrow, and More), Distribution Channel (Hospital, and More), and Geography (North America, and More). Market Forecasts are Provided in Value (USD).
Global Penicillin Drug Market Trends and Insights
Growing Prevalence of Bacterial Infections
Respiratory, urinary tract, and skin infections now drive more than 70% of penicillin prescriptions, and their incidence is climbing with urban air-pollution levels in megacities such as Delhi and Jakarta. Amoxicillin remains the empiric mainstay for uncomplicated pneumonia, while aging demographics in OECD countries triple UTI incidence among those older than 65. Influenza seasons continue to spawn secondary bacterial pneumonia; U.S. amoxicillin-clavulanate scripts spiked 18% during the 2024-2025 flu season. These trends cement penicillin relevance in outpatient care, especially where diagnostic microbiology is scarce.
Rising Demand for Affordable Generics in Emerging Markets
Dose-prices between USD 0.10 and 0.50 keep generic penicillins at the top of essential-medicine lists in regions where out-of-pocket payments exceed 40% of total health expenditure. India exported 42,000 metric tons of penicillin APIs in 2024, with 60% destined for sub-Saharan Africa and Southeast Asia. Brazil cleared 37 new generic registrations in 2025, the highest in seven years. Chinese amoxicillin capsules traded at USD 8 per 1,000 units in early 2026, down one-third from 2023, underpinning volumes across rural pharmacy outlets.
Escalating Antimicrobial Resistance (AMR)
Penicillin non-susceptibility in Streptococcus pneumoniae hit 18.3% across the European Union in 2024, up 3.6 percentage points from 2020. Indian data show 42% of community Escherichia coli UTIs now harbor ESBL genes, sidelining amoxicillin. U.S. deaths linked to penicillin-resistant pneumococci total 3,600 annually. Stewardship programs have responded by curbing empiric penicillin use in intensive care units, trimming high-margin volumes.
Other drivers and restraints analyzed in the detailed report include:
- Government Incentives for Domestic API Production
- Pharmacy-First Retail Initiatives Boosting Community Dispensing
- Stringent GMP & Regulatory Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Semisynthetic variants generated 64.78% of 2025 sales, and their 5.26% CAGR keeps the penicillin drug market ahead of natural derivatives. Amoxicillin and ampicillin together cover over 60% of prescriptions, while benzathine penicillin-G sustains rheumatic heart disease programs. Sandoz's 20% capacity expansion for 6-aminopenicillanic acid in 2024 underscores ongoing investment.
Natural penicillin remains critical for syphilis and rheumatic fever, but fermentation limitations and slower innovation limit upside. Nonetheless, donor-funded prophylaxis ensures a stable niche, particularly in Africa and Southeast Asia
Aminopenicillins held 41.63% of 2025 revenue, yet B-lactamase-inhibitor combinations grow fastest at 5.88%. EMA's 2025 approval of a high-dose amoxicillin-clavulanate option should lift adherence. Piperacillin-tazobactam continues to dominate antipseudomonal use in ICUs, while extended-spectrum agents such as ticarcillin-clavulanate leverage stewardship demand for carbapenem-sparing regimens.
Complete Report Scope:
- By Source
- Natural Penicillin
- Semisynthetic Penicillin
- By Product Type
- Aminopenicillin
- Penicillinase-Resistant
- Antipseudomonal
- B-lactamase-Inhibitor Combinations
- Extended-Spectrum
- By Route of Administration
- Oral
- Parenteral
- Topical
- By Spectrum of Activity
- Narrow-Spectrum
- Broad-Spectrum
- Extended-Spectrum
- By Distribution Channel
- Hospital Pharmacies
- Drug & Retail Pharmacies
- Online Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific captured 34.57% of 2025 sales, with India's MIP and API incentives tipping production toward local champions, while China's stricter prescribing guidelines reduced empiric penicillin volume but improved appropriateness metrics. Japan's super-aging demographics keep UTI and pneumonia incidence high. Australian pharmacist prescribing powers bolster community uptake.
Rapid strep diagnostics in the United States drive a pivot back to narrow-spectrum penicillin-V, even as Germany negotiated 15% generic price cuts. The UK's Pharmacy First maintains oral growth despite overall antibiotic decline, while France and Spain trimmed penicillin volumes double digits via awareness campaigns.
The Middle East and Africa show the fastest pace at 6.36%. Saudi Vision 2030 funds 120 new primary-care centers and 20 tertiary hospitals, expanding antibiotic reach. UAE telemedicine-linked e-pharmacies accelerate oral dispensing without in-person visits. Rwanda's prophylaxis blueprint offers a replicable model for neighboring countries.
South America is recovering as Brazil streamlines generic approvals and Argentina normalizes import flows. Brazil's 37 generic registrations in 2025 expand Farmacia Popular coverage to high-dose combinations.
- Abbott Laboratories
- Aurobindo Pharma Ltd.
- Bayer
- Cipla
- CSPC Zhongrun Pharmaceutical
- Dr. Reddy's Laboratories
- GlaxoSmithKline
- Johnson & Johnson
- Lupin
- North China Pharmaceutical Group
- Pfizer
- Sandoz Group
- Sanofi
- Sinopharm Weiqida Pharmaceutical
- Sun Pharmaceuticals Industries
- Takeda Pharmaceuticals
- Teva Pharmaceutical Industries
- The United Laboratories
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Prevalence of Bacterial Infections
- 4.2.2 Rising Demand for Affordable Generics in Emerging Markets
- 4.2.3 Government Incentives for Domestic API Production
- 4.2.4 Pharmacy-First Retail Initiatives Boosting Community Dispensing
- 4.2.5 AI-Enabled Fermentation Cost Efficiencies
- 4.2.6 Penicillin Prophylaxis Programmes for Rheumatic Heart Disease
- 4.3 Market Restraints
- 4.3.1 Escalating Antimicrobial Resistance (AMR)
- 4.3.2 Stringent GMP & Regulatory Compliance Costs
- 4.3.3 Fermentation-Feedstock Supply Volatility
- 4.3.4 Uptake of Novel B-Lactam/BLI Combinations Cannibalising Demand
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Source
- 5.1.1 Natural Penicillin
- 5.1.2 Semisynthetic Penicillin
- 5.2 By Product Type
- 5.2.1 Aminopenicillin
- 5.2.2 Penicillinase-Resistant
- 5.2.3 Antipseudomonal
- 5.2.4 B-lactamase-Inhibitor Combinations
- 5.2.5 Extended-Spectrum
- 5.3 By Route of Administration
- 5.3.1 Oral
- 5.3.2 Parenteral
- 5.3.3 Topical
- 5.4 By Spectrum of Activity
- 5.4.1 Narrow-Spectrum
- 5.4.2 Broad-Spectrum
- 5.4.3 Extended-Spectrum
- 5.5 By Distribution Channel
- 5.5.1 Hospital Pharmacies
- 5.5.2 Drug & Retail Pharmacies
- 5.5.3 Online Pharmacies
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 United Kingdom
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Aurobindo Pharma Ltd.
- 6.3.3 Bayer AG
- 6.3.4 Cipla Ltd.
- 6.3.5 CSPC Zhongrun Pharmaceutical
- 6.3.6 Dr. Reddy's Laboratories
- 6.3.7 GlaxoSmithKline plc
- 6.3.8 Johnson & Johnson (Janssen)
- 6.3.9 Lupin Ltd.
- 6.3.10 North China Pharmaceutical Group
- 6.3.11 Pfizer Inc.
- 6.3.12 Sandoz
- 6.3.13 Sanofi SA
- 6.3.14 Sinopharm Weiqida Pharmaceutical
- 6.3.15 Sun Pharmaceutical Industries
- 6.3.16 Takeda Pharmaceutical Co. Ltd.
- 6.3.17 Teva Pharmaceutical Industries
- 6.3.18 The United Laboratories
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment