

|
시장보고서
상품코드
2124700
북미 및 유럽의 챗봇 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America And Europe Chatbot - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 북미 및 유럽의 챗봇 시장 규모는 2025년에 72억 5,000만 달러로 평가되었고, 2026년 86억 7,000만 달러에서 2031년까지 180억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 15.74%를 나타낼 전망입니다.
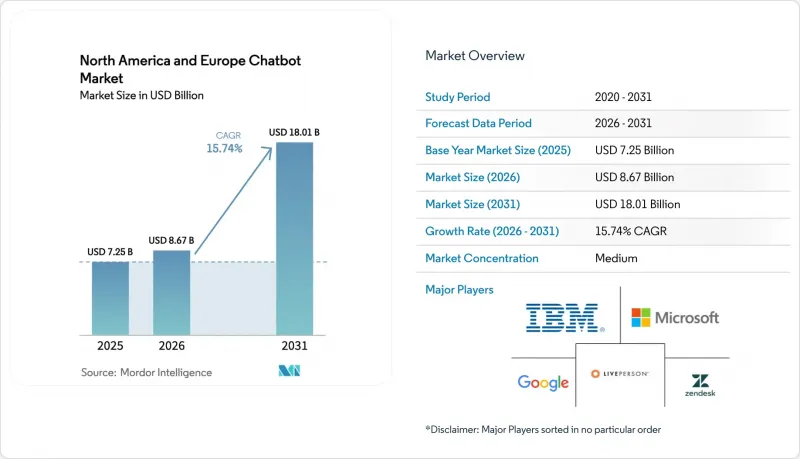
본 보고서는 기업 규모별(대기업, 중소기업), 최종 사용자 업종별(은행, 금융서비스 및 보험(BFSI), 소매, 헬스케어 등), 아키텍처별(규칙 기반/NLU 챗봇 등), 도입 모델별(클라우드 기반, 온프레미스/프라이빗 클라우드), 커뮤니케이션 채널별(웹 및 모바일 앱 등), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미 및 유럽의 챗봇 시장 동향 및 인사이트
검색 확장 생성(RAG)을 통한 CX 개인화
RAG를 통해 챗봇은 자체 지식 기반을 실시간으로 검색할 수 있게 되어, 일반적인 모델의 가중치 부여가 아닌 기업 데이터를 기반으로 한 답변을 제공할 수 있습니다. NVIDIA는 파일럿 프로젝트에서 벡터 데이터베이스를 추가함으로써 사실 오류를 68% 줄일 수 있었음을 보여주었습니다. 마이크로소프트는 2025년 중반, Copilot Studio 내에서 Azure AI Search 인덱스를 사용할 수 있게 했습니다. United Wholesale Mortgage사는 이를 활용하여 인적 검토를 최소화하면서 매월 1만 4,000건의 대출 파일을 처리하고 있습니다. GDPR(EU 개인정보보호규정)에 따라 유럽의 은행들은 온프레미스 RAG 스택으로의 전환을 강요받고 있으며, 하이브리드 클라우드 아키텍처를 제공하는 벤더에 대한 수요가 증가하고 있습니다. 현재는 단순한 유창함보다 정확성과 감사 가능성이 중시되면서, 북미 및 유럽의 챗봇 시장 전반에서 제품 로드맵이 재구성되고 있습니다.
EU 디지털 서비스법 : 연중무휴 24시간 디지털 지원 의무
2024년 2월부터 초대형 온라인 플랫폼에 대해 전면 시행되고 있는 디지털 서비스법(Digital Services Act)은 지속적인 다국어 지원을 의무화하고 있으며, 각 플랫폼 기업은 EU의 24개 공용어를 지원하는 챗봇 도입을 요구받고 있습니다. 독일의 사이버 보안 당국은 자동 지원 시스템에 대해 모든 상호 작용을 기록할 것을 의무화하고 있으며, 컴플라이언스 대시보드를 갖춘 챗봇 제품군이 선호되고 있습니다. EU 사용자에게 서비스를 제공하는 미국 기업들은 전 세계적으로 규정 준수에 부합하는 아키텍처를 채택하고 있으며, 유럽의 기준이 북미 및 유럽의 전체 챗봇 시장으로 확산되고 있습니다.
토큰 기반 API 가격 변동
OpenAI는 2025년 3월에 ChatGPT-4의 API 이용료를 15% 인상한 반면, Anthropic은 단계적 가격 체계로 전환함에 따라 대량 이용자들의 예산 수립에 불확실성이 커지고 있습니다. 한 유럽 통신사는 API 관련 비용이 전년 대비 3배로 급증했다고 밝혔으며, 온프레미스 언어 모델 도입에 대한 재검토가 진행되고 있습니다. 마이크로소프트의 크레딧 기반 요금 체계에서는 쿼리 길이에 따라 소비율이 300%나 변동하기 때문에 기업들은 비용을 절감하기 위해 하이브리드형이나 오픈소스 대안으로 눈을 돌리고 있습니다.
부문 분석
2025년에는 대기업이 매출의 54.81%를 차지한 것으로 평가했으며, 북미 및 유럽의 챗봇 시장에서 CRM과의 긴밀한 통합 및 다국어 지원을 실현하기 위한 충분한 자원을 보유하고 있음이 부각되었습니다. 한편, 중소기업(SME)은 출시 기간을 몇 주에서 몇 시간으로 단축하는 로우코드 빌더의 부양에 힘입어 2031년까지 연평균 성장률(CAGR) 16.06%를 나타낼 것으로 예측됩니다. 마이크로소프트에 따르면, 16만 개의 Copilot Studio 테넌트 중 40%는 직원 수가 250명 미만이며, 이는 IT 팀이 아닌 사업 부서가 현재 대화형 프로젝트를 주도하고 있음을 시사합니다. 이탈리아의 PNRR 보조금과 스페인·포르투갈의 유사한 보조금 덕분에 도입 격차는 더욱 좁혀지고 있으며, 북미 및 유럽의 챗봇 시장에서 중소기업이 우선적인 성장 부문으로서의 입지를 공고히 하고 있습니다.
중소기업은 주문 추적 및 예약 관리를 위해 기성 템플릿을 활용하는 반면, 대기업은 GDPR(EU 개인정보보호규정) 및 HIPAA 요건을 충족하기 위해 온프레미스 또는 하이브리드형 도입을 유지하고 있습니다. 이러한 양극화로 인해 플랫폼 제공업체는 사용 편의성과 엔터프라이즈 수준의 거버넌스 간의 균형을 맞추고, 고객의 성숙도에 따라 진화하는 확장 가능한 가격 체계를 제공해야 합니다.
BFSI(은행 및 금융 및 보험) 부문은 2025년 기준 28.63%의 점유율을 유지했으나, 주요 이용 사례의 상당수가 성숙기에 접어들면서 성장은 정체되는 추세입니다. 대조적으로, 헬스케어 분야는 원격의료의 보험 적용 범위 확대와 관리용 챗봇을 시판 전 승인 대상에서 제외하는 FDA의 지침에 힘입어 15.93%의 연평균 성장률(CAGR)을 나타낼 전망입니다. 2025년 JAMA 연구에 따르면, 챗봇이 알림 및 접수 업무를 담당했을 때 노쇼(no-show)율이 22% 감소한 것으로 밝혀져, 챗봇의 급속한 확산을 뒷받침하는 근거가 되고 있습니다.
의료 기관은 기밀 데이터를 보호하기 위해 온프레미스 도입을 선호하는 반면, 소매 업계에서는 대화형 커머스에 챗봇을 활용하고 있으며, 그 예로 Shopify의 Gemini를 활용한 상품 검색 기능이 전환율을 18% 향상시킨 사례가 있습니다. 부문별 규정 준수 요건과 ROI 요인이 앞으로도 북미 및 유럽 챗봇 시장에서 공급업체의 입지를 좌우할 것으로 보입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the North America and Europe Chatbot Market size was valued at USD 7.25 billion in 2025 and is estimated to grow from USD 8.67 billion in 2026 to reach USD 18.01 billion by 2031, at a CAGR of 15.74% during the forecast period (2026-2031).
This report is Segmented by Enterprise Size (Large Enterprises, and Small and Medium Enterprises), End-User Vertical (BFSI, Retail, Healthcare, and More), Architecture (Rule-based/NLU Chatbots, and More), Deployment Model (Cloud-Based, and On-Premise/Private Cloud), Communication Channel (Web and Mobile Apps, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
North America And Europe Chatbot Market Trends and Insights
CX Personalization Via Retrieval-Augmented Generation (RAG)
RAG lets chatbots query proprietary knowledge bases in real time, grounding answers in enterprise data instead of generic model weights. NVIDIA showed that adding vector databases cut factual errors by 68% in pilot projects. Microsoft enabled Azure AI Search indices inside Copilot Studio in mid-2025, which United Wholesale Mortgage uses to process 14,000 loan files monthly with limited human review. GDPR pushes European banks toward on-premise RAG stacks, boosting demand for vendors that deliver hybrid-cloud architectures. Accuracy and auditability now outrank sheer fluency, reshaping product roadmaps across the North America and Europe chatbot market.
EU Digital Services Act 24/7 Digital-Support Mandate
The Digital Services Act, fully enforceable for very large online platforms since February 2024, obliges continuous multilingual support, prompting platforms to deploy chatbots across 24 official EU languages. Germany's cybersecurity authority required that automated support systems log every interaction, favoring chatbot suites with compliance dashboards. U.S. firms serving EU users are adopting compliant architectures globally, exporting European standards across the North America and Europe chatbot market.
Token-Based API-Pricing Volatility
OpenAI raised ChatGPT-4 API fees by 15% in March 2025, while Anthropic shifted to tiered pricing, raising budgeting uncertainty for high-volume users. A European telecom disclosed tripled API spending year over year, prompting reviews of on-premise language-model deployment. Microsoft's credit-based pricing shows burn rates fluctuating by 300% depending on query length, pushing enterprises toward hybrid or open-source options to cap costs.
Other drivers and restraints analyzed in the detailed report include:
- SaaS Ecosystem Embedding of ChatGPT and Claude APIs
- Contact-Center Labor Shortages Push Automation
- Fragmented Messaging-Platform Policies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Large enterprises contributed 54.81% revenue in 2025, underscoring their resources for deep CRM integration and multilingual support across the North America and Europe chatbot market size. Yet SMEs are forecast to grow 16.06% CAGR through 2031, fueled by low-code builders that cut launch times from weeks to hours. Microsoft noted that 40% of the 160,000 Copilot Studio tenants have fewer than 250 staff, signaling that business units, not IT teams, now champion conversational projects. Italy's PNRR grants and similar subsidies in Spain and Portugal further close the adoption gap, reinforcing SMEs as a priority growth segment within the North America and Europe chatbot market.
SMEs pursue pre-built templates for order tracking and appointment scheduling, while large enterprises retain on-premise and hybrid rollouts to meet GDPR or HIPAA mandates. This bifurcation means platform providers must balance ease of use with enterprise-grade governance, offering scalable pricing tiers that evolve as customers mature.
BFSI retained 28.63% share in 2025, but growth is leveling as most tier-1 use cases mature. Healthcare, in contrast, is predicted to post a 15.93% CAGR, propelled by expanded telehealth reimbursement and FDA guidance that exempts administrative chatbots from pre-market approval. A 2025 JAMA study found no-show rates fell 22% when chatbots handled reminders and intake, fortifying the case for rapid scaling.
Health systems favor on-premise deployments to safeguard sensitive data, whereas retail leverages chatbots for conversational commerce, exemplified by Shopify's Gemini-powered product discovery that boosted conversions 18%. Segment-specific compliance and ROI drivers will continue to dictate vendor positioning across the North America and Europe chatbot market.
Complete Report Scope:
- By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By End-User Vertical
- BFSI
- Retail
- Healthcare
- IT and Telecom
- Travel and Hospitality
- Other End-User Verticals
- By Architecture
- Rule-based/NLU Chatbots
- Generative-AI Chatbots
- Hybrid Architectures
- By Deployment Model
- Cloud-based
- On-Premise/Private Cloud
- By Communication Channel
- Web and Mobile Apps
- Social Media/Messaging Apps
- Voice Assistants and IVR
- In-Product Widgets/SDKs
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- North America
List of Companies Covered in this Report:
- Microsoft Corporation
- IBM Corporation
- Google LLC (Alphabet Inc.)
- LivePerson, Inc.
- Zendesk, Inc.
- Nuance Communications, Inc.
- Drift.com, Inc.
- Intercom, Inc.
- ManyChat, Inc.
- Rasa Technologies, Inc.
- Cognigy GmbH
- Gupshup (Webaroo Inc.)
- Amplify.ai (TruVerse, Inc.)
- CM.com N.V.
- Inbenta Holdings Inc.
- Chatfuel (200 Labs, Inc.)
- Octane AI, Inc.
- Personetics Technologies Ltd.
- Kore.ai, Inc.
- Pypestream, Inc.
- Pandorabots, Inc.
- Ada Support, Inc.
- Genesys Cloud Services Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 CX Personalization via Retrieval-Augmented Generation (RAG)
- 4.2.2 EU Digital Services Act (DSA) 24/7 Digital-Support Mandate
- 4.2.3 SaaS Ecosystem Embedding of ChatGPT and Claude APIs
- 4.2.4 Contact-Center Labor Shortages Push Automation
- 4.2.5 Rise of Low-Code / No-Code Bot Builders
- 4.2.6 5G and Edge-Cloud Roll-outs Enable Real-Time Multimodal Bots
- 4.3 Market Restraints
- 4.3.1 Token-Based API-Pricing Volatility
- 4.3.2 Fragmented Messaging-Platform Policies
- 4.3.3 Edge-Device Privacy Constraints for On-Device Inference
- 4.3.4 Cultural Pushback on Bot-Led Mental-Health and Sensitive Services
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 History and Evolution of Chatbots
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Enterprise Size
- 5.1.1 Large Enterprises
- 5.1.2 Small and Medium Enterprises (SMEs)
- 5.2 By End-User Vertical
- 5.2.1 BFSI
- 5.2.2 Retail
- 5.2.3 Healthcare
- 5.2.4 IT and Telecom
- 5.2.5 Travel and Hospitality
- 5.2.6 Other End-User Verticals
- 5.3 By Architecture
- 5.3.1 Rule-based/NLU Chatbots
- 5.3.2 Generative-AI Chatbots
- 5.3.3 Hybrid Architectures
- 5.4 By Deployment Model
- 5.4.1 Cloud-based
- 5.4.2 On-Premise/Private Cloud
- 5.5 By Communication Channel
- 5.5.1 Web and Mobile Apps
- 5.5.2 Social Media/Messaging Apps
- 5.5.3 Voice Assistants and IVR
- 5.5.4 In-Product Widgets/SDKs
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 Germany
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Rest of Europe
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 IBM Corporation
- 6.4.3 Google LLC (Alphabet Inc.)
- 6.4.4 LivePerson, Inc.
- 6.4.5 Zendesk, Inc.
- 6.4.6 Nuance Communications, Inc.
- 6.4.7 Drift.com, Inc.
- 6.4.8 Intercom, Inc.
- 6.4.9 ManyChat, Inc.
- 6.4.10 Rasa Technologies, Inc.
- 6.4.11 Cognigy GmbH
- 6.4.12 Gupshup (Webaroo Inc.)
- 6.4.13 Amplify.ai (TruVerse, Inc.)
- 6.4.14 CM.com N.V.
- 6.4.15 Inbenta Holdings Inc.
- 6.4.16 Chatfuel (200 Labs, Inc.)
- 6.4.17 Octane AI, Inc.
- 6.4.18 Personetics Technologies Ltd.
- 6.4.19 Kore.ai, Inc.
- 6.4.20 Pypestream, Inc.
- 6.4.21 Pandorabots, Inc.
- 6.4.22 Ada Support, Inc.
- 6.4.23 Genesys Cloud Services Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


