|
시장보고서
상품코드
2124704
동남아시아의 리튬 이온 배터리 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Southeast Asia Lithium-ion Battery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
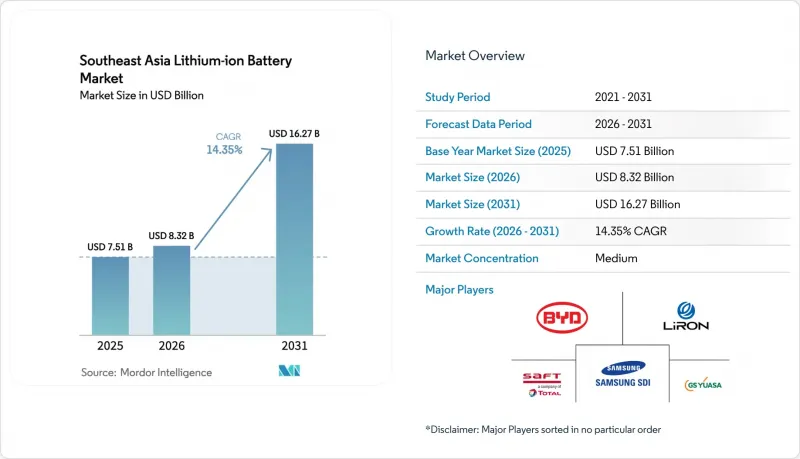
에 의하면, 동남아시아의 리튬 이온 배터리 시장 규모는 2025년 75억 1,000만 달러로 평가되었습니다. 2026년에는 83억 2,000만 달러로 확대되어 2031년까지 162억 7,000만 달러에 이를 것으로 예상되고 2026년부터 2031년에 걸쳐 CAGR 14.35%로 성장할 전망입니다.
본 보고서는 제품 유형(LCO, LFP, NMC, NCA, LMO, LTO), 형태(원통형, 각형, 파우치형),용량(3,000 mAh 미만, 3,000-1만 mAh, 1만-6만 mAh, 6만 mAh 초과), 최종 이용 산업(자동차, 소비자 가전, 산업용·전동 공구, 기타),및 지역(인도네시아, 말레이시아, 필리핀, 베트남, 기타)별로 분류되어 있습니다.
동남아시아의 리튬 이온 배터리 시장 동향 및 인사이트
전기차(EV)의 급속한 보급을 뒷받침하는 인센티브
인도네시아의 부가가치세(VAT) 인하,베트남의 등록비 환급, 그리고 태국의 전기차 대상 3.5 현금 보조금 덕분에 2025년에는 내연기관 차량과의 총 소유 비용(TCO) 격차가 최대 25퍼센트 포인트 축소되어, 이륜차 및 소형차 분야의 신차 출시가 활발해졌습니다. 자동차 제조업체들은 현재 인센티브를 활용하기 위해 배터리 셀의 현지 조달을 추진하고 있으며, 이로 인해 기가팩토리의 가동률이 가속화되고, 보조금 상한선이 설정된 차종 등급에서 비용 경쟁력이 있는 LFP(인산철리튬) 배터리의 입지가 확고해지고 있습니다. 자카르타와 방콕에서 라스트 마일 배송용 교체형 배터리 차량의 도입이 확대됨에 따라, 3,000-1만 mAh의 표준화된 배터리 팩에 대한 수요가 급증하고 있습니다. 2년마다 현지 조달 비율 기준을 상향 조정하는 규정 준수 조항은 수직 통합을 촉진하는 한편, 외국 OEM 제조업체를 정책 변경의 위험에 노출시키고 있습니다. 그 결과, 2028년까지 동남아시아의 리튬 이온 배터리 시장의 성장 궤도는 지속적으로 상승할 전망입니다.
확대되는 가전제품 제조
삼성 및 애플공급업체들이 중국에서 생산 라인을 이전함에 따라, 2025년에는 베트남의 스마트폰 및 노트북 전 세계 조립 점유율이 31%로 상승했고, 원통형 및 각형 셀에 대한 수요가 박닌 및 박짱 주변에 집중되었습니다. 인접한 셀 공장으로 인해 물류 리드타임이 1주일 미만으로 단축되고 운전 자금이 절감되는 동시에, 3,000-5,000 mAh의 LCO 및 NMC 셀에 대한 재주문이 확보되고 있습니다. 태국의 데이터센터용 하드웨어 생산 라인에서는 UPS 모듈용 고사이클 수명 LTO 셀에 대한 틈새 수요가 발생하고 있습니다. 한편, IEC 62133 시험 준수로 인해 신규 SKU 출시가 최대 6주 지연되고 있습니다. 노동 시장 경색으로 인해 기술자 임금은 상승하고 있으나, 전극 코팅 공정에 자동화를 도입함으로써 그 영향은 상쇄되고 있습니다.
수입 원자재에 대한 의존
이 지역에서는 리튬 화학 물질의 95% 이상, 합성 흑연의 87%를 해외에서 조달하고 있어, 셀 제조업체는 상품 가격의 급격한 변동에 노출되어 있습니다. 2025년에는 탄산리튬 가격이 톤당 1만 2,500-1만 8,700달러 범위에서 형성되어 이익률을 압박했습니다. 중국의 흑연 수출 허가 제도로 인해 승인 기간이 2주에서 8주로 연장되면서 말레이시아의 양극재 생산 확대가 지연되었습니다. 글렌코어(Glencore)의 무탄다(Mutanda) 광산에서 불가항력 선언에 따른 코발트 가격 급등으로 인해, 베트남 생산자들은 90일 분의 재고를 확보할 수밖에 없게 되었고, 유동성이 동결되었습니다. 수산화 코발트 및 분리막 시범 사업은 진행 중이지만, 실질적인 대체재가 실현되기까지는 아직 수년이 소요될 것으로 예상되므로, 동남아시아의 리튬 이온 배터리 시장은 계속해서 업스트림 부문의 충격에 노출된 상태입니다.
부문별 분석
2025년에도 리튬·니켈·망간·코발트(NMC) 계열 배터리가 매출의 61.3%를 차지했으나, 자동차 제조업체들이 보조금 상한선을 충족하는 코발트 프리 배터리 팩으로 전환함에 따라,동남아시아의 리튬 이온 배터리 시장에서 인산철리튬(LFP) 시장 규모는 연평균 성장률(CAGR) 38.5%로 3배 확대될 것으로 예측됩니다. BYD가 VinFast 및 Banpu NEXT에 Blade 기술을 라이선스함에 따라 모듈 수가 감소하고 팩 무게가 10% 경감되어, 차량 1대당 배터리 비용은 kWh당 90달러 미만으로 떨어졌습니다. 2026년부터 인도네시아에서 생산될 CATL의 M3P 변형 제품은 코발트 관련 위험 없이 표준 LFP에 비해 에너지 밀도를 15% 향상시켰습니다.
코발트가 포함되지 않은 화학 조성은 인도네시아의 황산니켈 수출 관세가 국내 양극재 생산을 촉진하고 있다는 점과,태국이 망간을 풍부하게 함유한 배합을 선호하는 점을 배경으로, 시장 점유율이 2025년 28.7%에서 2031년까지 46.3%로 상승할 전망입니다. NCA는 8.2%의 점유율에 그치며, 테슬라 수입차에 사용되는 파나소닉 제조의 원통형 셀로 한정되어 있지만, LTO는 1만 사이클의 내구성이 요구되는 선박용 및 UPS(무정전 전원 장치) 부문에서 점유율을 확대되고 있습니다. 경쟁의 초점은 양극 전구체의 조달과 셀에서 팩으로의 통합 효율에 있습니다.
2025년에는 중국의 전기차 제조업체들이 스케이트보드형 섀시에 적층이 가능한 원통형 셀을 선호함에 따라 각형 셀이 매출의 46.5%를 차지하며 1위를 차지했으나, 파우치형 셀은 팩의 무게를 12% 경량화하고주행 거리를 연장하는 현대자동차와 LG의 카라완 생산 라인의 뒷받침으로 연평균 21.1%의 성장률을 기록하고 있습니다. 동남아시아의 고급 세단용 리튬 이온 배터리 시장에서 파우치형 셀의 점유율은 세라믹 코팅된 라미네이트가 열대 기후의 더위로 인한 팽창을 억제하기 때문에 2031년까지 35%를 넘어설 가능성이 있습니다.
원통형은 32.8%의 점유율을 유지하고 있으며, 전동 공구 및 고성능 소비자용 전자기기 분야에서 주도적인 위치를 차지하고 있습니다. 이러한 분야에서는 자동 권선 기술을 통해 저비용과 높은 사이클 수명이 실현되고 있습니다. 각형 셀은 유틸리티 규모의 에너지 저장 분야에서 계속해서 주도적인 위치를 유지하고 있습니다. 말레이시아의 400 MWh 시범 프로젝트에 도입된 CATL의 280 Ah 캔형 배터리는 90%의 효율로 6,000회의 충방전을 견딥니다. 인건비 균형 덕분에 태국 및 베트남 공장에서는 원통형 셀 가격 대비 5% 이내의 가격대로 파우치형 및 각형 셀을 양산할 수 있게 되었습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the Southeast Asia lithium-ion battery market size is expected to increase from USD 7.51 billion in 2025 to USD 8.32 billion in 2026 and reach USD 16.27 billion by 2031, growing at a CAGR of 14.35% over 2026-2031.
This report is Segmented by Product Type (LCO, LFP, NMC, NCA, LMO, and LTO), Form Factor (Cylindrical, Prismatic, and Pouch), Power Capacity (Up To 3, 000 MAh, 3, 000 To 10, 000 MAh, 10, 000 To 60, 000 MAh, and Above 60, 000 MAh), End-Use Industry (Automotive, Consumer Electronics, Industrial, Stationary Storage, and More), and Geography (Indonesia, Malaysia, Philippines, Vietnam, and More).
Southeast Asia Lithium-ion Battery Market Trends and Insights
Rapid EV-Adoption Incentives
VAT cuts in Indonesia, registration-fee rebates in Vietnam, and Thailand's EV 3.5 cash subsidies narrowed the total-cost-of-ownership gap against internal-combustion vehicles by up to 25 percentage points in 2025, lifting model launches across two-wheelers and compact cars. Automakers now localize cell sourcing to unlock incentives, accelerating gigafactory utilization and cementing cost-competitive LFP chemistry in subsidy-capped vehicle classes. Swappable-battery fleets for last-mile delivery in Jakarta and Bangkok multiply demand for standardized 3,000-to-10,000 mAh packs. Compliance clauses that ratchet local-content thresholds every two years encourage vertical integration but expose foreign OEMs to policy shifts. The net effect is a sustained uplift in the Southeast Asia lithium-ion battery market trajectory through 2028.
Expanding Consumer-Electronics Manufacturing
Vietnam's share of global smartphone and notebook assembly climbed to 31% in 2025 as Samsung and Apple suppliers relocated lines from China, clustering cylindrical- and prismatic-cell demand around Bac Ninh and Bac Giang. Adjacent cell plants shorten logistics lead times to under one week, lowering working capital and locking in repeat orders for 3,000-to-5,000 mAh LCO and NMC cells. Thailand's data-center hardware lines add niche demand for high-cycle-life LTO cells in UPS modules, while compliance with IEC 62133 testing slows new SKUs by up to six weeks. Tightening labor markets raise technician wages but are offset by automation upgrades in electrode coating.
Imported Raw-Material Dependence
The region sources more than 95% of lithium chemicals and 87% of synthetic graphite from abroad, exposing cell makers to volatile commodity swings that eroded margins in 2025 when lithium carbonate ranged between USD 12,500 and USD 18,700/t. China's export-licensing on graphite stretched approval cycles from two to eight weeks, delaying Malaysian cathode ramps. Cobalt price spikes following Glencore's Mutanda force-majeure forced Vietnamese producers to hold 90-day inventories, freezing liquidity. While pilot hydroxide and separator ventures are underway, meaningful substitution is still several years out, keeping the Southeast Asia lithium-ion battery market exposed to upstream shocks.
Other drivers and restraints analyzed in the detailed report include:
- Government-Backed Gigafactory Investments
- Declining Battery-Pack Costs
- Safety Recalls & Thermal-Runaway Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Lithium Nickel Manganese Cobalt retained 61.3% revenue in 2025, yet the Southeast Asia lithium-ion battery market size for Lithium Iron Phosphate is projected to triple at a 38.5% CAGR as automakers shift to cobalt-free packs that meet subsidy caps. BYD's Blade licensing to VinFast and Banpu NEXT cut module count and trimmed pack weight by 10%, shrinking per-vehicle battery cost below USD 90 per kWh. CATL's M3P variant, produced in Indonesia from 2026, adds 15% energy density versus baseline LFP without introducing cobalt risk.
Cobalt-free chemistries collectively rise from 28.7% share in 2025 to 46.3% by 2031, propelled by Indonesia's export levies on nickel sulfate that encourage in-country cathode production and Thailand's preference for manganese-rich formulations. NCA remains niche at 8.2% share, reserved for Panasonic cylindrical cells used in Tesla imports, while LTO captures marine and UPS segments requiring 10,000-cycle durability. Competitive pressure revolves around cathode precursor sourcing and cell-to-pack integration efficiencies.
Prismatic units led with 46.5% revenue in 2025 as Chinese EVs favored stackable cans for skateboard chassis, but pouch cells are growing 21.1% annually, spurred by Hyundai-LG's Karawang line that delivers 12% lighter packs and extra driving range. The Southeast Asia lithium-ion battery market share for pouch architecture in premium sedans could top 35% by 2031 as ceramic-coated laminate reduces swelling in tropical heat.
Cylindrical formats maintain a 32.8% share, dominating power-tool and high-performance consumer devices, where automated winding yields low cost and high cycle life. Prismatic designs continue leading in utility-scale storage; CATL's 280 Ah cans deployed in Malaysia's 400 MWh pilot deliver 6,000 cycles at 90% efficiency. Labor-cost parity enables Thai and Vietnamese plants to mass-produce pouch and prismatic cells within 5% of cylindrical price points.
Complete Report Scope:
- By Product Type
- Lithium Cobalt Oxide (LCO)
- Lithium Iron Phosphate (LFP)
- Lithium Nickel Manganese Cobalt (NMC)
- Lithium Nickel Cobalt Aluminium (NCA)
- Lithium Manganese Oxide (LMO)
- Lithium Titanate (LTO)
- By Form Factor
- Cylindrical
- Prismatic
- Pouch
- By Power Capacity
- Up to 3,000 mAh
- 3,000 to 10,000 mAh
- 10,000 to 60,000 mAh
- Above 60,000 mAh
- By End-use Industry
- Automotive (EV, HEV, PHEV)
- Consumer Electronics
- Industrial and Power Tools
- Stationary Energy Storage
- Aerospace and Defense
- Marine
- By Geography
- Indonesia
- Malaysia
- Philippines
- Singapore
- Thailand
- Vietnam
- Rest of Southeast Asia
List of Companies Covered in this Report:
- Contemporary Amperex Technology Co. Ltd. (CATL)
- LG Energy Solution Ltd.
- BYD Co. Ltd.
- Samsung SDI Co., Ltd.
- Panasonic Holdings Corp.
- SK On Co., Ltd.
- EVE Energy Co., Ltd.
- Saft Groupe SA
- GS Yuasa Corp.
- Murata Manufacturing Co., Ltd.
- Tesla, Inc.
- Envision AESC Group Ltd.
- Varta AG
- A123 Systems LLC
- Narada Power Source Co., Ltd.
- Sunwoda Electronic Co., Ltd.
- Dynapack Asia Pte Ltd
- LiRON LIB Power Pte Ltd
- CSB Energy Technology Co., Ltd.
- Northvolt AB
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid EV-adoption incentives
- 4.2.2 Expanding consumer-electronics manufacturing
- 4.2.3 Government-backed gigafactory investments
- 4.2.4 Declining battery-pack costs
- 4.2.5 Indonesia nickel-laterite HPAL upsurge
- 4.2.6 Maritime electrification of archipelagos
- 4.3 Market Restraints
- 4.3.1 Imported raw-material dependence
- 4.3.2 Safety recalls & thermal-runaway concerns
- 4.3.3 Grid-instability limiting ESS uptake
- 4.3.4 Restrictive local-content rules
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Lithium Cobalt Oxide (LCO)
- 5.1.2 Lithium Iron Phosphate (LFP)
- 5.1.3 Lithium Nickel Manganese Cobalt (NMC)
- 5.1.4 Lithium Nickel Cobalt Aluminium (NCA)
- 5.1.5 Lithium Manganese Oxide (LMO)
- 5.1.6 Lithium Titanate (LTO)
- 5.2 By Form Factor
- 5.2.1 Cylindrical
- 5.2.2 Prismatic
- 5.2.3 Pouch
- 5.3 By Power Capacity
- 5.3.1 Up to 3,000 mAh
- 5.3.2 3,000 to 10,000 mAh
- 5.3.3 10,000 to 60,000 mAh
- 5.3.4 Above 60,000 mAh
- 5.4 By End-use Industry
- 5.4.1 Automotive (EV, HEV, PHEV)
- 5.4.2 Consumer Electronics
- 5.4.3 Industrial and Power Tools
- 5.4.4 Stationary Energy Storage
- 5.4.5 Aerospace and Defense
- 5.4.6 Marine
- 5.5 By Geography
- 5.5.1 Indonesia
- 5.5.2 Malaysia
- 5.5.3 Philippines
- 5.5.4 Singapore
- 5.5.5 Thailand
- 5.5.6 Vietnam
- 5.5.7 Rest of Southeast Asia
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Contemporary Amperex Technology Co. Ltd. (CATL)
- 6.4.2 LG Energy Solution Ltd.
- 6.4.3 BYD Co. Ltd.
- 6.4.4 Samsung SDI Co., Ltd.
- 6.4.5 Panasonic Holdings Corp.
- 6.4.6 SK On Co., Ltd.
- 6.4.7 EVE Energy Co., Ltd.
- 6.4.8 Saft Groupe SA
- 6.4.9 GS Yuasa Corp.
- 6.4.10 Murata Manufacturing Co., Ltd.
- 6.4.11 Tesla, Inc.
- 6.4.12 Envision AESC Group Ltd.
- 6.4.13 Varta AG
- 6.4.14 A123 Systems LLC
- 6.4.15 Narada Power Source Co., Ltd.
- 6.4.16 Sunwoda Electronic Co., Ltd.
- 6.4.17 Dynapack Asia Pte Ltd
- 6.4.18 LiRON LIB Power Pte Ltd
- 6.4.19 CSB Energy Technology Co., Ltd.
- 6.4.20 Northvolt AB
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment