

|
시장보고서
상품코드
2124720
벤젠, 톨루엔 및 크실렌(BTX) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Benzene-Toluene-Xylene (BTX) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
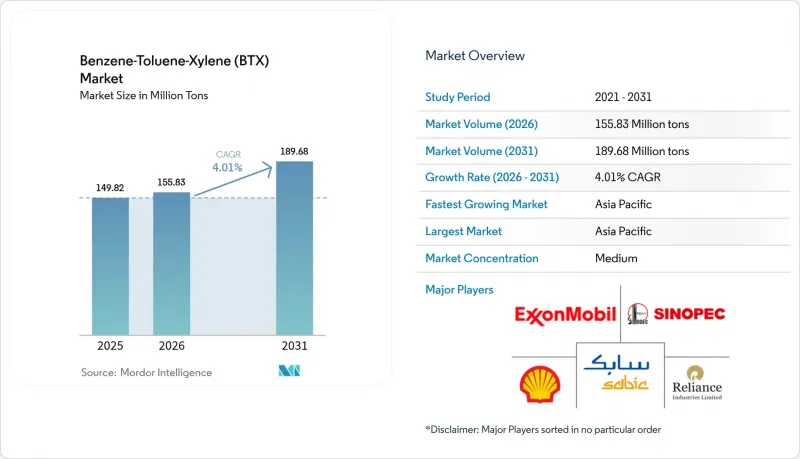
에 의하면, 벤젠, 톨루엔 및 크실렌(BTX) 시장 규모는 2025년에 1억 4,982만 톤으로 평가되었고, 2026년에 1억 5,583만 톤으로 추정되고, 2031년까지 1억 8,968만 톤에 이를 것으로 예측되며, 2026-2031년 CAGR 4.01%로 성장할 전망입니다.
본 보고서는 유형별(벤젠, 톨루엔, 크실렌), 용도별(벤젠(에틸벤젠, 시클로헥산, 알킬벤젠, 쿠멘,니트로벤젠, 기타), 톨루엔별(페인트 및 코팅, 접착제·잉크, 폭발물, 화학 중간체), 크실렌별(용제, 모노머, 기타)), 지역별(아시아태평양, 북미, 유럽, 기타)로 분석합니다. 시장 예측은 수량(톤) 기준입니다.
세계의 벤젠, 톨루엔 및 크실렌(BTX) 시장 동향 및 인사이트
신규 방향족 화합물 복합 시설에 대한 투자 붐이 지역 공급 구조를 재편
2024-2027년 중국, 인도, 사우디아라비아, 말레이시아에서는 신규(그린필드) 및 기존(브라운필드) 방향족 화합물 프로젝트가 잇달아 발표될 전망입니다. 2024년 3월에는 그레이에서 대규모 생산 능력을 자랑하는 파라크실렌 제조 설비가 가동을 시작했습니다. 한편, 펭겔란 시설은 완공을 앞두고 있으며, 2026년 중반에 가동을 시작할 것으로 예측됩니다. 2024년 하반기에는 한 프로젝트가 톨루엔의 수소 탈알킬화 루프를 활용하여 벤젠을 생산함으로써 생산 능력을 확대했습니다. 이러한 사업들은 전반적으로 BTX 공급에 기여하며, 아시아태평양의 생산 우위를 더욱 공고히 하고 있습니다. ISO 9001 및 ISO 14001 준수를 의무화함으로써, 이 프로젝트들은 건설 품질, 배기가스 모니터링 및 근로자 안전을 중시하고 있습니다. 이러한 노력으로 인해 초기 자본 집약도는 높아지지만, 프로젝트 전체 기간에 걸친 운영 위험은 경감됩니다.
PET 수요의 급증으로 인해 파라크실렌의 수급 균형은 여전히 타이트한 상태를 유지하고 있습니다.
1인당 PET 보급률이 북미에 비해 뒤처져 있는 인도, 인도네시아, 베트남에서는 주로 식수 병용으로 폴리에틸렌 테레프탈레이트(PET) 수지 수요가 급증하고 있습니다. 크실렌 수요의 대부분을 차지하는 파라크실렌은 정제 테레프탈산(PTA) 제조에 이 원료가 필요하기 때문에 수요가 높습니다. 저장성에 거점을 둔 룽성 석유화학은 연간 생산 능력이 큰 파라크실렌 시설을 운영하고 있으며, 가동률이 높은 수준에 있어 예상치 못한 수요 급증에 대응할 여지가 거의 없습니다. 오르토크실렌과 메타크실렌을 합친 소비량은 크실렌 전체에서 비교적 작은 비중을 차지할 뿐이지만, 그 성장세는 둔화되고 있습니다. 이는 주로 프탈산 무수물이 가소제의 대체품과의 경쟁에서 고전하고 있기 때문입니다. 2026년 1월, 파라크실렌의 혼합 크실렌 대비 프리미엄은 2021년 이후 최고 수준에 도달했습니다. 이러한 가격 급등으로 인해 정제업체들은 톨루엔의 불균형 루프를 조정할 수밖에 없게 되었고, 그 결과 오르토크실렌 및 벤젠 생산량이 희생되는 상충 현상이 발생하고 있습니다. 하류 폴리머용 촉매를 보호하기 위해서는 ASTM D5453 규격을 준수하고, 황 함량을 1 ppm 미만으로 유지하는 것이 필수적입니다.
발암성에 기반한 노출 제한이 규정 준수 비용을 상승시키고 있습니다.
미국 직업안전보건청(OSHA)은 벤젠에 대한 엄격한 노출 한도를 시행하고 있습니다. 구체적으로는 시간 가중 평균 1 ppm, 단기 상한치 5 ppm이 정해져 있습니다. 이러한 조치는 벤젠 과다 노출과 급성 골수성 백혈병 간의 연관성에 대응하기 위한 것입니다. 사업자는 현재 밀폐형 로딩 암, 증기 회수 시스템 및 실시간 대기 모니터링 장비에 대한 투자를 의무화하고 있습니다. 또한, 설정된 임계치를 초과하는 노출 기록이 있는 직원에 대해서는 연례 혈액 검사 비용을 부담해야 합니다. 세계보건기구(WHO) 및 관련 EU 지침은 전 세계적으로 이러한 엄격한 기준치의 적용을 권장하고 있습니다. 1980년대 중반에 건설된 방향족 화합물 추출 라인을 현대의 환기 및 모니터링 기준에 부합하도록 개조하는 데는 막대한 투자가 필요합니다. 또한, 직원 100명 규모의 공장의 경우, 지속적인 모니터링 및 개인보호구(PPE)(PPE)에 드는 비용은 상당한 금액에 달할 전망입니다. 2025년, 쉘(Shell)은 노후화된 풀라우 부콤(Pulau Bukom)의 벤젠 생산 설비에 대한 개보수 비용이 경제적으로 타당하지 않다고 판단하여 폐쇄했습니다. 마찬가지로, SABIC도 같은 이유로 헬렌(Geleen)의 가동을 중단했습니다.
부문별 분석
2025년, 벤젠은 총 생산량의 38.33%를 차지했으며, 에틸벤젠에서 스티렌, 시클로헥산에서 나일론, 쿠멘에서 비스페놀 A에 이르는 일련의 생산 체인을 뒷받침했습니다. 특히 에틸벤젠은 2025년 벤젠 생산량에서 큰 비중을 차지했습니다. 벤젠, 톨루엔 및 크실렌(BTX) 부문에서 벤젠 유도체 시장은 2031년까지 꾸준히 성장할 것으로 예측됩니다. 세제 및 폴리우레탄에 대한 수요로 인해 쿠멘, 니트로벤젠, 알킬벤젠 시장 점유율을 더욱 확대되고 있습니다. 벤젠 사용량의 상당 부분을 차지하는 시클로헥산은 자동차 엔진룸 내부 부품에 나일론 6 섬유의 채택이 확대됨에 따라 성장을 보이고 있습니다.
톨루엔은 현재 점유율은 작지만, 연평균 성장률(CAGR) 4.48%를 기록하며 벤젠, 톨루엔 및 크실렌(BTX) 시장에서 가장 빠르게 성장하는 방향족 화합물입니다. 현재 톨루엔의 상당 부분이 불균화 반응 및 트랜스알킬화 플랜트에 투입되어 벤젠과 파라크실렌이 생산되고 있으며, 이는 지난 몇 년에 비해 현저히 증가한 수치입니다. 도료, 잉크, 접착제와 같은 기존 분야는 한때 톨루엔 소비량의 대부분을 차지했으나, VOC 규제로 인해 그 비율은 감소하고 있습니다. 반면, 폭발물 및 니트로화 화학 물질과 같은 틈새 시장은 계속해서 호황을 누리고 있습니다. ASTM 순도 기준을 준수함으로써 금속 및 황 불순물이 촉매의 허용 범위 내에 포함되도록 보장되며, 그 결과 다운스트림 공정의 효율이 향상됩니다.
지역별 분석
아시아태평양은 2025년 총량의 62.41%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 4.22%를 나타낼 것으로 예측됩니다. 중국은 파라크실렌 생산이 거의 풀가동되고 있는 것을 배경으로, 이 지역 수요 대부분을 차지하고 있습니다. 한편, 인도에서는 2024-2026년 방향족 화합물의 생산 능력이 추가됨에 따라 이 수요가 더욱 증가할 전망입니다. 일본과 한국에서는 일부 공장의 생산량이 감소하고 수출처가 동남아시아로 전환됨에 따라 생산 능력 동향에 변화가 나타나고 있습니다.
북미에서는 벤젠, 톨루엔 및 크실렌(BTX) 시장 규모는 안정적이지만, 통합이 진행되고 있습니다. 2026년까지 주로 자사 내 스티렌 및 폴리에스터 생산 라인을 대상으로 한 신규 생산 능력이 도입될 전망입니다. 캐나다는 안정적인 벤젠 생산을 유지하고 있는 반면, 멕시코는 정유시설 현대화 지연으로 인해 설비 가동률 측면에서 과제에 직면해 있습니다.
유럽의 점유율은 기존 정유시설들이 방향족 화합물 생산에서 중점을 옮기면서 축소되고 있습니다. 일부 공장은 폐쇄되거나 바이오연료 생산용으로 용도가 전환되고 있습니다. 그러나 일부 시설은 여전히 견조한 모습을 보이며 상당한 생산 능력을 자랑하고 있습니다. 남미는 한 대규모 복합 시설을 필두로 세계 생산량에 기여하고 있으며, 중동 및 아프리카의 기여도도 생산 능력 확대와 신규 프로젝트에 힘입어 증가하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the benzene-Toluene-Xylene market size is projected to be 149.82 million tons in 2025, 155.83 million tons in 2026, and reach 189.68 million tons by 2031, growing at a CAGR of 4.01% from 2026 to 2031.
This report is Segmented by Type (Benzene, Toluene, Xylene [Ortho, Meta, and Para]), Application (Benzene [Ethylbenzene, Cyclohexane, Alkylbenzene, Cumene, Nitrobenzene, and Other], Toluene [Coatings, Adhesives/Inks, Explosives, and Chemical Intermediates], Xylenes [Solvents, Monomer, and Other]), and Geography (Asia-Pacific, North America, Europe, and More). Market Forecasts are in Volume (Tons).
Global Benzene-Toluene-Xylene (BTX) Market Trends and Insights
CAPEX Boom in New Aromatics Complexes Reshapes Regional Supply
Between 2024 and 2027, China, India, Saudi Arabia, and Malaysia are set to unveil greenfield and brownfield aromatics projects. In March 2024, a para-xylene unit was inaugurated in Gulei, boasting a significant capacity. Meanwhile, a facility at Pengerang is on the verge of completion, eyeing a mid-2026 debut. Late in 2024, a project expanded its capacity by leveraging a toluene hydro-dealkylation loop for benzene production. Together, these ventures contribute to BTX supply, further solidifying Asia-Pacific's dominance in production. By mandating compliance with ISO 9001 and ISO 14001, the projects emphasize construction quality, emissions monitoring, and worker safety. This commitment elevates initial capital intensity but mitigates operational risks over the project's lifespan.
Surging PET Demand Keeps Para-Xylene Balances Tight
In India, Indonesia, and Vietnam, where per-capita PET penetration lags behind North America's, the demand for polyethylene terephthalate resin is surging, predominantly for beverage bottles. Para-xylene, accounting for the majority of xylene demand, is in high demand because producing purified terephthalic acid (PTA) requires this feedstock. Zhejiang-based Rongsheng Petrochemical operates para-xylene facilities with significant annual capacity, running at high utilization, which leaves little room for unexpected demand surges. While ortho and meta-xylene together make up a smaller portion of xylene consumption, their growth is tempered, largely due to phthalic anhydride's struggle against plasticizer substitutions. In January 2026, the premium of para-xylene over mixed xylene reached its peak since 2021. This price surge has led refiners to modify their toluene disproportionation loops, resulting in a trade-off where ortho-xylene and benzene outputs are compromised. To protect downstream polymer catalysts, adherence to ASTM D5453 standards is crucial, ensuring sulfur levels remain below 1 ppm.
Carcinogenicity-Driven Exposure Limits Raise Compliance Costs
The U.S. Occupational Safety and Health Administration (OSHA) enforces strict benzene exposure limits: a time-weighted average of 1 ppm and a short-term ceiling of 5 ppm. These measures are in response to links between benzene overexposure and acute myeloid leukemia. Operators are now mandated to invest in sealed loading arms, vapor-recovery systems, and real-time air monitors. Additionally, they must finance annual blood tests for staff with exposure records surpassing the set thresholds. The World Health Organization (WHO) and corresponding EU directives advocate for these stringent thresholds on a global scale. Retrofitting a mid-1980s aromatics extraction train to meet contemporary ventilation and monitoring standards demands significant investment. Furthermore, for a plant with 100 personnel, ongoing surveillance and personal protective equipment (PPE) expenses are considerable. In 2025, Shell closed its aging Pulau Bukom benzene unit, deeming the upgrade costs economically unviable. Similarly, SABIC shut down its Geleen operations for the same reason.
Other drivers and restraints analyzed in the detailed report include:
- Refinery-Petrochemical Integration Unlocks Captive Extraction
- Styrene-Linked Ethylbenzene Revival in Post-Tariff Markets
- VOC Caps in Coatings Redirect Solvent Demand
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, benzene accounted for 38.33% of the total volume, bolstering chains from ethylbenzene to styrene, cyclohexane to nylon, and cumene to bisphenol A. Ethylbenzene, in particular, consumed a major share of the 2025 benzene output. The market for benzene derivatives within the Benzene-Toluene-Xylene (BTX) segment is projected to grow steadily through 2031. Demand from detergents and polyurethanes has secured an additional share from cumene, nitrobenzene, and alkylbenzene. Cyclohexane, accounting for a notable portion of benzene's usage, is witnessing growth, driven by the increasing adoption of nylon 6 fiber in automotive under-hood components.
Toluene, while smaller today, is the Benzene-Toluene-Xylene (BTX) market's fastest-advancing aromatic at a 4.48% CAGR. As of now, a significant portion of toluene is being funneled into disproportionation and trans-alkylation units, producing benzene and para-xylene, a notable rise from earlier years. While traditional sectors like paint, ink, and adhesives-previously accounting for a substantial share of toluene's consumption-have diminished due to VOC regulations, niches such as explosives and nitration chemistry continue to thrive. Adhering to ASTM purity standards ensures that metal and sulfur contaminants remain within catalyst-tolerance limits, thereby enhancing downstream efficiency.
Complete Report Scope:
- By Type
- Benzene
- Toluene
- Xylene
- Ortho-xylene
- Meta-xylene
- Para-xylene
- By Application
- Benzene
- Ethylbenzene
- Cyclohexane
- Alkylbenzene
- Cumene
- Nitrobenzene
- Other Applications
- Toluene
- Paints and Coatings
- Adhesives and Inks
- Explosives
- Chemical Intermediates
- Xylenes
- Solvents
- Monomer
- Other Applications
- Benzene
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific anchored 62.41% of 2025 volume and is forecast to clock a 4.22% CAGR through 2031. China commands a significant portion of the regional demand, driven by para-xylene production operating at near full capacity. Meanwhile, India is set to bolster this demand further, with additional aromatics capacity being added between 2024 and 2026. In Japan and South Korea, capacity dynamics shift as output is reduced in some units and exports are redirected towards Southeast Asia.
North America sees its Benzene-Toluene-Xylene (BTX) market size stabilize, albeit with greater integration. By 2026, new capacity is set to be introduced, predominantly targeting in-house styrene and polyester chains. While Canada maintains steady benzene output, Mexico faces challenges with unit utilization, hindered by delays in refinery modernization.
Europe's share shrinks as traditional refineries shift focus from aromatics. Some units have been closed or repurposed for biofuel production. However, certain facilities remain resilient, boasting significant production capacities. South America, spearheaded by a major complex, contributes to the global volume, while contributions from the Middle-East and Africa rise, buoyed by capacity extensions and new projects.
- BASF
- BP p.l.c.
- Chevron Phillips Chemical Company LLC
- China Petrochemical Corporation
- China National Offshore Oil Corporation (CNOOC)
- Dow
- ENEOS Corporation
- Exxon Mobil Corporation
- Formosa Plastics Group
- GS Caltex Corporation
- INEOS
- IRPC Public Company Limited
- JFE Chemical Corporation
- JX Nippon Oil & Gas Exploration Corporation (ENEOS)
- Mitsubishi Gas Chemical Trading, Inc.
- MOLGROUP
- OCI Company Ltd.
- Reliance Industries Limited
- SABIC
- Shell plc
- S-OIL Corporation
- TotalEnergies
- YEOCHUN NCC CO., LTD.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 CAPEX boom in new aromatics complexes (Asia and Middle-East)
- 4.2.2 Surging PET demand keeps para-xylene balances tight
- 4.2.3 Refinery-petchem integration unlocking captive BTX extraction
- 4.2.4 Styrene-linked ethylbenzene revival in post-tariff U.S. and India
- 4.2.5 China's refinery's Aromatics-Plus policy incentives for high-purity BTX
- 4.3 Market Restraints
- 4.3.1 Carcinogenicity-driven occupational exposure curbs
- 4.3.2 VOC caps in paints/adhesives favour low-aromatic blends
- 4.3.3 Octane-for-aromatics trade-off in gasoline pool after E10 rollout
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Type
- 5.1.1 Benzene
- 5.1.2 Toluene
- 5.1.3 Xylene
- 5.1.3.1 Ortho-xylene
- 5.1.3.2 Meta-xylene
- 5.1.3.3 Para-xylene
- 5.2 By Application
- 5.2.1 Benzene
- 5.2.1.1 Ethylbenzene
- 5.2.1.2 Cyclohexane
- 5.2.1.3 Alkylbenzene
- 5.2.1.4 Cumene
- 5.2.1.5 Nitrobenzene
- 5.2.1.6 Other Applications
- 5.2.2 Toluene
- 5.2.2.1 Paints and Coatings
- 5.2.2.2 Adhesives and Inks
- 5.2.2.3 Explosives
- 5.2.2.4 Chemical Intermediates
- 5.2.3 Xylenes
- 5.2.3.1 Solvents
- 5.2.3.2 Monomer
- 5.2.3.3 Other Applications
- 5.2.1 Benzene
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 Italy
- 5.3.3.4 France
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 BASF
- 6.4.2 BP p.l.c.
- 6.4.3 Chevron Phillips Chemical Company LLC
- 6.4.4 China Petrochemical Corporation
- 6.4.5 China National Offshore Oil Corporation (CNOOC)
- 6.4.6 Dow
- 6.4.7 ENEOS Corporation
- 6.4.8 Exxon Mobil Corporation
- 6.4.9 Formosa Plastics Group
- 6.4.10 GS Caltex Corporation
- 6.4.11 INEOS
- 6.4.12 IRPC Public Company Limited
- 6.4.13 JFE Chemical Corporation
- 6.4.14 JX Nippon Oil & Gas Exploration Corporation (ENEOS)
- 6.4.15 Mitsubishi Gas Chemical Trading, Inc.
- 6.4.16 MOLGROUP
- 6.4.17 OCI Company Ltd.
- 6.4.18 Reliance Industries Limited
- 6.4.19 SABIC
- 6.4.20 Shell plc
- 6.4.21 S-OIL Corporation
- 6.4.22 TotalEnergies
- 6.4.23 YEOCHUN NCC CO., LTD.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


