

|
시장보고서
상품코드
2124737
유럽의 디지털 거래 관리(DTM) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Digital Transaction Management (DTM) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
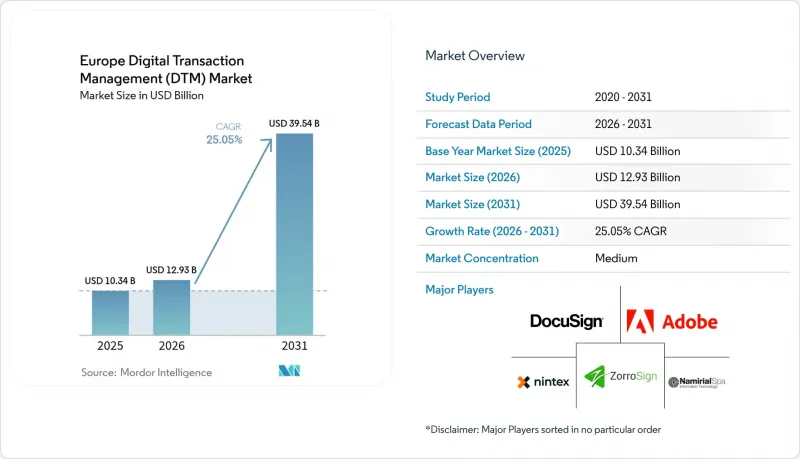
에 의하면, 2026년 유럽의 디지털 거래 관리 시장 규모는 129억 3,000만 달러로 추정되고, 2025년 103억 4,000만 달러에서 확대해, 2031년에는 395억 4,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 25.05%가 될 것으로 전망됩니다.
본 보고서는 구성 요소별(솔루션, 서비스), 도입 형태별(클라우드, 온프레미스, 기타), 조직 규모별(중소기업, 대기업), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 헬스케어 및 생명과학, 소매 및 전자상거래, 기타) 및 국가별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시됩니다.
유럽의 디지털 거래 관리(DTM) 시장 동향 및 인사이트
전자 서명 및 클라우드 도입 증가
유럽의 입법 기관은 전자 서명 서비스의 연간 매출이 25%의 안정적인 성장세를 보일 것으로 예측하고 있으며, 이로 인해 이미 거래의 77.70%를 차지하고 2030년까지 가장 높은 연평균 성장률(CAGR)을 기록하고 있는 클라우드 모델이 더욱 확대될 전망입니다. 북유럽 국가 정부들은 거의 종이 없는 공공 서비스를 추진하고 있으며, 덴마크는 시민과의 거래에서 종이 매체 선택지를 대부분 폐지했고, 스웨덴은 현금 없는 경제 실현에 한 걸음 더 다가서고 있습니다. eIDAS 2.0은 EU의 인증 신뢰 서비스를 기반으로 발급된 원격 서명을 승인함으로써 국경을 초월한 장벽을 제거합니다. BFSI(은행 및 금융 및 보험) 이해관계자들도 의무화된 10초 이내에 즉시 결제를 인증하기 위해 클라우드의 확장성에 의존하고 있으며, 클라우드 아키텍처는 범유럽 신뢰 서비스의 사실상의 기반으로 자리 잡고 있습니다.
중소기업을 통한 종단간 워크플로우 자동화 추진
유럽 기업의 99% 이상을 중소기업이 차지하고 있지만, 디지털 규정 준수 부담은 530억 유로에 달할 전망입니다. EU의 디지털·유럽 기금(Digital and European Fund)을 통한 표적 지원은 이러한 비용을 부분적으로 상쇄하고 있으며, 중소기업의 도입률을 연평균 성장률(CAGR) 26.50%로 끌어올리고 있습니다. Visma와 같은 통합 기업은 KYC, 청구서 발행, 서명 기능을 턴키형 패키지로 묶은 틈새 플랫폼을 인수함으로써 이러한 추세에 대응하고 있습니다. 현재 중소기업의 72%가 데이터 기반 의사결정 도구에 의존하고 있는 만큼, 구독형 노코드 자동화에 대한 수요는 단순한 편의성을 넘어 생존을 위한 필수 요건으로 변화하고 있습니다.
견고한 데이터 프라이버시 및 사이버 위험에 대한 우려
실시간 결제에서는 10초 이내의 결제 처리가 요구되지만, 한편으로는 많은 경우 국내 데이터 보관을 의무화하는 GDPR(EU 개인정보보호규정)의 데이터 최소화 규칙도 준수해야 합니다. NIS2 지침에 따라 정보 유출 통지 의무가 확대되고 벌금도 인상됨에 따라, 많은 은행은 개인정보 보호 제약에 저촉되지 않으면서도 증가하는 부정 시도에 대처할 수 있는 AI 기반 이상 감지 시스템을 도입하고 있습니다. 특히 중소기업은 전문적인 보안 인력 확보에 어려움을 겪고 있어, 플랫폼에 내장된 벤더 제공의 규정 준수 기능의 필요성이 부각되고 있습니다.
부문 분석
2025년, 유럽의 디지털 거래 관리 시장에서 솔루션이 시장 점유율의 70.85%를 차지했습니다. 이는 서명, 신원 확인, 워크플로우, 감사 기능을 하나의 라이선스로 통합한 플랫폼이 배경에 있습니다. 서비스 부문의 점유율은 작지만, 특히 eIDAS 지갑 통합 및 즉시 결제 의무화에 따라 조직이 복잡한 업무를 관리형 서비스 제공업체에 위탁하는 경향이 강해지고 있어 연평균 성장률(CAGR) 23.15%로 확대되고 있습니다. 각 벤더사는 AI를 접목하여 문서의 자동 분류, 본인 확인, 알림 발동을 수행하고 있으며, 이를 통해 직원의 부담을 경감하는 동시에 서비스 확대 속도가 빠르더라도 솔루션 수익이 총 지출에서 계속해서 지배적인 위치를 유지할 수 있도록 보장하고 있습니다.
컨설팅 수요는 규제 도입 시점에 정점을 찍은 후, 이후에는 플랫폼 이용료가 지속적인 수익원이 됩니다. 유럽 헬스 데이터 스페이스(European Health Data Space) 프레임워크 하에서 자금을 지원받는 의료 프로젝트에서는 인증된 트러스트 서비스 통합에 예산이 특별히 배정되어 있어, 이를 통해 다년간의 플랫폼 계약이 확정되고 있습니다. 그 결과, 유럽의 주요 소프트웨어 기업들은 도입 인력을 확보하고 플랫폼에서의 우위를 지키기 위해 틈새 서비스 기업들을 인수하고 있습니다.
2025년, 유럽 시장 규모 중 클라우드 솔루션은 78.15%를 차지했으며, 연평균 성장률(CAGR) 27.95%로 성장하고 있어 온프레미스에서 클라우드 아키텍처로의 전환을 뒷받침하고 있습니다. 프로바이더는 실시간 규정 준수 업데이트, 지오펜스 지원 데이터센터, 온프레미스 환경에서는 재현하는 데 막대한 비용이 드는 지연 보장 등을 제공합니다. 연중무휴 24시간 즉시 결제 운영을 의무화하는 규제 요건으로 인해, 처리량이 급증할 때 자동 확장이 가능한 탄력적인 클라우드 리소스로의 전환이 더욱 가속화되고 있습니다.
하이브리드 환경은 핵심 원장 데이터를 온프레미스에 보관하면서 고객을 대상으로 하는 업무를 클라우드로 분산하고자 하는 금융 기관에게 여전히 전환의 길로 남아 있습니다. 하지만 이러한 경우에도 감사 추적 및 서명 검증은 대개 관리형 환경에 배치됩니다. 완전히 클라우드 기반으로 구축된 북유럽 국가들의 정부 포털은 강력한 개인정보 보호 조치를 취하면서도 전국 규모의 디지털 서비스를 대규모로 운영할 수 있음을 입증하고 있으며, 이에 뒤처져 있던 국가들도 유사한 노력을 추진하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, Europe digital transaction management market size in 2026 is estimated at USD 12.93 billion, growing from 2025 value of USD 10.34 billion with 2031 projections showing USD 39.54 billion, growing at 25.05% CAGR over 2026-2031.
This report is Segmented by Component (Solutions, Services), Deployment Mode (Cloud, On-Premise, and More), Organisation Size (Small and Medium Enterprises, Large Enterprises), End-User Industry (BFSI, Healthcare and Life Sciences, Retail and E-Commerce, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Digital Transaction Management (DTM) Market Trends and Insights
Rise in e-signatures and cloud adoption
European legislators project stable 25% yearly revenue gains for e-signature services, propelling cloud models that already hold 77.70% of transactions and register the fastest CAGR through 2030. Nordic governments showcase near-paperless public services, with Denmark eliminating hard-copy options for most citizen interactions and Sweden nearing a cash-free economy. eIDAS 2.0 removes cross-border friction by recognising remote signatures issued under any qualified EU trust service. BFSI stakeholders also depend on cloud scalability to authenticate instant payments within the mandated 10 seconds, cementing cloud architecture as the de facto backbone of pan-European trust services.
SME push for end-to-end workflow automation
SMEs account for over 99% of European businesses yet carry a EUR 53 billion digital-compliance burden. Targeted EU Digital Europe funds partially offset those costs and are catalysing 26.50% CAGR uptake among smaller firms. Consolidators such as Visma have responded by acquiring niche platforms that package KYC, invoicing and signing features into turnkey bundles. As 72% of SMEs now rely on data-driven decision tools, the demand for subscription-based, no-code automation has evolved from a convenience to a survival requirement .
Persistent data-privacy and cyber-risk concerns
Real-time payments demand 10-second clearing and yet must honour GDPR data-minimisation rules that often require data residency within national borders. The NIS2 directive widens breach-notification duties and raises fines, leading many banks to deploy AI-based anomaly detection that can handle rising fraud attempts without infringing privacy constraints. Smaller firms particularly struggle to finance specialist security skills, underscoring the need for vendor-provided compliance capabilities baked into platforms.
Other drivers and restraints analyzed in the detailed report include:
- EU eIDAS 2.0 and PSD3 accelerating trust services
- Post-COVID permanent shift to digital workflows
- High integration and change-management costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions accounted for 70.85% of the Europe Digital Transaction Management market share in 2025 on the back of platforms that bundle signing, identity, workflow and audit functions under one licence. The services slice is smaller but rising at 23.15% CAGR as organisations outsource complexity to managed providers, especially for eIDAS wallet integration and instant-payment obligations. Vendors embed AI to auto-classify documents, verify identities and trigger alerts, reducing staff overheads and ensuring that solutions revenue continues to dominate absolute spend even while services expand faster.
Demand for consulting peaks during regulation roll-outs, after which recurring platform fees drive sustained revenue. Healthcare projects funded under the European Health Data Space allocate budget specifically to qualified trust-service integration, thereby locking in multi-year platform contracts. European software majors are consequently acquiring niche service firms to secure implementation talent and defend platform primacy.
Cloud solutions held 78.15% of the Europe Digital Transaction Management market size in 2025 and are growing at 27.95% CAGR, reinforcing the architectural pivot away from on-premise. Providers offer real-time compliance updates, geo-fenced data centres and latency guarantees that on-premise installs find costly to replicate. Regulatory requirements for 24/7 instant-payment uptime further tilt adoption toward elastic cloud resources that can auto-scale during volume spikes.
Hybrid remains a transition path for financial institutions that wish to retain core-ledger data locally while routing customer-facing activity to the cloud. Nevertheless, even in these cases audit trails and signature verification often reside in managed environments. Nordic government portals, built completely in the cloud, supply proof points that nationwide digital services can run at scale with strong privacy safeguards, causing lagging countries to follow suit.
Complete Report Scope:
- By Component
- Solutions
- Services
- By Deployment Mode
- Cloud
- On-premise
- Hybrid
- By Organisation Size
- Small and Medium Enterprises
- Large Enterprises
- By End-user Industry
- BFSI
- Healthcare and Life Sciences
- Retail and E-commerce
- IT and Telecommunication
- Government and Public Sector
- Real-Estate and Construction
- Automotive and Mobility
- By Country
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
List of Companies Covered in this Report:
- Adobe Inc.
- DocuSign Inc.
- Namirial SpA
- InfoCert SpA (Tinexta SpA)
- Signicat AS
- Scrive AB
- PandaDoc Inc.
- Dropbox Sign (HelloSign)
- airSlate Inc. (SignNow)
- Nintex UK Ltd
- Mitratech Holdings Inc.
- AssureSign LLC (Equifax)
- Topaz Systems Inc.
- ZorroSign Inc.
- OneSpan Inc.
- Entrust Corporation
- eMudhra Ltd.
- Universign SAS
- Kofax Inc.
- Nitro Software Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise in e-signatures and cloud adoption
- 4.2.2 SME push for end-to-end workflow automation
- 4.2.3 EU eIDAS 2.0 and PSD3 accelerating trust services
- 4.2.4 Post-COVID permanent shift to digital workflows
- 4.2.5 Mandatory B2B e-invoicing roll-outs across EU
- 4.2.6 Instant-payment rails driving real-time DTM demand
- 4.3 Market Restraints
- 4.3.1 Persistent data-privacy and cyber-risk concerns
- 4.3.2 High integration and change-management costs
- 4.3.3 Fragmented national eID schemes hinder interoperability
- 4.3.4 Tight SME financing slows tech refresh cycles
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-premise
- 5.2.3 Hybrid
- 5.3 By Organisation Size
- 5.3.1 Small and Medium Enterprises
- 5.3.2 Large Enterprises
- 5.4 By End-user Industry
- 5.4.1 BFSI
- 5.4.2 Healthcare and Life Sciences
- 5.4.3 Retail and E-commerce
- 5.4.4 IT and Telecommunication
- 5.4.5 Government and Public Sector
- 5.4.6 Real-Estate and Construction
- 5.4.7 Automotive and Mobility
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Spain
- 5.5.5 Italy
- 5.5.6 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 DocuSign Inc.
- 6.4.3 Namirial SpA
- 6.4.4 InfoCert SpA (Tinexta SpA)
- 6.4.5 Signicat AS
- 6.4.6 Scrive AB
- 6.4.7 PandaDoc Inc.
- 6.4.8 Dropbox Sign (HelloSign)
- 6.4.9 airSlate Inc. (SignNow)
- 6.4.10 Nintex UK Ltd
- 6.4.11 Mitratech Holdings Inc.
- 6.4.12 AssureSign LLC (Equifax)
- 6.4.13 Topaz Systems Inc.
- 6.4.14 ZorroSign Inc.
- 6.4.15 OneSpan Inc.
- 6.4.16 Entrust Corporation
- 6.4.17 eMudhra Ltd.
- 6.4.18 Universign SAS
- 6.4.19 Kofax Inc.
- 6.4.20 Nitro Software Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


