

|
시장보고서
상품코드
2124740
의료 상호운용성 솔루션 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Global Healthcare Interoperability Solutions - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 의료 상호운용성 솔루션 시장 규모는 56억 1,000만 달러로 추정되고, 2025년 50억 4,000만 달러에서 확대해, 2031년에는 95억 7,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 11.27%를 나타낼 전망입니다.
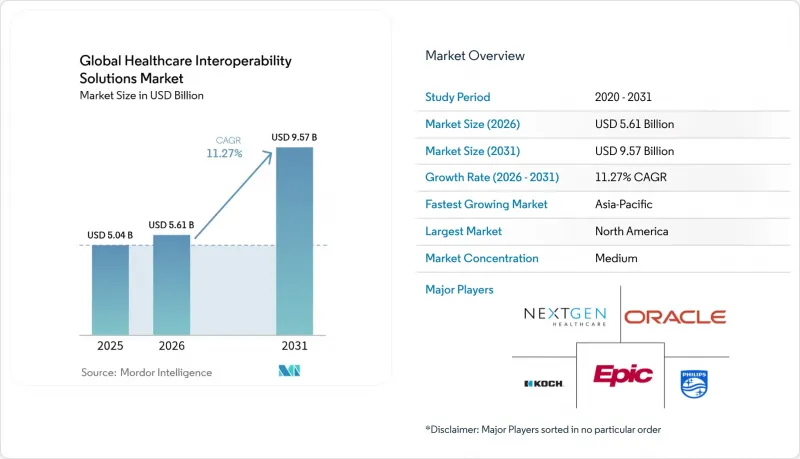
본 보고서는 구성 요소별(소프트웨어, 서비스, 플랫폼/미들웨어), 상호운용성 수준별(기반적, 구조적, 의미적, 조직적), 도입 형태별(온프레미스 등), 최종 사용자별(병원·의료 시스템, 외래·전문 클리닉 등), 지역별(북미, 유럽 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 의료 상호운용성 솔루션 시장 동향 및 인사이트
EHR 상호운용성에 관한 규제상 의무
위반 1건당 최대 100만 달러의 벌금이 부과되는 정보 차단에 대한 제재로 인해, API 표준화는 이사회 차원의 최우선 과제가 되었으며, 의료 제공업체들은 21세기 치료법(21st Century Cures Act)을 준수하는 HL7 FHIR R4 엔드포인트의 도입을 강요받고 있습니다. TEFCA는 2024년에 운영을 시작하여, 인증된 의료 정보 네트워크(Qualified Health Information Networks)를 통해 625개 이상의 병원을 신속하게 연결함으로써 전국적인 데이터 교환의 실현 가능성을 입증했습니다. 유럽의 EHDS 규정 또한 이러한 압력을 반영하여, FHIR 및 SNOMED CT를 활용한 국경을 초월한 데이터 마이그레이션성을 의무화하고 있습니다. 이에 따라 병원들은 미들웨어, 거버넌스 정책, 그리고 직원 역량 강화를 동시에 추진해야만 합니다. 이러한 규제는 종합적으로 의료 상호운용성 솔루션 시장에 대한 자본 배분을 가속화하고 있습니다.
클라우드 기반 의료 IT의 채택 확대
Microsoft Azure의 FHIR 서비스는 2024년에 월간 API 호출 횟수가 10억 건을 돌파했으며, 대규모 환경에서도 탄력적인 성능을 발휘하고 있습니다. NextGen은 자사의 Mirth 인터페이스 엔진을 관리형 클라우드 서비스로 이전하여 프로비저닝 시간을 몇 주에서 몇 시간으로 단축하는 동시에 중규모 병원의 운영 비용을 절감했습니다. 하이브리드 배포가 표준으로 자리 잡아가면서, 기밀성이 높은 아카이브는 온프레미스에 보관하고 분석 워크로드는 클라우드로 분산함으로써, 헬스케어 상호운용성 솔루션 시장의 추가적인 확산이 촉진되고 있습니다.
통합 프로젝트의 높은 비용
맞춤형 구성, 마이그레이션, 직원 교육 비용을 합산하면, 여러 시설에 걸친 복잡한 도입 비용은 8자리 수를 초과하기도 합니다. 소규모 병원은 이러한 자본 지출을 많은 환자 수로 분산시킬 만한 규모가 없기 때문에 단계적인 도입을 할 수밖에 없으며, 이로 인해 헬스케어 상호운용성 솔루션 시장의 확산이 지연되고 있습니다. 또한, CFO는 사이버 보안, 라이선싱, AI 시범 프로젝트에 대한 자금을 동시에 확보해야 하기 때문에 예산이 부족해지고 계약 주기가 장기화되고 있습니다.
부문 분석
2025년에는 소프트웨어가 매출의 46.02%를 차지했습니다. 이는 통합 제품군이 EHR 연결, FHIR 변환 및 분석 기능을 단일 계약으로 묶어 벤더 관리를 용이하게 하고 가치 실현까지의 시간을 단축하기 때문입니다. 플랫폼/미들웨어는 로우코드 API 허브를 사용하여 레거시 HL7 v2 피드를 클라우드상의 FHIR 스토리지에 연결하는 병원들 수요에 힘입어 연평균 성장률(CAGR) 11.67%를 나타낼 것으로 예측됩니다. 설정, 거버넌스 설계, 라이프사이클 지원에는 여전히 서비스가 필수적이며, 많은 경우 총 예산의 3분의 1을 차지합니다.
가격 모델은 영구 라이선스에서 트랜잭션 기반 구독으로 전환되고 있어 지역 병원의 진입 장벽이 낮아지고 있습니다. 미들웨어 공급업체들은 현재 확립된 엔진을 SaaS 포털로 감싸, TEFCA를 지원하는 턴키 솔루션과 자동화된 규정 준수 보고 기능을 제공합니다. Epic의 플랫폼 접근 방식은 기존 기업들이 상호 운용성을 임상 워크플로우의 심층부에 통합함으로써 시장 점유율을 유지하고 있음을 보여줍니다. 반면, Redox와 같은 API 우선 벤더는 벤더 중립성을 추구하는 구매자가 있는 신규 도입 프로젝트에서 우위를 점하고 있습니다. 따라서 시장에서는 신속한 매핑 도구와 미리 구축된 규제 대응 템플릿을 결합한 공급업체가 높이 평가받고 있습니다.
2025년에는 조직들이 우선 메시지 라우팅 및 문서 교환에 집중함에 따라 구조적 상호 운용성이 41.52%의 점유율을 차지했습니다. AI 기반 분석 및 인구 건강 대시보드에는 의료 제공 거점 전반에 걸친 코드화된 데이터가 필요하기 때문에 의미적 상호 운용성은 연평균 성장률(CAGR) 12.41%로 확대될 것으로 예측됩니다. HL7 FHIR R5는 값 세트의 바인딩을 강화하고, 더 풍부한 코딩 가능한 개념을 지원함으로써 의미적 성숙도를 높이고 있습니다.
기반적 및 조직적 상호운용성은 안전한 전송과 거버넌스에 여전히 필수적이지만, 향후 점진적인 성장률은 낮아질 전망입니다. 병원들은 이종 어휘를 통합하기 위해 용어 서버, 환자 마스터 인덱스, 데이터 품질 엔진에 투자하고 있으며, 시맨틱 기능을 최종 목표로 삼고 있습니다. 그 결과, 시장 전반에 걸쳐 5개년 디지털 헬스 로드맵에 시맨틱 툴킷이 통합되었습니다.
지역별 분석
북미는 ONC의 명확한 의무화, 견고한 광대역 환경, 그리고 TEFCA의 조기 도입에 힘입어 2025년에도 41.85%의 점유율을 유지했습니다. 아시아태평양은 일본의 국가 의료 DX 프로그램에 따른 전자 건강 기록의 표준화와 호주의 상호 운용성 계획에 따른 FHIR 도입에 대한 자금 지원을 배경으로 연평균 성장률(CAGR) 12.67%를 나타낼 것으로 예측됩니다. 유럽에서는 GDPR(EU 개인정보보호규정)로 인한 도입의 복잡성에도 불구하고 EHDS 규제가 수요를 뒷받침하고 있습니다. 한편, 남미 및 중동 및 아프리카은 초기 단계에 있지만, 자본 제약을 피하기 위해 클라우드 호스팅형 HIE를 점점 더 중시하고 있습니다.
신흥 시장의 정부 부처에서는 자본 지출(CapEx)을 운영 비용(OpEx)으로 전환하기 위해 매니지드 서비스 가격 체계를 채택하는 경우가 많아, 다국어 지원 및 소버린 클라우드 옵션을 제공할 수 있는 벤더에게 새로운 비즈니스 기회가 창출되고 있습니다. 걸프협력회의(GCC) 및 아세안(ASEAN) 지역의 국경을 초월한 원격 의료도 또 다른 촉진요인으로 작용하고 있으며, 이를 통해 지역 기업들은 표준 기반의 ID 페더레이션을 요구하는 시장에 진출하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 전망(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측(금액, 2024-2030년)
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, healthcare interoperability solutions market size in 2026 is estimated at USD 5.61 billion, growing from 2025 value of USD 5.04 billion with 2031 projections showing USD 9.57 billion, growing at 11.27% CAGR over 2026-2031.
This report is Segmented by Component (Software, Services, Platforms/Middleware), Interoperability Level (Foundational, Structural, Semantic, Organizational), Deployment Mode (On-Premise, and More), End User (Hospitals & Health Systems, Ambulatory & Specialty Clinics, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Healthcare Interoperability Solutions Market Trends and Insights
Regulatory mandates for EHR interoperability
Information-blocking penalties of up to USD 1 million per violation have turned API standardization into a board-level imperative, forcing providers to adopt HL7 FHIR R4 endpoints that comply with the 21st Century Cures Act. TEFCA went live in 2024 and quickly connected more than 625 hospitals through Qualified Health Information Networks, proving nationwide data exchange viability. Europe's EHDS regulation mirrors this pressure by mandating cross-border data liquidity using FHIR and SNOMED CT, compelling hospitals to upgrade middleware, governance policies, and workforce skills simultaneously. These mandates collectively accelerate capital allocation toward the Healthcare Interoperability Solutions market.
Growing adoption of cloud-based healthcare IT
Microsoft Azure's FHIR service surpassed 1 billion monthly API calls in 2024, demonstrating elastic performance at scale. NextGen migrated its Mirth interface engine to a managed cloud service, shrinking provisioning time from weeks to hours and cutting operating expenses for mid-tier hospitals. Hybrid deployment is becoming the norm, keeping sensitive archives on-premise while bursting analytics workloads to the cloud, and thereby propelling further adoption within the Healthcare Interoperability Solutions market.
High cost of integration projects
Complex multi-facility deployments can exceed eight figures once customization, migration, and staff training are tallied. Smaller hospitals lack the scale to dilute these capital outlays across large patient volumes, forcing phased rollouts that slow Healthcare Interoperability Solutions market penetration. CFOs must also fund cybersecurity, cloud licensing, and AI pilots concurrently, stretching budgets and elongating deal cycles.
Other drivers and restraints analyzed in the detailed report include:
- Shift to value-based care requiring integrated data
- Expansion of telehealth & remote monitoring
- Data privacy & security concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software contributed 46.02% revenue in 2025 because integrated suites bundle EHR connectivity, FHIR translation, and analytics in a single contract, easing vendor management and accelerating time to value. Platforms / middleware is forecast to grow 11.67% CAGR, driven by hospitals that use low-code API hubs to connect legacy HL7 v2 feeds with cloud FHIR stores. Services remain indispensable for configuration, governance design, and lifecycle support, often absorbing one-third of total budgets.
Pricing models have shifted from perpetual licenses to transaction-based subscriptions, lowering entry barriers for community hospitals. Middleware suppliers now wrap SaaS portals around established engines, providing turnkey TEFCA readiness and automated compliance reporting. Epic's platform approach illustrates how incumbents defend share by embedding interoperability deep in their clinical workflows, whereas API-first vendors such as Redox win greenfield deployments where buyers want vendor neutrality. The Healthcare Interoperability Solutions market therefore rewards suppliers that combine rapid-mapping tools with pre-built regulatory templates.
Structural interoperability held 41.52% share in 2025 as organizations first focused on message routing and document exchange. Semantic interoperability is projected to expand at 12.41% CAGR because AI-driven analytics and population-health dashboards require codified data across sites of care. HL7 FHIR R5 advances semantic maturity by tightening value-set bindings and adding richer codeable-concept support.
Foundational and organizational layers remain essential for secure transport and governance but will capture less incremental growth. Hospitals are investing in terminology servers, patient-master-indexes, and data-quality engines to unify disparate vocabularies, positioning semantic capabilities as the ultimate goal. As a result, semantic toolkits are now embedded in five-year digital-health roadmaps across the Healthcare Interoperability Solutions market.
Complete Report Scope:
- By Component
- Software
- Services
- Platforms / Middleware
- By Interoperability Level
- Foundational
- Structural
- Semantic
- Organizational
- By Deployment Mode
- On-premise
- Cloud-based
- Hybrid
- By End User
- Hospitals & Health Systems
- Ambulatory & Specialty Clinics
- Laboratories
- Pharmacies
- Payers
- Health Information Exchanges (HIEs)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America retained 41.85% share in 2025 thanks to clear ONC mandates, robust broadband, and early TEFCA onboarding. Asia-Pacific is projected to log a 12.67% CAGR as Japan's national medical DX program standardizes electronic records and Australia's Interoperability Plan funds FHIR roll-outs;. Europe's EHDS regulation boosts demand despite GDPR-driven implementation complexity, while South America and the Middle East & Africa are early-stage but increasingly target cloud-hosted HIEs to bypass capital constraints.
Emerging-market ministries often adopt managed-service pricing to convert CapEx into OpEx, opening white-space for vendors willing to provide multilingual support and sovereign-cloud options. Cross-border telehealth in the Gulf Cooperation Council and ASEAN blocs is another catalyst, pushing regional players into the Healthcare Interoperability Solutions market for standards-based identity federations.
- Oracle
- Epic Systems
- InterSystems
- Koninklijke Philips
- Orion Health
- Meditech
- Allscripts (Altera)
- Change Healthcare
- IBM
- Optum
- athenahealth
- eClinicalWorks
- NextGen Healthcare
- Availity
- Lyniate
- Rhapsody
- Dedalus Group
- Sectra
- CompuGroup Medical
- Health Level Seven International (HL7)
- Redox
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Regulatory mandates for EHR interoperability
- 4.2.2 Growing adoption of cloud-based healthcare IT
- 4.2.3 Shift to value-based care requiring integrated data
- 4.2.4 Expansion of telehealth & remote monitoring
- 4.2.5 Rise of healthcare data marketplaces
- 4.2.6 AI-driven CDS demanding standardized data models
- 4.3 Market Restraints
- 4.3.1 High cost of integration projects
- 4.3.2 Data privacy & security concerns
- 4.3.3 Vendor reluctance to open proprietary APIs
- 4.3.4 Fragmented consent-management frameworks
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, 2024-2030)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.1.3 Platforms / Middleware
- 5.2 By Interoperability Level
- 5.2.1 Foundational
- 5.2.2 Structural
- 5.2.3 Semantic
- 5.2.4 Organizational
- 5.3 By Deployment Mode
- 5.3.1 On-premise
- 5.3.2 Cloud-based
- 5.3.3 Hybrid
- 5.4 By End User
- 5.4.1 Hospitals & Health Systems
- 5.4.2 Ambulatory & Specialty Clinics
- 5.4.3 Laboratories
- 5.4.4 Pharmacies
- 5.4.5 Payers
- 5.4.6 Health Information Exchanges (HIEs)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 GCC
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Oracle Cerner
- 6.3.2 Epic Systems
- 6.3.3 InterSystems
- 6.3.4 Koninklijke Philips N.V.
- 6.3.5 Orion Health
- 6.3.6 MEDITECH
- 6.3.7 Allscripts (Altera)
- 6.3.8 Change Healthcare
- 6.3.9 IBM Watson Health
- 6.3.10 Optum
- 6.3.11 athenahealth
- 6.3.12 eClinicalWorks
- 6.3.13 NextGen Healthcare
- 6.3.14 Availity
- 6.3.15 Lyniate
- 6.3.16 Rhapsody
- 6.3.17 Dedalus Group
- 6.3.18 Sectra AB
- 6.3.19 CompuGroup Medical
- 6.3.20 Health Level Seven International (HL7)
- 6.3.21 Redox
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


