

|
시장보고서
상품코드
2124820
디지털 신호 처리장치(DSP) : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Digital Signal Processor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
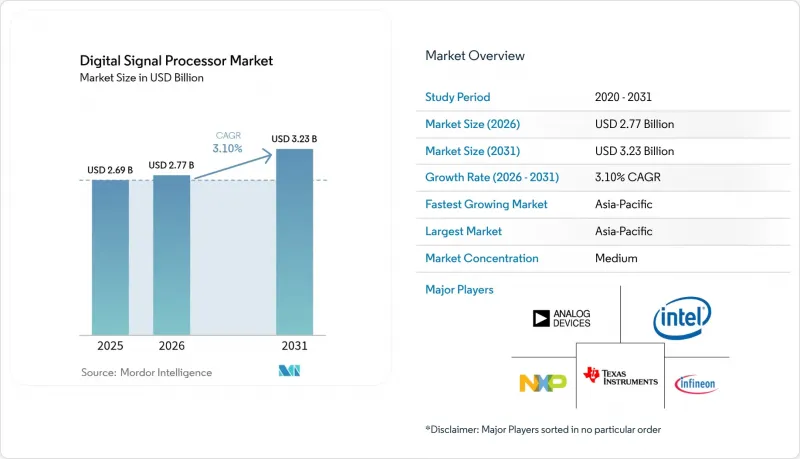
에 의하면, 디지털 신호 처리장치(DSP) 시장 규모는 2025년 26억 9,000만 달러에서 2026년에는 27억 7,000만 달러에 이르고, 2026-2031년 CAGR 3.10%로 성장을 지속하여 2031년에는 32억 3,000만 달러에 달할 것으로 예측됩니다.

본 보고서는 코어 수(싱글 코어 등), 제품 유형(범용 독립형 DSP 등), 아키텍처(SIMD, VLIX 등), 수치 형식(고정 소수점 등), 최종 사용자 산업(통신, 자동차, 소비자 가전 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 디지털 신호 처리장치 시장 동향 및 인사이트
아시아에서의 5G 오픈 RAN 도입 확대
Open RAN 아키텍처는 하드웨어와 소프트웨어의 기능을 분리하고, 독점적인 베이스밴드 카드를 소프트웨어로 재타겟팅이 가능한 프로그래머블 DSP 플랫폼으로 대체합니다. 중국, 일본, 한국의 통신 사업자들은 벤더 종속성을 완화하고 기능 업데이트를 가속화하기 위해 이러한 오픈 스택을 채택하고 있습니다. NVIDIA ARC GPU와 고성능 DSP 코어를 결합한 테스트베드는 다중 사용자 부하 조건에서 500 Mbps를 초과하는 다운링크 속도를 달성했습니다. 이러한 성능 입증을 계기로, 빔포밍, 채널 추정, 프론트홀 압축을 실시간으로 실행하는 멀티코어 및 부동소수점 연산 지원 DSP의 조달 붐이 일고 있습니다. 그 결과로 인한 파급 효과로 아시아태평양에서 상용 실리콘 및 라이선스 가능한 DSP IP의 수주가 증가하고 있을 뿐만 아니라, 북미에서도 2차 도입이 진행되고 있습니다.
자동차용 ADAS의 Tier 1 설계가 MCU에서 DSP 중심의 SoC로 전환되고 있습니다.
차량 1대당 카메라, 레이더, LiDAR의 탑재 수가 증가함에 따라, 마이크로컨트롤러로는 실시간 센서 퓨전을 수행하는 데 필요한 처리량이 부족해지고 있습니다. 이에 따라 Tier 1 공급업체들은 멀티코어 DSP 엔진과 AI 가속기를 결합한 이종 SoC로의 전환을 추진하고 있습니다. AMD의 Zynq UltraScale+ XA MPSoC는 긴밀하게 연동된 DSP 패브릭이 레이더의 처프 신호를 처리하는 한편, 인접한 AI 엔진이 물체를 분류하는 모습을 보여주며, 이 모든 것이 단일 안전 인증 패키지에 포함되어 있습니다. 유럽 및 동아시아의 자동차 공급망은 2027년까지 설계 채택을 꾸준히 진행하고 있으며, 평균 판매 가격이 하락하는 추세 속에서도 두 자릿수의 수량 성장을 뒷받침하고 있습니다.
첨단 노드(7nm 이하) 파운드리에서공급망 변동
대만과 한국에 위치한 소수의 최첨단 팹은 주기적인 지정학적 요인과 물류 혼란에 직면해 있습니다. 생산 능력이 부족해지면 DSP 리드타임이 40주를 초과하여 길어지며, 설계자는 전력 소비 및 성능 목표를 충족하지 못하는 성숙한 공정에서 재테이프아웃을 해야만 합니다. 여러 파운드리 활용 전략과 적응성이 높은 물리적 설계 키트를 보유한 반도체 제조업체는 단일 공급업체와의 제휴에 얽매여 있는 경쟁사보다 영향을 덜 받는 상황입니다.
부문 분석
멀티코어 디바이스는 2025년 매출의 64.30%를 차지하며, 디지털 신호 처리장치 시장 규모 17억 3,000만 달러에 해당하여 5G 베이스밴드, 자동차용 레이더, 산업용 비전 분야에서 그 필수적인 역할을 부각시키고 있습니다. 디지털 신호 처리장치 시장에서는 작업 수준의 병렬 처리가 여러 개의 동종 코어에 자연스럽게 적용되며, 실시간 제약 조건 하에서도 결정론적 지연 시간을 실현할 수 있기 때문에 이러한 부품이 선호되고 있습니다. 텍사스 기기의 C66x 제품군은 8개의 고정 소수점/부동 소수점 코어가 통합된 ‘Multicore Navigator’ 패브릭을 활용하여 복사로 인한 오버헤드를 제거하는 구조를 보여줍니다. 이러한 구성의 유연성 덕분에 의료용 영상 진단, 모터 제어, SATCOM 단말기에 이르는 다양한 제품 라인을 지원합니다.
스마트 미터와 같이 깊이 임베디된 가격에 민감한 엔드 노드에서는 싱글 코어 및 듀얼 코어 옵션이 여전히 존재하지만, DSP, CPU, AI 가속기를 융합한 이종 멀티코어 SoC가 기세를 더하고 있습니다. 2031년까지 연평균 성장률(CAGR) 3.64%가 지속됨에 따라, 디지털 신호 처리장치 시장의 멀티코어 분야 확장 속도는 업계 전체 매출 성장률을 계속해서 상회하고 있습니다. 오픈소스 툴체인이 성숙해짐에 따라 멀티코어 프로그래밍의 부담이 줄어들고, 확장 가능한 타일 기반 패브릭, 스크래치패드 메모리 계층 및 코어 간 메시지 전달을 우선시하는 공급업체의 로드맵이 뒷받침되고 있습니다.
2025년에는 특정 용도용 DSP가 매출의 47.60%, 즉 디지털 신호 처리장치 시장 규모의 12억 8,000만 달러를 차지했습니다. 이는 스마트폰, 기지국, 인포테인먼트 헤드 유닛에서 엄격하게 특화된 명령어 세트와 가속기 블록이 와트당 뛰어난 성능을 실현하고 있기 때문입니다. 이러한 성장은 부품 비용(BOM) 절감과 기판 공간 축소를 추구하는 OEM의 요구와 부합합니다. 퀄컴의 모뎀 통합형 DSP 블록과 아날로그 디바이스의 RF 최적화 코어는 이러한 ‘목적에 부합하는’ 접근 방식의 좋은 예입니다.
그러나 가장 빠른 성장이 예상되는 분야는 보다 광범위한 SoC 프로젝트에 통합되는 라이선싱 가능한 임베디드 DSP IP입니다. 연평균 성장률(CAGR) 4.02%로 성장을 지속하고, 있는 이러한 추세는 EDA 벤더와 소프트웨어 IP 공급업체에게 잠재적인 시장 규모를 확대되고 있습니다. 범용 디스크리트 DSP는 현재 긴 제품 수명 주기가 중요한 군사, 항공우주 및 실험용 계측 장비와 같은 틈새 시장으로 방향을 전환하고 있습니다. FPGA 기반의 하이브리드 제품은 중규모 생산 고객이 ASIC의 위험을 감수하지 않고 재구성 가능성을 필요로 하는 상황에서 맞춤화의 공백을 메우고 있습니다.
지역별 분석
2025년, 아시아태평양은 전 세계 매출의 48.20%를 차지하며, 전 세계 디지털 신호 처리장치 시장의 절반에 조금 못 미치는 비중을 차지했습니다. 중국 혼자서 웨이퍼 수요의 4분의 1 이상을 차지하고 있는데, 이는 중국의 통신 사업자들이 초고밀도 5G 네트워크를 구축하고, 전기차 제조업체들이 차량에 레이더 및 인포테인먼트용 프로세서를 탑재하고 있기 때문입니다. 한국과 일본은 첨단 메모리, 센서, 자동차용 공급망을 통해 추가적인 수요를 견인하고 있습니다. 연평균 성장률(CAGR) 3.74%를 기록하며, 이 지역은 성장 순위 1위를 유지하고 있으며, 그 팹 설비 용량은 첨단 노드 배정이 부족할 때에도 공급 면에서의 우위를 확보하고 있습니다.
북미는 매출과 연구개발(R&D)의 깊이 두 가지 측면에서 2위를 차지하고 있습니다. 실리콘밸리의 스타트업과 오스틴에 기반을 둔 기존 기업들이 최첨단 멀티코어 아키텍처와 신경망 DSP 하이브리드 기술을 주도하는 한편, 미국의 국방 프로젝트는 방사선 내성 부동소수점 연산용 부품에 대한 안정적인 시장을 보장하고 있습니다. ‘CHIPS and Science Act’에 따른 연방 정부의 인센티브는 2027년까지 가동을 시작할 예정인 국내 팹 확장을 촉진하고 있으며, 이는 현지 DSP 제조업체들의 노드 부족 문제를 완화할 것으로 기대됩니다.
유럽은 독일과 프랑스의 자동차 제조업체들로부터의 견조한 수요와 증가하는 머신 비전 통합 업체들에 힘입어 이 3극 구조를 완성하고 있습니다. IPCEI 마이크로일렉트로닉스 등의 지역 이니셔티브는 12인치 웨이퍼용 파일럿 라인을 지원하며, 아시아와의 생산 격차를 좁히고 있습니다. 한편, 남미 및 중동 및 아프리카는 주로 통신 인프라 구축과, 높은 처리량을 자랑하는 DSP 기반 모뎀에 의존하는 위성 광대역 게이트웨이와 관련하여 신흥 시장으로서 기여하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the digital signal processor market size is expected to grow from USD 2.69 billion in 2025 to USD 2.77 billion in 2026 and is forecast to reach USD 3.23 billion by 2031 at 3.10% CAGR over 2026-2031.
This report is Segmented by Core (Single-Core, and More), Product Type (General-Purpose Stand-Alone DSPs, and More), Architecture (Single Instruction Multiple Data, Very-Long-Instruction-Word, and More), Numeric Format (Fixed-Point, and More), End-User Industry (Communication, Automotive, Consumer Electronics, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Signal Processor Market Trends and Insights
Proliferation of 5G Open-RAN Deployments in Asia
Open RAN architectures separate hardware and software functions, replacing proprietary baseband cards with programmable DSP platforms that can be retargeted in software. Operators in China, Japan, and South Korea are using these open stacks to trim vendor lock-in and speed feature updates. Testbeds combining NVIDIA ARC GPUs with high-performance DSP cores have exceeded 500 Mbps downlink under multi-user loads. This performance proof drives a procurement wave for multicore, floating-point-capable DSPs that execute beam-forming, channel estimation, and fronthaul compression in real time. The resulting pull-through effect is lifting orders for both merchant silicon and licensable DSP IP in Asia-Pacific and secondary deployments in North America.
Automotive ADAS Tier-1 Designs Migrating from MCU to DSP-centric SoCs
As camera, radar, and LiDAR counts rise per vehicle, microcontrollers lack the throughput to perform real-time sensor fusion. Tier-1 suppliers are therefore shifting to heterogeneous SoCs combining multi-core DSP engines with AI accelerators. AMD's Zynq UltraScale+ XA MPSoC shows how a tightly coupled DSP fabric processes radar chirps while adjacent AI engines classify objects, all inside a single safety-certified package. The automotive supply chain in Europe and East Asia is committing design wins through 2027, anchoring double-digit unit growth even as average selling prices drift lower.
Supply-chain Volatility in Advanced Node (<= 7 nm) Foundries
A limited pool of ultra-modern fabs in Taiwan and South Korea faces periodic geopolitical and logistics disruptions. When capacity tightens, DSP lead-times stretch beyond 40 weeks, pushing designers to retape-out on mature processes that meet neither power nor performance targets. Chipmakers with multi-foundry strategies and adaptable physical-design kits remain better insulated than rivals locked to single-source partnerships.
Other drivers and restraints analyzed in the detailed report include:
- AI-enhanced Audio & Voice Processing in Hearables and Smart Speakers
- Adoption of Software-Defined Radar in Aerospace & Defense
- Integration Trade-offs Between Fixed- and Floating-Point Precision in Battery-Powered Devices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Multi-core devices generated 64.30% of 2025 revenue, equivalent to a USD 1.73 billion slice of the digital signal processor market size, underscoring their essential role in 5G baseband, automotive radar, and industrial vision. The digital signal processor market favors these parts because task-level parallelism maps naturally to multiple homogeneous cores, allowing deterministic latency under real-time constraints. Texas Instruments' C66x family demonstrates how eight fixed-/floating-point cores harness a unified Multicore Navigator fabric to eliminate copy overhead. The configuration headroom supports product-line variants spanning medical imaging, motor control, and SATCOM terminals.
Single-core and dual-core options survive in deeply embedded, price-sensitive end-nodes such as smart meters, while heterogeneous multi-core SoCs that blend DSP, CPU, and AI accelerators are gaining traction. Sustained 3.64% CAGR through 2031 keeps the multi-core slice of the digital signal processor market expanding faster than overall industry revenue. As open-source toolchains mature, multicore programming burdens fall, reinforcing supplier roadmaps that prioritize scalable tile-based fabrics, scratchpad memory hierarchies, and inter-core message passing.
Application-specific DSPs captured 47.60% of revenue in 2025, or USD 1.28 billion of the digital signal processor market size, because tightly focused instruction sets and accelerator blocks deliver watt-efficient performance in smartphones, base stations, and infotainment head units. Their growth aligns with OEM demands for BOM savings and board-space reductions. Qualcomm's modem-integrated DSP blocks and Analog Devices' RF-optimized cores exemplify this fit-for-purpose approach.
The fastest expansion, however, comes from licensable embedded DSP IP inserted into wider SoC projects. At a 4.02% CAGR, this vector raises the total addressable slice for EDA vendors and soft-IP houses. General-purpose discrete DSPs now orient toward military, aerospace, and laboratory instrumentation niches that value long product lifecycles. FPGA-based hybrids fill customization gaps where mid-volume customers need reconfigurability without ASIC risk.
Complete Report Scope:
- By Core
- Single-core
- Dual-core
- Multi-core
- By Product Type
- General-purpose Stand-alone DSPs
- Application-specific DSP (ASSP/ASIP)
- Embedded DSP IP Cores
- FPGA/SoC-based Hybrid DSPs
- By Architecture
- SIMD (Single Instruction Multiple Data)
- VLIW (Very-long-instruction-word)
- SIMT/Vector DSPs
- MLIW and Novel Heterogeneous Designs
- By Numeric Format
- Fixed-point
- Floating-point
- Mixed/Adaptive Precision
- By End-user Industry
- Communication
- Cellular Infrastructure (4G/5G, Open-RAN)
- Data Center and Cloud Edge
- VoIP and IP Video
- Automotive
- ADAS and Autonomous Driving
- In-vehicle Infotainment
- Consumer Electronics
- Smartphones and Tablets
- Hearables/Wearables
- Smart TVs and STBs
- Industrial
- Motor Control and Drives
- Machine Vision and Robotics
- Smart Grid and Energy
- Aerospace and Defense
- Radar and EW Systems
- Satellite and Space Electronics
- Healthcare
- Medical Imaging
- Patient Monitoring and Diagnostics
- Communication
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- South East Asia
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific generated 48.20% of worldwide revenue in 2025, just under half of the global digital signal processor market. China alone drives more than one quarter of wafer demand as its telecom operators build ultra-dense 5G grids and EV makers load vehicles with radar and infotainment processors. South Korea and Japan add further pull through their advanced memory, sensor, and automotive supply chains. A 3.74% CAGR keeps the region at the top of the growth league, and its installed fab capacity secures a supply advantage when advanced-node allocations tighten.
North America ranks second in both revenue and R&D depth. Silicon Valley start-ups and Austin-based incumbents push leading-edge multicore architectures and neural-DSP hybrids, while US defense projects guarantee a steady market for rad-hard floating-point parts. Federal incentives under the CHIPS and Science Act catalyze domestic fab expansions scheduled to come online by 2027, promising to ease node scarcity for local DSP houses.
Europe completes the triad with robust demand from German and French automakers and a growing cohort of machine-vision integrators. Regional initiatives such as IPCEI Micro-electronics support pilot lines for 12-in wafers, narrowing the production gap with Asia. Meanwhile, South America plus the Middle East & Africa contribute an emerging tail, largely tied to telecom infrastructure roll-outs and satellite broadband gateways that rely on high-throughput DSP-based modems.
- Texas Instruments Inc.
- Analog Devices Inc.
- Qualcomm Technologies Inc.
- Intel Corporation
- NXP Semiconductors N.V.
- STMicroelectronics N.V.
- Infineon Technologies AG
- Renesas Electronics Corp.
- Xilinx Inc. (AMD)
- Broadcom Inc.
- Samsung Electronics Co. Ltd.
- Toshiba Corp.
- Cirrus Logic Inc.
- MediaTek Inc.
- HiSilicon Technologies Co. Ltd.
- Marvell Technology Inc.
- ARM Ltd. (DSP IP)
- CEVA Inc.
- Cadence Design Systems (Tensilica DSP)
- Synopsys Inc. (ARC DSP)
- ON Semiconductor Corp.
- Silicon Labs Inc.
- Realtek Semiconductor Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of 5G Open-RAN Deployments in Asia
- 4.2.2 Automotive ADAS Tier-1 Designs Migrating from MCU to DSP-centric SoCs
- 4.2.3 AI-enhanced Audio and Voice Processing in Hearables and Smart Speakers
- 4.2.4 Adoption of Software-Defined Radar in Aerospace and Defense
- 4.2.5 Edge-based Industrial Machine Vision for Quality 4.0 in Europe
- 4.2.6 Cloud-native Radio Access Networks Requiring High-throughput Baseband DSPs
- 4.3 Market Restraints
- 4.3.1 Supply-chain Volatility in Advanced Node (?7 nm) Foundries
- 4.3.2 Integration Trade-offs Between Fixed- and Floating-Point Precision in Battery-Powered Devices
- 4.3.3 Escalating Royalty Costs for Licensable DSP IP Cores
- 4.3.4 Global Cyber-export Controls Limiting DSP Shipments to Select Regions
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Core
- 5.1.1 Single-core
- 5.1.2 Dual-core
- 5.1.3 Multi-core
- 5.2 By Product Type
- 5.2.1 General-purpose Stand-alone DSPs
- 5.2.2 Application-specific DSP (ASSP/ASIP)
- 5.2.3 Embedded DSP IP Cores
- 5.2.4 FPGA/SoC-based Hybrid DSPs
- 5.3 By Architecture
- 5.3.1 SIMD (Single Instruction Multiple Data)
- 5.3.2 VLIW (Very-long-instruction-word)
- 5.3.3 SIMT/Vector DSPs
- 5.3.4 MLIW and Novel Heterogeneous Designs
- 5.4 By Numeric Format
- 5.4.1 Fixed-point
- 5.4.2 Floating-point
- 5.4.3 Mixed/Adaptive Precision
- 5.5 By End-user Industry
- 5.5.1 Communication
- 5.5.1.1 Cellular Infrastructure (4G/5G, Open-RAN)
- 5.5.1.2 Data Center and Cloud Edge
- 5.5.1.3 VoIP and IP Video
- 5.5.2 Automotive
- 5.5.2.1 ADAS and Autonomous Driving
- 5.5.2.2 In-vehicle Infotainment
- 5.5.3 Consumer Electronics
- 5.5.3.1 Smartphones and Tablets
- 5.5.3.2 Hearables/Wearables
- 5.5.3.3 Smart TVs and STBs
- 5.5.4 Industrial
- 5.5.4.1 Motor Control and Drives
- 5.5.4.2 Machine Vision and Robotics
- 5.5.4.3 Smart Grid and Energy
- 5.5.5 Aerospace and Defense
- 5.5.5.1 Radar and EW Systems
- 5.5.5.2 Satellite and Space Electronics
- 5.5.6 Healthcare
- 5.5.6.1 Medical Imaging
- 5.5.6.2 Patient Monitoring and Diagnostics
- 5.5.1 Communication
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 South Korea
- 5.6.3.4 India
- 5.6.3.5 South East Asia
- 5.6.3.6 Australia
- 5.6.3.7 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Texas Instruments Inc.
- 6.4.2 Analog Devices Inc.
- 6.4.3 Qualcomm Technologies Inc.
- 6.4.4 Intel Corporation
- 6.4.5 NXP Semiconductors N.V.
- 6.4.6 STMicroelectronics N.V.
- 6.4.7 Infineon Technologies AG
- 6.4.8 Renesas Electronics Corp.
- 6.4.9 Xilinx Inc. (AMD)
- 6.4.10 Broadcom Inc.
- 6.4.11 Samsung Electronics Co. Ltd.
- 6.4.12 Toshiba Corp.
- 6.4.13 Cirrus Logic Inc.
- 6.4.14 MediaTek Inc.
- 6.4.15 HiSilicon Technologies Co. Ltd.
- 6.4.16 Marvell Technology Inc.
- 6.4.17 ARM Ltd. (DSP IP)
- 6.4.18 CEVA Inc.
- 6.4.19 Cadence Design Systems (Tensilica DSP)
- 6.4.20 Synopsys Inc. (ARC DSP)
- 6.4.21 ON Semiconductor Corp.
- 6.4.22 Silicon Labs Inc.
- 6.4.23 Realtek Semiconductor Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


