

|
시장보고서
상품코드
2124930
북미의 창고 자동화 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Warehouse Automation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
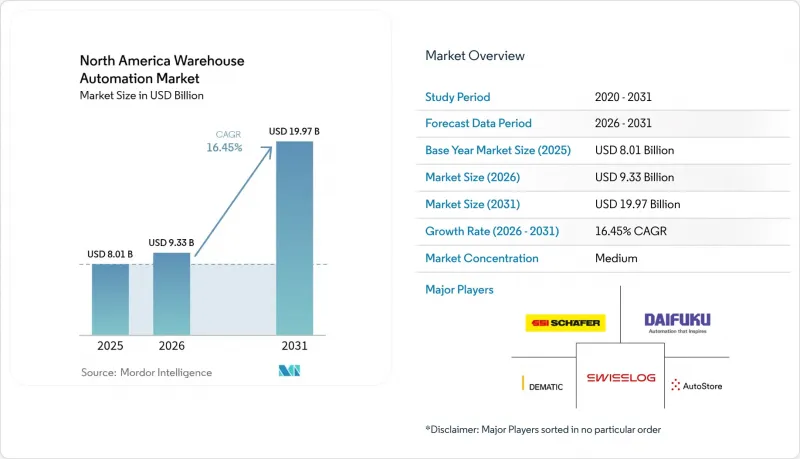
에 의하면, 북미의 창고 자동화 시장 규모는 2025년 80억 1,000만 달러에서 2026년에는 93억 3,000만 달러에 이르고, 2026-2031년 CAGR 16.45%로 성장을 지속하여 2031년에는 199억 7,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 구성 요소(하드웨어, 소프트웨어, 서비스), 기술(자동 창고 시스템 등), 최종 사용자 산업(식품 및 음료, 자동차 등), 기능(보관, 포장·출하, 팔레타이징·디팔레타이징, 분류 등), 지역(미국, 캐나다, 멕시코)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
북미의 창고 자동화 시장 동향 및 인사이트
전자상거래 주문 처리 자동화의 급증
소매업체들은 주문에서 출하까지의 주기를 몇 시간으로 단축하고 있으며, 고속 분류, 굿-투-퍼슨(상품에서 사람으로) 방식의 피킹, 그리고 로봇을 이용한 팔레타이징에 자본을 투자하고 있습니다. 월마트는 2024년에 자율 주행 지게차에 2억 달러를 할당했는데, 이는 매장 판매에 비해 매출 총이익률이 400-600 베이시스 포인트 낮은 온라인 주문으로 인한 이익률 압박을 로봇 공학이 상쇄할 수 있다는 확신의 표현입니다. 아마존의 슈리브포트와 디트로이트 풀필먼트 센터에서는 각각 1,000대 이상의 AMR을 도입하여, 연말 성수기 수요 급증 시 피크 처리 능력을 3배로 확대했습니다. Shopify상의 여러 매장에 서비스를 제공하는 제3자 물류 사업자는 모듈식 자동화를 도입함으로써 비용을 고객사 간에 분산하고, 계약 물량의 변동에 따라 로봇을 재배치할 수 있도록 하고 있습니다. 도심부의 부동산 가격 급등으로 인해 재고는 더 대규모의 지역 허브로 이동하고 있습니다. 그곳에서는 부지 면적을 확대하지 않고도 고밀도로 소프트웨어 주도형 자동화를 확장할 수 있습니다. 당일 배송이 필수 조건이 되는 가운데, 북미의 창고 자동화 시장에서는 주문 처리 속도가 생존을 좌우하는 경쟁 요인으로 자리 잡고 있습니다.
창고 업계의 인력 부족과 임금 인플레이션 심화
2024년 3분기, 창고업 임금은 전년 동기 대비 4.1% 상승했습니다. 한편, 지방 허브의 인력 부족은 여전히 심각하여, 사업자들은 야간 근무에 대한 교대 수당을 지급할 수밖에 없는 상황에 처해 있습니다. 인증된 로봇 기술자의 부족은 인건비를 더욱 끌어올리거나, 사업자들을 특정 벤더에 묶이는 서비스 계약으로 몰아넣고 있습니다. 현재 각 벤더사는 예상치 못한 가동 중지 시간을 줄이기 위해 예측 유지보수 기능을 제어 소프트웨어에 통합하고 있으며, 한 명의 엔지니어가 여러 거점을 담당할 수 있는 원격 진단 기능도 도입하고 있습니다. 연간 임금 상승률이 3% 이상의 상황에서 대량 처리를 수행하는 시설에서는 자율 이동 로봇(AMR)의 투자 회수 기간이 24개월 미만으로 단축되어, 노동 경제와 자동화 투자 계획 간의 구조적 연계가 강화되고 있습니다. 그 결과, 하드웨어와 차량 최적화 소프트웨어를 패키지로 제공하는 AMR 공급업체들은 북미의 창고 자동화 시장에서 유리한 입지를 차지하고 있습니다.
중소기업에 있어 막대한 초기 투자
자동 창고 시스템은 거점당 500만-2,000만 달러의 비용이 소요될 수 있어, 3년마다 갱신되는 경우가 많은 제3자 물류(3PL) 계약과 불일치가 발생합니다. ‘로보틱스 애즈 어 서비스(RaaS)’ 모델에서는 피킹 1회 또는 팔레트 1회 이동마다 요금을 부과함으로써 설비 구입 비용을 운영 비용으로 전환하지만, 그 대신 가동률에 대한 위험은 벤더 측으로 전가됩니다. 표준화된 성과 지표가 없기 때문에 소규모 사업자는 제안 내용을 비교하는 데 어려움을 겪고 있으며, 판매 주기가 장기화되고 있습니다. 이러한 격차로 인해 분산된 네트워크 전체에서 엔지니어링 및 통합 비용을 상각할 수 있는 대형 소매업체나 여러 거점을 보유한 3PL 사업자를 중심으로 자동화 도입이 집중되고 있습니다. 그 결과, 하드웨어 가격 하락에도 불구하고 북미의 창고 자동화 시장에서 중견 규모 사업자의 보급률은 여전히 낮은 수준에 머물러 있습니다.
부문 분석
2025년, 하드웨어는 68.73%의 점유율을 유지하고 있으며, 이는 북미의 창고 자동화 시장 전체에서 자동화 시설의 핵심을 이루는 컨베이어와 ASRS(자동 창고 시스템)가 자본 집약적임을 여실히 보여줍니다. 소프트웨어는 연평균 성장률(CAGR) 16.85%로 성장을 지속하고, 있습니다. 이는 오케스트레이션, 인력 계획, 재고 최적화가 대규모 건설 공사를 진행하지 않고도 처리량을 향상시키는 가장 효과적인 수단이 되고 있기 때문입니다. 영구 라이선스를 대신해 구독 모델이 보급됨에 따라, 사업자는 무선으로 기능 강화를 배포할 수 있게 되어 기능과 하드웨어의 업데이트 주기를 분리할 수 있게 되었습니다.
지속적으로 확대되고 있는 AMR(자율 이동 로봇) 플릿에는 독자적인 플릿 관리 기능이 내장되어 있어, 주문량이 증가하는 구역으로 로봇을 동적으로 재배치함으로써 유휴 시간을 줄이고 자산 활용도를 더욱 높이고 있습니다. 디지털 트윈 모델을 통해 작업자가 현장에 들어가기 전에 랙 재배치나 통로 폭의 미세 조정을 시뮬레이션할 수 있으므로, 프로젝트의 위험을 대폭 줄일 수 있습니다. 설치, 유지보수, 운영 관리와 같은 서비스 수익은 통합업체가 장비 가동 시간이 아닌 ‘시간당 처리 라인 수’를 보장하는 성과 기반 계약으로 전환되고 있어, 공급업체의 인센티브를 사업자의 서비스 수준 목표와 일치시키고 있습니다.
자동 창고 시스템(AS/RS)은 2025년에 매출의 33.15%를 차지할 것으로 예상되며, 부품 및 음료 유통 분야에서 수직 방향의 높은 밀도가 높이 평가받고 있습니다. 한편, AMR(자율 이동 로봇) 및 AGV(자동 유도 차량)는 사업자가 수백 대 단위가 아닌 수십 대 단위로 차량을 확장할 수 있는 유연성을 중시함에 따라 연평균 17.35%의 속도로 보급이 확대되고 있습니다. 예측 가능한 처리량을 다루는 소포 허브에서는 컨베이어나 분류 설비가 여전히 필수적이지만, 개보수 공사 시 ‘라스트 원 미터’ 경로 설정을 위해 AMR과 연동되는 다이버터가 빈번히 도입되고 있습니다.
AutoStore사의 큐브형 보관 시스템은 고밀도 고정 그리드와 그 위에서 작동하는 이동 로봇을 결합하여, 빈 내의 물품을 신속하게 꺼낼 수 있도록 하는 하이브리드 추세를 상징합니다. Locus Robotics는 2024년 북미 전역에서 협업 로봇 도입 대수가 1만 대를 돌파하며, 품목 수가 다양한 전자상거래 분야에서 ‘피킹 1회당 과금 모델’의 유효성을 입증했습니다. 사업자들은 ASRS가 A급 재고를 보관하고, AMR이 B급 및 C급 SKU를 인체공학에 기반한 작업 스테이션까지 운반하는 하이브리드형 시설을 점점 더 많이 도입하고 있으며, 수요 동향이 변화할 때에도 사업 연속성을 확보하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the North America warehouse automation market size is expected to grow from USD 8.01 billion in 2025 to USD 9.33 billion in 2026 and is forecast to reach USD 19.97 billion by 2031 at 16.45% CAGR over 2026-2031.
This report is Segmented by Component (Hardware, Software, Services), Technology (Automated Storage and Retrieval Systems, and More), End-User Industry (Food and Beverage, Automotive, and More), Function (Storage, Packing and Dispatch, Palletizing and Depalletizing, Sortation, and More), and Geography (United States, Canada, Mexico). The Market Forecasts are Provided in Terms of Value (USD).
North America Warehouse Automation Market Trends and Insights
Surge in E-Commerce Fulfillment Automation
Retailers are compressing order-to-ship cycles to hours, pushing capital toward high-speed sortation, goods-to-person picking, and robotic palletizing. Walmart allocated USD 200 million to autonomous forklifts in 2024, evidencing confidence that robotics offset margin pressure from online orders that carry 400-600 basis-point lower gross margins than stores. Amazon's Shreveport and Detroit fulfillment centers each deployed more than 1,000 AMRs to triple peak throughput during holiday surges. Third-party logistics operators serving multiple storefronts on Shopify are embracing modular automation so they can amortize costs across clients and redeploy robots as contract volumes shift. Real-estate premiums in urban cores are steering inventory toward larger regional hubs where dense, software-defined automation scales without expanding footprints. As same-day delivery becomes table stakes, the North America warehouse automation market embeds fulfillment speed as an existential competitive variable.
Rising Labor Shortages and Wage Inflation in Warehousing
Warehouse pay grew 4.1% year-over-year in Q3 2024, while vacancy rates in rural hubs remain acute, forcing operators to pay shift differentials for overnight coverage. Shortfalls in certified robotics technicians further elevate compensation costs or push operators into vendor-locked service contracts. Vendors now embed predictive maintenance into control software to cut unplanned downtime and remote diagnostics that let a single engineer cover multiple sites. When wage growth exceeds 3% annually, autonomous mobile robots show sub-24-month paybacks in high-volume facilities, strengthening the structural ties between labor economics and automation capital plans. Consequently, AMR vendors that package hardware with fleet-optimization software are well positioned inside the North America warehouse automation market.
High Upfront Capital Expenditure for SMEs
Automated storage and retrieval systems can demand USD 5-20 million per site, a misalignment for third-party logistics contracts that often renew every three years. Robotics-as-a-service models convert equipment purchases into operating costs by charging per pick or pallet move, but they also shift utilization risk to the vendor. Lacking standardized performance benchmarks, smaller operators struggle to compare proposals, elongating sales cycles. This disparity concentrates automation adoption among big-box retailers and multi-site 3PLs that can amortize engineering and integration across distributed networks. Consequently, the North America warehouse automation market still shows under-penetration among mid-market operators despite falling hardware prices.
Other drivers and restraints analyzed in the detailed report include:
- US Inflation Reduction Act Incentives for Domestic Automation Hardware
- Integration of AI-Driven Warehouse Orchestration Platforms
- Integration Complexity with Legacy WMS and ERP Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware retained 68.73% share in 2025, underscoring the capital intensity of conveyors and ASRS that anchor automated facilities across the North America warehouse automation market. Software is tracking a 16.85% CAGR because orchestration, labor planning, and inventory optimization are now the fastest levers to raise throughput without heavy construction. As subscription models replace perpetual licenses, operators can roll out feature enhancements over-the-air, decoupling capability from physical refresh cycles.
Expanding fleets of AMRs embed their own fleet-management layers that dynamically reassign robots to zones with rising order depth, cutting idle time and squeezing higher asset utilization. Digital-twin models simulate rack redeployments or aisle-width tweaks before crews step on the floor, slashing project risk. Service revenues installation, maintenance, managed operations are pivoting toward outcome-based contracts where integrators guarantee lines per hour rather than equipment uptime, aligning vendor incentives with the operator's service-level goals.
Automated storage and retrieval systems delivered 33.15% revenue in 2025, prized for vertical density in parts and beverage distribution. Meanwhile, AMRs and AGVs are advancing at 17.35% annually as operators prioritize flexibility that lets fleets scale in increments of tens rather than hundreds. Conveyor and sortation assets remain indispensable for parcel hubs handling predictable volumes, but retrofits frequently embed diverters that interact with AMRs for last-meter routing.
AutoStore's cube-based storage underscores a hybrid trend: dense static grids coupled with mobile robots on top to liberate bin content quickly. Locus Robotics surpassed 10,000 collaborative units across North America in 2024, validating the pay-per-pick model in high-mix e-commerce. Operators increasingly deploy hybrid estates where ASRS stores A-class inventory and AMRs ferry B- and C-class SKUs to ergonomic workstations, ensuring resilience when demand profiles shift.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Technology
- Automated Storage and Retrieval Systems
- Autonomous Mobile Robots and AGVs
- Conveyor and Sortation Systems
- Picking and Packing Automation
- Warehouse Management and Execution Software
- By End-User Industry
- E-Commerce and Retailers
- Third-Party Logistics
- Food and Beverage
- Automotive
- Healthcare and Pharmaceuticals
- Electronics and Electrical
- By Function
- Storage
- Order Picking
- Packing and Dispatch
- Palletizing and Depalletizing
- Sortation
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Daifuku Co., Ltd.
- SSI Schaefer AG
- Dematic Corp.
- Swisslog Holding AG
- AutoStore Holdings Ltd.
- TGW Logistics Group GmbH
- Honeywell Intelligrated Inc.
- Bastian Solutions LLC
- MHS Holdings, LLC
- Murata Machinery, Ltd.
- KNAPP AG
- Kardex Holding AG
- Vanderlande Industries B.V.
- Geekplus Technology Co., Ltd.
- Locus Robotics Corp.
- Fetch Robotics, Inc. (Zebra Technologies Corp.)
- GreyOrange Pte. Ltd.
- Seegrid Corporation
- Ocado Group plc
- Exotec SAS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in E-Commerce Fulfillment Automation
- 4.2.2 Rising Labor Shortages and Wage Inflation in Warehousing
- 4.2.3 US Inflation Reduction Act Incentives for Domestic Automation Hardware
- 4.2.4 Integration of AI-Driven Warehouse Orchestration Platforms
- 4.2.5 Demand for Cold-Chain Compliance and Temperature-Controlled Automation
- 4.2.6 2025 US Tariffs Accelerating Nearshoring of Automation Supply Chains
- 4.3 Market Restraints
- 4.3.1 High Upfront Capital Expenditure for SMEs
- 4.3.2 Integration Complexity with Legacy WMS and ERP Systems
- 4.3.3 Shortage of Skilled Robotics Technicians in Rural Distribution Hubs
- 4.3.4 Cybersecurity Risks to Connected Warehouse Control Systems
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Technology
- 5.2.1 Automated Storage and Retrieval Systems
- 5.2.2 Autonomous Mobile Robots and AGVs
- 5.2.3 Conveyor and Sortation Systems
- 5.2.4 Picking and Packing Automation
- 5.2.5 Warehouse Management and Execution Software
- 5.3 By End-User Industry
- 5.3.1 E-Commerce and Retailers
- 5.3.2 Third-Party Logistics
- 5.3.3 Food and Beverage
- 5.3.4 Automotive
- 5.3.5 Healthcare and Pharmaceuticals
- 5.3.6 Electronics and Electrical
- 5.4 By Function
- 5.4.1 Storage
- 5.4.2 Order Picking
- 5.4.3 Packing and Dispatch
- 5.4.4 Palletizing and Depalletizing
- 5.4.5 Sortation
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Daifuku Co., Ltd.
- 6.4.2 SSI Schaefer AG
- 6.4.3 Dematic Corp.
- 6.4.4 Swisslog Holding AG
- 6.4.5 AutoStore Holdings Ltd.
- 6.4.6 TGW Logistics Group GmbH
- 6.4.7 Honeywell Intelligrated Inc.
- 6.4.8 Bastian Solutions LLC
- 6.4.9 MHS Holdings, LLC
- 6.4.10 Murata Machinery, Ltd.
- 6.4.11 KNAPP AG
- 6.4.12 Kardex Holding AG
- 6.4.13 Vanderlande Industries B.V.
- 6.4.14 Geekplus Technology Co., Ltd.
- 6.4.15 Locus Robotics Corp.
- 6.4.16 Fetch Robotics, Inc. (Zebra Technologies Corp.)
- 6.4.17 GreyOrange Pte. Ltd.
- 6.4.18 Seegrid Corporation
- 6.4.19 Ocado Group plc
- 6.4.20 Exotec SAS
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


