

|
시장보고서
상품코드
2124957
미국의 엔지니어링 서비스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Engineering Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 미국의 엔지니어링 서비스 시장 규모는 2025년에 3,874억 2,000만 달러로 평가되었습니다. 2026년 4,096억 2,000만 달러에서 2031년까지 5,333억 3,000만 달러에 이를 것으로 추정되고 2026-2031년까지 예측 기간 CAGR은 5.42%를 나타낼 전망입니다.
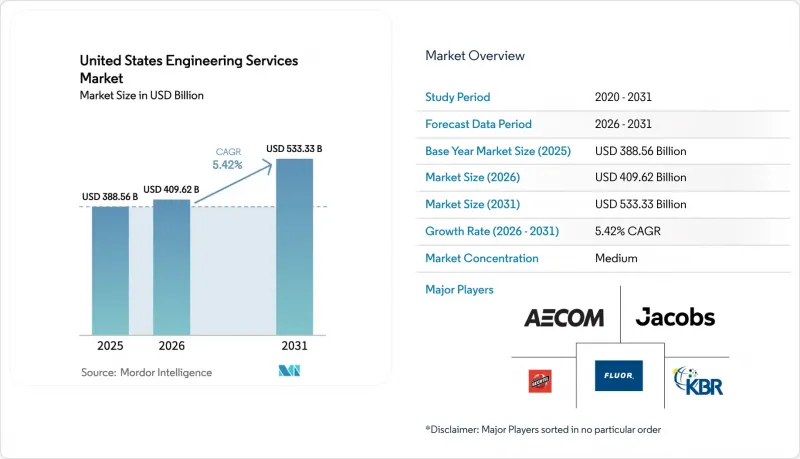
본 보고서는 용도별(토목, 기계, 전기, 환경, 화학, 구조, 소프트웨어·시스템), 서비스 유형별(컨설팅·설계, 기타), 최종 사용자 산업별(건설 및 인프라, 석유 및 가스, 기타), 참여 모델별(사내, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
미국의 엔지니어링 서비스 시장 동향 및 인사이트
IIJA에 따른 연방 인프라 자금
인프라 투자 및 고용법(IIJA)에 따라 2026년까지 5,500억 달러의 신규 예산이 확보되었습니다. 이 예산의 내역은 도로 및 교량에 1,100억 달러, 철도에 660억 달러, 광대역에 650억 달러로 구성되어 있습니다. 각 주가 브렌트 스펜스 교량 재건축이나 게이트웨이 터널과 같은 주요 프로젝트를 조달 단계로 진행하는 가운데, 설계 회사는 초기 단계의 계획 및 시공 관리에 대한 보수를 확보하고 있습니다. ‘바이 아메리카(Buy American)’ 조항에 따라 엔지니어들이 국내 철강 및 시멘트 공급망을 검증해야 할 필요가 생겨, 설계 일정이 최대 1년 연장되고 청구 가능한 조정 작업 시간이 확대되고 있습니다. 보증금 요건을 충족하기 위해 중소규모 및 대규모 EPCM 기업 간의 합작 투자가 급증하고 있으며, 이로 인해 총 보수는 분산되는 한편, 시장 진출기업은 확대되고 있습니다. 중기적으로는 안정적인 예산 배분과 효율화된 보조금 지급으로 인해 토목·구조 부문의 수주 잔고는 견조한 추세를 보일 전망입니다.
반도체 팹 및 배터리 기가팩토리 건설 가속화
‘CHIPS·과학법’에 따른 527억 달러 규모의 인센티브 패키지는 2024년부터 2026년에 걸쳐 23곳의 팹 건설 발표를 뒷받침했습니다. 각 시설에는 방진 기초, 초순수 순환 시스템, 공정 배기 시스템이 필요하며, 기계·전기·화학 엔지니어가 담당할 수 있는 업무 범위가 확대되고 있습니다. 조지아주, 테네시주, 미시간주의 배터리 기가팩토리 역시 클린룸 및 고전압 변전소 설계 수요를 견인하고 있습니다. 각 기업은 설비 연결을 표준화하는 모듈식 템플릿을 도입하고 있지만, 현장 고유의 내진 및 환경적 제약으로 인해 맞춤형 엔지니어링이 지속적으로 요구되고 있으며, 이로 인해 높은 보수율이 유지되고 있습니다.
숙련된 인력의 만성적인 부족으로 인한 청구 단가 상승
면허를 취득한 엔지니어의 40%가 55세 이상이며, ABET(미국 공학기술인증위원회) 등록자 수는 2022년부터 2025년에 걸쳐 연평균 3% 감소했습니다. 각 기업은 신입 사원의 초임 연봉을 연간 8-12% 인상하고 있어, 고정 가격 계약의 이익률을 압박하고 있습니다. 복잡도가 낮은 도면 작성 업무를 인도나 필리핀에 외주화하더라도, 미국 내 전문가의 서명이 여전히 의무화되어 있어 인력 부족의 압박을 일부만 완화할 수 있습니다. 규격에 부합하는 레이아웃을 자동으로 생성하는 자동화 도구가 해결책이 될 수 있지만, 대부분의 규제 당국은 창고나 경공업 시설 유형에만 그 사용을 허용하고 있어 단기적인 영향은 제한적입니다.
부문별 분석
2025년 미국의 엔지니어링 서비스 시장 규모 중 토목 공학이 34.59%를 차지했습니다. 이는 IIJA(인프라 투자 및 고용법) 자금을 통한 교량 개보수, 고속도로 확장, 빗물 배수 시스템 개선이 주도한 결과입니다. 유틸리티자가 배전망 현대화를 추진하고, 제조업체가 산업용 IoT 플랫폼을 활용해 공장을 개보수함에 따라, 소프트웨어 및 시스템 엔지니어링은 2031년까지 연평균 성장률(CAGR) 5.89%를 기록할 전망입니다. 기계 공학에 대한 수요는 50kW의 랙 밀도를 지원하는 데이터센터의 수냉식 설계가 보급됨에 따라 증가하고 있으며, 한편 전기 공학의 업무 범위는 송전망의 신뢰성을 뒷받침하는 위상 측정 장치 및 자동 피더 스위치의 도입으로 확대되고 있습니다. 환경 공학 분야는 PFAS(퍼플루오로알킬 물질) 정화 및 습지대 대체 조치와 관련된 수주를 지속적으로 확보하고 있으며, 구조 공학 전문가들은 서부 해안 지역의 내진 보강 규제의 혜택을 받고 있습니다.
소프트웨어 및 시스템 솔루션에 대한 수요 증가는 특히 중요 인프라 분야에서 소유주들이 운영 기술(OT)의 사이버 위협을 우려하고 있음을 반영합니다. 현재 계약에는 소프트웨어 코딩과 OT 보안 강화가 세트로 포함되어 있어, 제로 트러스트 아키텍처에 정통한 기업들에게 안정적이고 지속적인 수익원이 되고 있습니다. 토목 공학은 IIJA의 예산 배분이 지속되는 한 적어도 2028년까지는 주도적인 위치를 유지할 전망이지만, 의회의 육상 운송 관련 승인이 기존 수준을 상회하는 형태로 갱신되지 않는다면 성장이 둔화될 가능성이 있습니다. 전반적으로, 용도의 다양성이 미국의 엔지니어링 서비스 시장을 개별 부문의 경기 변동 영향으로부터 보호하고 있습니다.
컨설팅 및 설계 서비스는 2025년 미국의 엔지니어링 서비스 시장 점유율의 38.11%를 차지했습니다. 이는 사업주가 자본을 투입하기 전에 범위와 비용을 확정하기 위한 상세한 초기 단계 패키지가 필요했기 때문입니다. 자동화 및 디지털 엔지니어링은 2031년까지 연평균 성장률(CAGR) 5.67%를 나타낼 것으로 예측됩니다. 이는 BIM 레벨 2의 의무화 및 시운전 주기를 단축하는 디지털 트윈의 도입을 반영한 것입니다. 공정 및 플랜트 엔지니어링은 반도체 및 배터리 공장 수요 증가의 흐름에 힘입어, 설비 발주에 앞서 배관·계장 도면 및 위험 구역 분류가 요구되고 있습니다. 제품 엔지니어링은 여전히 항공우주 및 방위 부문에 집중되어 있으며, 이 부문에서는 제조 전에 유한요소법이나 열분석을 이용하여 설계 검증이 이루어지고 있습니다.
노후화된 교량이나 변전소에서 상태 평가 및 수명 주기 모델링이 필요함에 따라 자산 관리의 업무 범위는 확대되고 있습니다. 건설 관리 수요는 견조한 추세를 보이고 있으며, 발주자는 프로젝트의 복잡성에 따라 ‘위험을 부담하는 건설 관리자(CMAR)’ 방식과 ‘설계·시공 일괄 방식(DB)’ 중 하나를 선택하고 있습니다. 미국의 자동화 서비스 관련 엔지니어링 서비스 시장 규모는 충돌 감지 및 4D 스케줄링 도구가 주류를 이루면서 확대될 전망입니다. 이를 통해 전미종합건설업협회(AGC)가 건설 예산의 5-10%로 추정하는 낭비가 절감될 것입니다. 이러한 도구를 고정 요금제 제안서에 포함시키는 기업들은 기존에는 발주자가 부담하던 기술 비용을 효과적으로 수익화함으로써 견실한 이익률을 유지하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the United States engineering services market size was valued at USD 387.42 billion in 2025 and estimated to grow from USD 409.62 billion in 2026 to reach USD 533.33 billion by 2031, at a CAGR of 5.42% during the forecast period 2026-2031.
This report is Segmented by Application (Civil, Mechanical, Electrical, Environmental, Chemical, Structural, and Software and Systems), Service Type (Consulting and Design, and More), End-User Industry (Construction and Infrastructure, Oil and Gas, and More), Engagement Model (In-House, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
United States Engineering Services Market Trends and Insights
Federal Infrastructure Funding Under IIJA
The Infrastructure Investment and Jobs Act unlocked USD 550 billion in fresh allocations through 2026, including USD 110 billion for roads and bridges, USD 66 billion for rail, and USD 65 billion for broadband. Design firms are securing front-end planning and construction-management fees as states move stalwart projects like the Brent Spence Bridge replacement and the Gateway Tunnel into procurement. Buy-America clauses are stretching design schedules by up to a year as engineers validate domestic steel and cement supply chains, expanding billable coordination hours. Joint ventures between small and large EPCMs are proliferating to meet bonding thresholds, fragmenting fee pools yet widening participation. Over the medium term, consistent appropriations and streamlined grant disbursement will keep civil and structural backlogs robust.
Accelerating Semiconductor Fabs and Battery Gigafactory Construction
The CHIPS and Science Act's USD 52.7 billion incentive package has catalysed 23 announced fabs between 2024 and 2026. Each facility demands vibration-isolated foundations, ultra-pure water loops, and process exhaust systems, enlarging the addressable scope for mechanical, electrical, and chemical engineers. Battery gigafactories in Georgia, Tennessee, and Michigan are likewise driving cleanroom and high-voltage substation design mandates. Firms are deploying modular templates that standardize tool hook-ups, yet site-specific seismic and environmental constraints preserve the need for bespoke engineering, sustaining premium fee rates.
Persistent Skilled-Labor Shortages Inflating Billing Rates
Forty percent of licensed engineers are over 55, and ABET enrolments fell 3% annually from 2022-2025. Firms are raising entry-level pay by 8-12% a year, compressing margins on fixed-price contracts. Outsourcing low-complexity drafting to India and the Philippines offsets only a portion of labour pressure, as U.S.-based professional seals remain mandatory. Automation tools that autogenerate code-compliant layouts promise relief, yet most regulators accept them only for warehousing and light-industrial typologies, limiting near-term impact.
Other drivers and restraints analyzed in the detailed report include:
- AI-Enabled Digital Twin Adoption Reducing Re-work
- Record Utility-Scale Renewable Interconnection Backlog
- Lengthy NEPA and State Environmental Reviews
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Civil engineering accounted for 34.59% of the United States engineering services market size in 2025, fuelled by bridge rehabilitation, highway widening, and storm-water upgrades funded under the IIJA. Software and systems engineering is on track for a 5.89% CAGR through 2031 as utilities modernize distribution grids and manufacturers retrofit plants with industrial IoT platforms. Mechanical engineering demand is climbing in parallel with data-center liquid-cooling designs handling 50 kW rack densities, while electrical engineering scopes are expanding with phasor measurement units and automated feeder switches that underpin grid reliability. Environmental engineering continues to capture mandates for PFAS remediation and wetland mitigation, whereas structural specialists gain from seismic-retrofit rules on the West Coast.
The preference for software and systems solutions mirrors owner concern over operational-technology cyber threats, especially across critical infrastructure. Contracts now bundle software coding with OT hardening, creating steady retainer revenue for firms versed in zero-trust architectures. Civil engineering will stay dominant until at least 2028 while IIJA allocations flow, yet growth could taper without fresh congressional surface-transport authorizations at elevated levels. Overall, application diversity cushions the United States engineering services market from cyclical swings in any single discipline.
Consulting and design services captured 38.11% of the 2025 United States engineering services market share as owners required detailed front-end packages to pin down scope and cost before mobilizing capital. Automation and digital engineering is projected to post a 5.67% CAGR through 2031, reflecting BIM Level 2 mandates and digital-twin adoption that compress commissioning cycles. Process and plant engineering rides the semiconductor and battery-plant wave, demanding piping and instrumentation diagrams and hazardous-area classifications ahead of equipment orders. Product engineering remains concentrated within aerospace and defense, where finite-element and thermal modelling validate designs prior to fabrication.
Asset-management scopes are rising as aging bridges and substations need condition assessments and lifecycle modelling. Construction-management demand stays steady, with owners choosing between construction-manager-at-risk and design-build depending on complexity. The United States engineering services market size tied to automation services will advance as clash-detection and 4D scheduling tools become mainstream, reducing the waste that the Associated General Contractors of America pegs at 5-10% of construction budgets. Firms embedding such tools within fixed-fee proposals effectively monetize technology previously borne by owners, sustaining margin resilience.
Complete Report Scope:
- By Application
- Civil
- Mechanical
- Electrical
- Environmental
- Chemical
- Structural
- Software and Systems
- By Service Type
- Consulting and Design
- Process and Plant Engineering
- Product Engineering and Prototyping
- Automation and Digital Engineering
- Asset Management and O&M
- Construction Management
- By End-user Industry
- Construction and Infrastructure
- Oil and Gas
- Manufacturing
- Utilities (Power, Water)
- Transportation (Rail, Airports, Ports)
- Telecommunications and Data Centers
- Healthcare Facilities
- Defense and Aerospace
- Renewable Energy Projects
- By Engagement Model
- In-house
- Outsourced, EPCM
- Public-Private Partnership (PPP) Frameworks
- By Geography
- Northeast
- Midwest
- South
- West
List of Companies Covered in this Report:
- AECOM
- Jacobs Engineering Group Inc.
- Bechtel Corporation
- Fluor Corporation
- KBR, Inc.
- HDR, Inc.
- Terracon Consultants, Inc.
- Black & Veatch Holding Company
- Jensen Hughes, Inc.
- ECS Limited
- WSP USA Inc.
- Tetra Tech, Inc.
- STV Group, Inc.
- Arup US, Inc.
- Gannett Fleming, Inc.
- Burns & McDonnell Engineering Company, Inc.
- HNTB Corporation
- Parsons Corporation
- Louis Berger U.S., Inc.
- AtkinsRealis USA Inc.
- Ghafari Associates, LLC
- Kimley-Horn and Associates, Inc.
- Dewberry Engineers Inc.
- Michael Baker International, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Federal Infrastructure Funding under IIJA
- 4.2.2 Accelerating Semiconductor Fabs and Battery Gigafactory Construction
- 4.2.3 Near-shoring Advanced Manufacturing Lines
- 4.2.4 Record Utility-Scale Renewable Interconnection Backlog
- 4.2.5 Defense Modernization Programs Requiring Specialized Engineering
- 4.2.6 AI-Enabled Digital Twin Adoption Reducing Re-work
- 4.2.7 Climate-Resilience Retrofits of Aging Infrastructure
- 4.2.8 Stricter Building Energy Codes Driving MEP Redesigns
- 4.3 Market Restraints
- 4.3.1 Volatile Steel and Concrete Input-Cost Pass-Through Risk
- 4.3.2 Lengthy NEPA and State Environmental Reviews
- 4.3.3 Persistent Skilled-Labor Shortages Inflating Billing Rates
- 4.3.4 State-by-State Engineering Licensing Variances
- 4.3.5 Rising Professional Liability Insurance Premiums
- 4.4 Industry Value-Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory and Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Comparative Analysis, In-house vs Outsourced Engineering
- 4.9 Vendor Service Innovation Trends
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Civil
- 5.1.2 Mechanical
- 5.1.3 Electrical
- 5.1.4 Environmental
- 5.1.5 Chemical
- 5.1.6 Structural
- 5.1.7 Software and Systems
- 5.2 By Service Type
- 5.2.1 Consulting and Design
- 5.2.2 Process and Plant Engineering
- 5.2.3 Product Engineering and Prototyping
- 5.2.4 Automation and Digital Engineering
- 5.2.5 Asset Management and O&M
- 5.2.6 Construction Management
- 5.3 By End-user Industry
- 5.3.1 Construction and Infrastructure
- 5.3.2 Oil and Gas
- 5.3.3 Manufacturing
- 5.3.4 Utilities (Power, Water)
- 5.3.5 Transportation (Rail, Airports, Ports)
- 5.3.6 Telecommunications and Data Centers
- 5.3.7 Healthcare Facilities
- 5.3.8 Defense and Aerospace
- 5.3.9 Renewable Energy Projects
- 5.4 By Engagement Model
- 5.4.1 In-house
- 5.4.2 Outsourced, EPCM
- 5.4.3 Public-Private Partnership (PPP) Frameworks
- 5.5 By Geography
- 5.5.1 Northeast
- 5.5.2 Midwest
- 5.5.3 South
- 5.5.4 West
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 AECOM
- 6.4.2 Jacobs Engineering Group Inc.
- 6.4.3 Bechtel Corporation
- 6.4.4 Fluor Corporation
- 6.4.5 KBR, Inc.
- 6.4.6 HDR, Inc.
- 6.4.7 Terracon Consultants, Inc.
- 6.4.8 Black & Veatch Holding Company
- 6.4.9 Jensen Hughes, Inc.
- 6.4.10 ECS Limited
- 6.4.11 WSP USA Inc.
- 6.4.12 Tetra Tech, Inc.
- 6.4.13 STV Group, Inc.
- 6.4.14 Arup US, Inc.
- 6.4.15 Gannett Fleming, Inc.
- 6.4.16 Burns & McDonnell Engineering Company, Inc.
- 6.4.17 HNTB Corporation
- 6.4.18 Parsons Corporation
- 6.4.19 Louis Berger U.S., Inc.
- 6.4.20 AtkinsRealis USA Inc.
- 6.4.21 Ghafari Associates, LLC
- 6.4.22 Kimley-Horn and Associates, Inc.
- 6.4.23 Dewberry Engineers Inc.
- 6.4.24 Michael Baker International, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


