

|
시장보고서
상품코드
2124958
능동적 상처 관리 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Active Wound Care - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
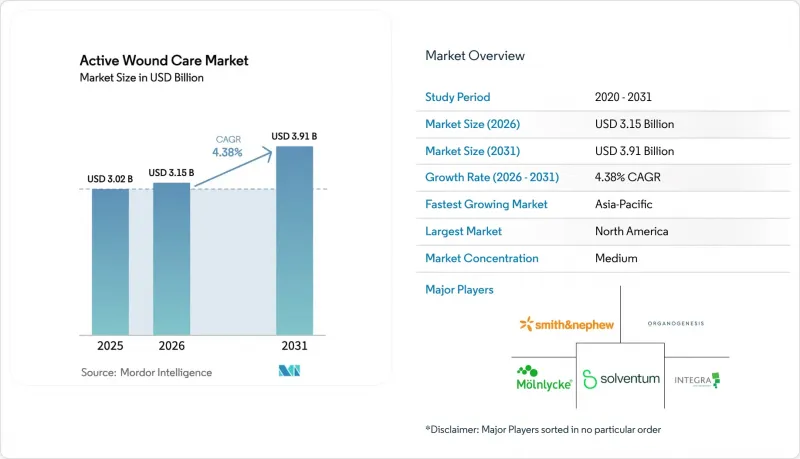
에 의하면, 능동적 상처 관리 시장 규모는 2025년 30억 2,000만 달러에서 2026년에는 31억 5,000만 달러에 이르고, 2026-2031년 CAGR 4.38%로 성장을 지속하여 2031년에는 39억 1,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 제품별(생체재료, 피부 대체재, 성장 인자), 최종 사용자별(병원, 전문 상처 클리닉, 재택치료, 기타), 용도별(만성 상처, 급성 상처) 및 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
전 세계 능동적 상처 관리 시장 동향 및 인사이트
만성 상처(당뇨병, 비만) 유병률 증가
세계적인 당뇨병의 확산은 상처 관리 수요 패턴을 근본적으로 변화시키고 있으며, 당뇨병성 족부 궤양은 연간 130억 달러의 치료 비용을 초래하고 있지만, 기존의 치료법으로는 이를 효과적으로 해결하지 못하고 있습니다. 중국 전역에 걸쳐 상처 치료 센터가 구축되고 있는 것은 복잡한 궤양 사례가 증가하는 가운데 의료 시스템이 대응 능력을 확대하고 있음을 보여줍니다. 대사성 질환과 인구 고령화가 겹치면서, 2030년까지 만성 상처가 활성 상처 치료 시장의 주요 수익원으로 남아 있을 것으로 확실시되고 있습니다.
생체공학을 활용한 대체 재료 및 성장 인자 분야의 기술 혁신
2024년 FDA가 승인한 유전자 기반 피부 대체재 ‘Zevaskyn’은 열성 영양실조성 수포성 표피 수포증 병변에서 81%의 폐쇄율을 달성하여, 세포 재프로그래밍 기술의 신속한 임상 적용이 입증되었습니다. 새롭게 등장한 3D 바이오 프린팅 기술을 통해 혈관화 구조를 포함한 환자 맞춤형 이식편 제작이 가능해지면서, 이식편 부착 불량이라는 오랜 과제가 해결되고 있습니다. 이러한 진보에 힘입어, 활발한 상처 관리 시장은 범용적인 공급품에서 개별 상처의 미세 환경에 맞추어 치료를 최적화할 수 있는 정밀하고 생물학적으로 활성적인 플랫폼으로 전환되고 있습니다.
신흥 시장에서 제품의 높은 비용과 불균일한 보험 환급
고급 매트릭스나 성장 인자 제제는 거즈에 비해 몇 배나 높은 가격으로 책정되어 있어, 공적 의료 제도가 기본적인 치료만 보장하는 지역에서 보급을 저해하고 있습니다. 중국과 인도에 위치한 현지 제조 거점을 통해 비용은 낮아지고 있지만, 보험 환급은 임상 지침을 따라가지 못하고 있어 환자들은 본인 부담금을 지불할 수밖에 없는 실정입니다. 콜드체인을 통한 유통 및 훈련을 받은 적용 전문가의 부족과 같은 인프라 제약으로 인해, 일류 병원 이외의 장소에서 활성 제품의 보급이 더욱 제한되고 있어, 저·중소득 국가에서 활성 상처 관리 시장의 잠재력을 충분히 발휘하지 못하는 상황입니다.
부문 분석
2025년에는 생체 재료가 매출의 44.86%를 차지하며, 모든 상처 원인에 대한 1차 치료법으로서의 입지를 확고히 했습니다. 기능이 강화된 하이드로겔, 알지네이트 및 폼 복합재는 경쟁력 있는 가격대에서 수분 균형과 삼출액 조절을 실현하여, 활성 상처 치료 시장에서 폭넓은 채택을 보장하고 있습니다. 피부 대체재(생물 유래, 생체 합성 및 합성)는 차세대 매트릭스에 생존 가능한 세포와 성장 인자가 통합됨에 따라 연평균 성장률(CAGR) 4.78%를 나타낼 것으로 예측되며, 시장 규모가 급속히 확대되고 있습니다. 중증 화상에 대한 ‘NexoBrid’ 등의 승인이 임상적 유효성을 입증함에 따라, 능동적 상처 관리 시장의 성장이 가속화되고 있습니다.
각 제조업체들은 폼 및 하이드로콜로이드 드레싱에 마이크로 센서와 무선 모듈을 통합하는 움직임을 강화하고 있으며, 수동적인 붕대를 온보드 진단 기능을 갖춘 IoT 지원 치료용 제품으로 변모시키고 있습니다. 식물이나 어류 콜라겐에서 유래한 합성 고분자는 인간 유래 세포외 기질과 동등한 성능을 발휘하여, 공급 제약과 윤리적 우려를 완화하고 있습니다. 이러한 제품의 다양화는 조달 장애에 대한 능동적 상처 관리 시장의 회복력을 뒷받침하고 있습니다.
지역별 분석
북미는 유리한 보험 환급 제도와 인간을 대상으로 한 1상 임상시험을 주도하는 학술 의료 센터가 밀집해 있어, 2025년에는 전 세계 매출의 41.30%를 차지했습니다. 진행 중인 메디케어 어드밴티지(Medicare Advantage)의 확대로 인해, 정량화 가능한 치료 성과 향상을 보여주는 디지털 치료법 조합에 대한 민간 부문의 투자가 가속화되고 있으며, 이는 능동적 상처 관리 시장에서 해당 지역의 선도적 지위를 강화하고 있습니다.
아시아태평양은 인프라 확충과 만성 질환 관리 프로그램에 대한 정부의 지원에 힘입어 2031년까지 연평균 성장률(CAGR) 5.92%라는 가장 높은 성장 궤도를 기록하고 있습니다. 중국에서는 생명공학 스타트업에 대한 혁신 보조금의 지속적인 배분이 기술과 역량의 급속한 확충을 뒷받침하고 있습니다. 인도 및 인도네시아에서는 공공 보험의 확대에 따라 당뇨병성 궤양에 대한 생리활성 대체 요법의 보험 적용이 시작되면서, 능동적 상처 관리 시장에 새로운 환자층이 개척되고 있습니다.
유럽은 지속가능성을 우선시하는 엄격한 의료기기 규제에 의해 형성되어, 꾸준하면서도 기회가 풍부한 환경을 보여주고 있습니다. 환경 지침 및 병원의 친환경 조달 의무를 배경으로, 생분해성 드레싱과 식물 유래 콜라겐에 대한 수요가 증가하고 있습니다. 중동 및 아프리카 및 남미는 전체 시장 점유율은 작지만, 각각 특정 걸프협력회의(GCC) 회원국과 브라질에서 3차 의료기관이 OECD의 상처 관리 프로토콜과 동등한 수준을 목표로 하는 움직임에 힘입어 두 자릿수 성장 영역으로 전환되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the active wound care market size is expected to grow from USD 3.02 billion in 2025 to USD 3.15 billion in 2026 and is forecast to reach USD 3.91 billion by 2031 at 4.38% CAGR over 2026-2031.
This report is Segmented by Product (Biomaterials, Skin Substitutes, Growth Factors), End User (Hospitals, Specialty Wound Clinics, Home Healthcare, Others), Application (Chronic Wounds, Acute Wounds), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Active Wound Care Market Trends and Insights
Rising Prevalence of Chronic Wounds (Diabetes, Obesity)
The global diabetes epidemic is fundamentally reshaping wound care demand patterns, with diabetic foot ulcers representing a USD 13 billion annual treatment burden that traditional therapies fail to address effectively. China's nationwide push of wound centers illustrates how health systems are scaling capacity to manage a mounting caseload of complex ulcers. The intersection of metabolic disorders with population aging ensures that chronic wounds stay the dominant revenue driver in the active wound care market through 2030.
Technological Innovations in Bioengineered Substitutes and Growth Factors
The 2024 FDA approval of Zevaskyn, a gene-based skin substitute that achieved an 81% closure rate in recessive dystrophic epidermolysis bullosa lesions, confirms rapid clinical translation of cellular reprogramming techniques. Emerging 3D-bioprinting processes enable patient-specific grafts containing vascularized constructs, addressing the long-standing hurdle of poor graft integration. These advances reposition the active wound care market from commodity supplies to precision, biologically active platforms capable of tailoring therapy to individual wound microenvironments.
High Product Costs and Uneven Reimbursement in Emerging Markets
Advanced matrices and growth-factor formulations carry price tags many multiples higher than gauze, impeding penetration where public systems cover only basic care. Localized manufacturing hubs in China and India bring down costs, yet reimbursement lags behind clinical guidelines, forcing patients to self-pay. Infrastructure limitations, including cold-chain distribution and trained application specialists, further restrict active product uptake outside Tier-1 hospitals, curbing the full potential of the active wound care market in low- and middle-income economies.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Surgical and Trauma Procedures
- Expanding Reimbursement for Cellular/Tissue-Based Products
- Stringent Biologics Approval Pathways
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Biomaterials contributed 44.86% of revenue in 2025, affirming their role as first-line therapy across wound etiologies. Enhanced hydrogels, alginates, and foam composites offer moisture balance and exudate control at competitive price points, ensuring broad adoption in the active wound care market. Skin substitutes-biological, biosynthetic, and synthetic-are scaling faster, with a 4.78% CAGR forecast as next-generation matrices integrate viable cells and growth factors. The active wound care market growth propelled by approvals such as NexoBrid for severe burns that validate clinical efficacy.
Manufacturers increasingly embed micro-sensors and wireless modules into foam and hydrocolloid dressings, transforming a passive bandage into an IoT-enabled therapeutic with on-board diagnostics. Synthetic polymers derived from plant or fish collagen provide performance parity to human-derived extracellular matrices, mitigating supply constraints and ethical concerns. This product diversification supports resilience in the active wound care market against sourcing disruptions.
Complete Report Scope:
- By Product
- Biomaterials
- Skin Substitutes
- Biological Skin Substitutes
- Synthetic and Biosynthetic Skin Substitutes
- Growth Factors
- By End User
- Hospitals
- Specialty Wound Clinics
- Home Healthcare
- Others
- By Application
- Chronic Wounds
- Acute Wounds
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 41.30% of global revenue in 2025 thanks to favorable reimbursement and a dense cluster of academic medical centers spearheading first-in-human trials. Ongoing Medicare Advantage expansion is accelerating private-sector investment in digital-therapeutic pairings that display quantifiable outcome gains, reinforcing regional leadership in the active wound care market.
Asia-Pacific registers the highest trajectory at 5.92% CAGR through 2031, galvanized by infrastructure upgrades and government backing of chronic disease management programs. China's continued allocation of innovation grants for biotech startups underpins a rapid skills and capacity build-out. In India and Indonesia, public insurance expansions are beginning to reimburse bioactive substitutes for diabetic ulcers, unlocking new patient cohorts for the active wound care market.
Europe presents a steady yet opportunity-rich environment shaped by stringent medical-device regulations that prioritize sustainability. Demand for biodegradable dressings and plant-based collagen is growing, driven by environmental directives and hospital green-procurement mandates. Middle East & Africa and South America contribute a smaller collective share but are moving into double-digit growth zones in select Gulf Cooperation Council (GCC) states and Brazil, respectively, as tertiary hospitals seek parity with OECD wound-care protocols.
- Smiths Group
- Solventum
- Molnlycke Health Care
- Organogenesis
- Integra LifeSciences Holdings Corp.
- MiMedx Group Inc.
- Tissue Regenix
- Stryker
- ConvaTec Group plc
- Baxter
- Coloplast
- Johnson & Johnson
- Medtronic
- Axio Biosolutions
- Fibroheal Woundcare Pvt. Ltd.
- Human BioSciences
- BSN medical (Essity)
- Aroa Biosurgery Ltd.
- Regenesis Biomedical
- Gunze Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Chronic Wounds (Diabetes, Obesity)
- 4.2.2 Surge In Surgical and Trauma Procedures
- 4.2.3 Technological Innovations in Bioengineered Substitutes and Growth Factors
- 4.2.4 Expanding Reimbursement for Cellular/Tissue-Based Products
- 4.2.5 Smart Sensor-Embedded Active Dressings Adoption
- 4.2.6 Military and Space-Medicine Funded Regenerative R&D
- 4.3 Market Restraints
- 4.3.1 High Product Costs and Uneven Reimbursement in EMs
- 4.3.2 Stringent Biologics Approval Pathways
- 4.3.3 Supply-Chain Limits for Human/Animal ECM Sourcing
- 4.3.4 Rising Antimicrobial Resistance Impacting Bioactive Dressings
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product
- 5.1.1 Biomaterials
- 5.1.2 Skin Substitutes
- 5.1.2.1 Biological Skin Substitutes
- 5.1.2.2 Synthetic and Biosynthetic Skin Substitutes
- 5.1.3 Growth Factors
- 5.2 By End User
- 5.2.1 Hospitals
- 5.2.2 Specialty Wound Clinics
- 5.2.3 Home Healthcare
- 5.2.4 Others
- 5.3 By Application
- 5.3.1 Chronic Wounds
- 5.3.2 Acute Wounds
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Smith & Nephew plc
- 6.3.2 Solventum
- 6.3.3 Molnlycke Health Care AB
- 6.3.4 Organogenesis Inc.
- 6.3.5 Integra LifeSciences Holdings Corp.
- 6.3.6 MiMedx Group Inc.
- 6.3.7 Tissue Regenix Group plc
- 6.3.8 Stryker Corp.
- 6.3.9 ConvaTec Group plc
- 6.3.10 Baxter International Inc.
- 6.3.11 Coloplast A/S
- 6.3.12 Johnson & Johnson (Ethicon)
- 6.3.13 Medtronic plc
- 6.3.14 Axio Biosolutions
- 6.3.15 Fibroheal Woundcare Pvt. Ltd.
- 6.3.16 Human BioSciences
- 6.3.17 BSN medical (Essity)
- 6.3.18 Aroa Biosurgery Ltd.
- 6.3.19 Regenesis Biomedical
- 6.3.20 Gunze Limited
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


