|
시장보고서
상품코드
2125299
유럽의 식품 수탁제조 및 포장 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Food Contract Manufacturing And Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
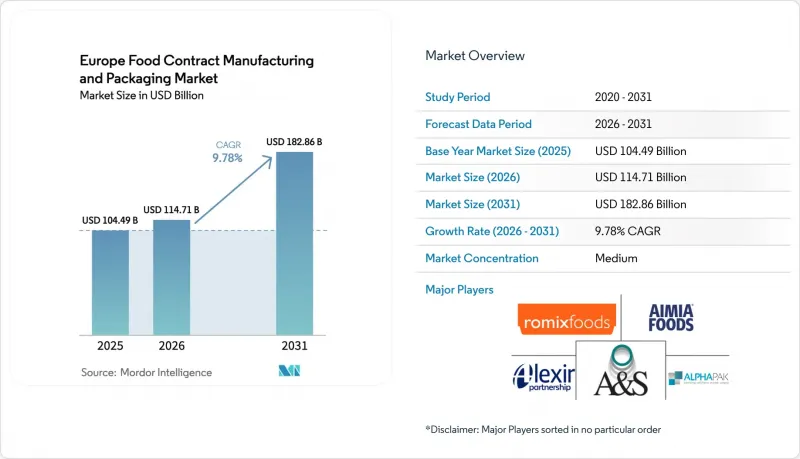
에 의하면, 유럽의 식품 수탁제조 및 포장 시장 규모는 2025년에 1,044억 9,000만 달러로 평가되었고, 2026년 1,147억 1,000만 달러에서 2031년까지 1,828억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 9.78%를 나타낼 전망입니다.
본 보고서는 서비스 유형별(가공·제조, 포장, 창고 보관·풀필먼트, 맞춤형 제조·연구 개발), 최종 이용 산업별(제빵 및 제과, 유제품, 편의 식품·레디밀, 기타), 포장 형태별(연질, 경질), 국가별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
유럽의 식품 수탁제조 및 포장 시장 동향과 인사이트
알레르기 유발 물질이 없는 제품 및 식물 유래 제품 라인에 투자하는 수탁 제조업체
각국 식품 안전 당국의 감독이 엄격해짐에 따라, 알레르기 유발 물질이 없는 제품과 식물 유래 제품 생산에 특화된 시설이 유럽 전역에서 확대되고 있습니다. 마스는 2024년, 프랑스의 8개 거점을 현대화하기 위해 1억 4,040만 달러를 투자하여 교차 오염의 위험을 배제하는 분리형 공조 및 보관 시스템을 도입했습니다. 선제적으로 대응한 기업들은 전문적인 설비 개보수 자금이 부족한 브랜드들로부터 수년에 걸친 계약을 확보하고 있습니다. 개보수 주기는 18-24개월로, 그 기간 동안은 외부 위탁 생산 능력이 일시적으로 부족해지지만, 완료 후에는 궁극적으로 전체적인 처리 능력이 향상됩니다. 이러한 수요는 비건 제품 출시가 급증하고 있으며, 공중보건 당국이 생활습관병과 동물성 단백질의 과다 섭취를 연관 짓고 있는 점에 힘입어 더욱 가속화되고 있습니다. 수탁 제조업체에게 식물성 단백질 텍스처라이제이션 라인은 알레르기 유발 물질 관리에 따른 높은 에너지 비용과 인증 비용을 상쇄할 수 있는 프리미엄 요금을 가져다줍니다. 그 결과, 이러한 추세는 유럽의 식품 수탁제조 및 포장 시장에서 수익 밀도와 협상력을 모두 높이고 있습니다.
유연한 생산 능력을 추구하는 소매 업계의 자체 브랜드 확대
현재 유럽의 식료품 소매업체들은 자사 브랜드의 이익률을 활용해 소비자를 인플레이션의 충격으로부터 보호하고 있으며, 이는 생산 일정에 전례 없는 변동을 초래하고 있습니다. 2025년 뉴 프린세스(New Princess)가 10억 달러에 카르푸 이탈리아(Carrefour Italy)를 인수한 것은 다온도대 제품 포트폴리오에 대응할 수 있는 자체 생산 능력과 위탁 생산 능력의 전략적 가치를 입증하는 사례입니다. 소매업체들은 연간 입찰 대신 분기별 입찰 주기를 채택하는 경향이 강해지고 있으며, 24시간 이내에 생산 전환을 실현할 수 있는 계약업체를 우대하고 있습니다. 일반적으로 12-18개월 간의 유연한 생산 능력 계약에는 재고 위험을 제조업체 측으로 전가하는 변동 수량 조항이 포함되게 되었습니다. 디지털 트윈을 활용한 스케줄링과 신속한 위생 관리 프로토콜을 통해 빈번한 생산 가동 비용을 상쇄할 수 있는 기업은 유럽의 식품 수탁제조 및 포장 시장에서 타사를 압도하는 시장 점유율을 확보하고 있습니다.
계약업체에 파급되는 브랜드 소유자의 가격 마진 압박
2025년, 영국의 식품 인플레이션율은 5.1%로 정점을 찍었고, 이에 따라 소매업체들은 매장 가격 상한선을 설정하고 공급업체들에게 투입 비용의 급등분을 흡수할 것을 요구했습니다. 전기·가스 요금은 2020년 기준치에 비해 2배로 치솟아, 에너지 집약적인 조리·건조 라인의 기여 이익률을 잠식하고 있습니다. 대형 수탁 제조업체는 전가 조항 협상이나 에너지 헤지를 실시하지만, 중견 기업들은 이익률 압박에 직면해 있어 설비 투자를 억제하고 있습니다. 현금 흐름의 경색으로 인해 자동화 업그레이드가 지연되면서, 유럽 식품 수탁제조 및 포장 시장 실적 격차가 확대되고 있습니다.
부문별 분석
2025년, 유럽 식품 수탁제조 및 포장 시장에서 가공·제조 부문은 46.88%의 점유율을 차지했으며, 사설 브랜드 일용식품의 대량 판매 기반으로서의 역할을 두드러지게 하고 있습니다. 이러한 규모의 이점을 활용하여 수탁 업체들은 원료의 대량 조달과 연속 흐름식 기계를 활용함으로써 브랜드 제조업체 및 소매업체를 대상으로 한 단가를 경쟁력 있는 수준으로 유지하고 있습니다. 동시에, 맞춤형 제조 및 연구 개발(R&D) 부문은 2031년까지 연평균 성장률(CAGR) 10.18%를 나타낼 것으로 예측되며, 이는 브랜드 소유자가 사내 파일럿 플랜트를 건설하지 않고도 차별화된 콘셉트를 상품화하고자 하는 절실한 요구를 보여줍니다. 이처럼 임상적으로 입증된 영양 보충제나 클린 라벨 유화 제품이 불과 1분기 만에 연구실에서 매장으로 이동함에 따라, 유럽 식품 수탁제조 및 포장 시장에서 맞춤형 제조 서비스 시장 규모는 확대될 것으로 예측됩니다.
ACG의 맞춤형 캡슐 플랫폼으로 대표되는 마이크로 배치 캡슐화 기술의 발전은 수탁 업체들이 프리미엄 요금 체계를 통해 제형의 지적 재산권(IP)을 수익화하고 있는 실제 사례를 보여줍니다. 창고 보관 및 주문 처리 서비스는 소비자 직접 판매(D2C) 흐름 증가로 혜택을 보고 있지만, 가격 책정은 여전히 수량에 연동되어 있기 때문에 공간 활용률을 최적화하기 위한 실시간 재고 가시화가 전략적으로 중요시되고 있습니다. 포장 서비스의 경우, EU의 재활용 가능성에 관한 규제 요건으로 인해 지속적인 재설계와 규제 당국의 검증이 요구되고 있으며, 그 복잡성 때문에 많은 브랜드 소유자가 외부 위탁을 선호함에 따라 이익률 향상이 예상됩니다. 전반적으로 유럽의 식품 수탁제조 및 포장 시장은 배합 개발, 가공, 규제 준수 포장을 단일 턴키 솔루션으로 제공할 수 있는 수탁 업체로 계속해서 기울고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Europe food contract manufacturing and packaging market size was valued at USD 104.49 billion in 2025 and estimated to grow from USD 114.71 billion in 2026 to reach USD 182.86 billion by 2031, at a CAGR of 9.78% during the forecast period (2026-2031).
This report is Segmented by Service Type (Processing and Manufacturing, Packaging, Warehousing and Fulfilment, Custom Formulation and R&D), End-Use Industry (Bakery and Confectionery, Dairy Products, Convenience and Ready Meals, and More), Packaging Format (Flexible, Rigid), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Food Contract Manufacturing And Packaging Market Trends and Insights
Contract-Manufacturers Investing in Allergen-Free and Plant-Based Lines
Facilities dedicated to allergen-free and plant-based production are scaling across Europe in response to stricter oversight from national food safety agencies. Mars allocated USD 140.4 million to modernize eight French sites in 2024, installing segregated air-handling and storage systems that eliminate cross-contact risk. Early movers secure multi-year contracts from brands that lack capital for specialized retrofits. The conversion cycle spans 18-24 months, temporarily tightening outsourced capacity but ultimately lifting overall throughput once finished. Demand is buoyed by a surge in vegan product launches and by public health authorities linking lifestyle diseases to overconsumption of animal proteins. For contract manufacturers, plant-protein texturization lines offer premium fees that offset the higher utility and certification expenses associated with allergen management. As a result, this trend lifts both revenue density and bargaining power within the Europe food contract manufacturing and packaging market.
Retail Private-Label Expansion Seeking Flexible Capacity
European grocers now use private-label margins to shield consumers from inflation shocks, driving unprecedented volatility in production schedules. NewPrinces' USD 1 billion acquisition of Carrefour Italia in 2025 affirms the strategic value of in-house and contracted capacity that can handle multi-temperature portfolios. Retailers increasingly issue quarterly bid cycles rather than annual tenders, rewarding contractors that demonstrate sub-24-hour changeover. Flexible capacity contracts, typically 12-18 months in length, now include variable-volume clauses that shift inventory risk back to manufacturers. Those able to amortize frequent start-ups through digital twin scheduling and rapid sanitization protocols capture disproportionate wallet share in the Europe food contract manufacturing and packaging market.
Compression of Brand Owner Price Margins Passed to Contractors
Food inflation peaked at 5.1% in the United Kingdom during 2025, prompting retailers to cap shelf prices and force suppliers to absorb input spikes. Electricity and gas tariffs doubled versus 2020 baselines, eroding contribution margins on energy-intensive cooking and drying lines. While tier-one contractors negotiate pass-through clauses or hedge energy, mid-sized firms face a margin squeeze that dampens capital spending. Constrained cash flow slows automation upgrades, widening performance gaps inside the Europe food contract manufacturing and packaging market.
Other drivers and restraints analyzed in the detailed report include:
- Digitalization and Cloud-Connected Factories Improving Line-Changeover Speeds
- E-Commerce Meal-Kit Boom Demanding Fulfillment-Ready Packaging
- Tightening EU Single-Use Plastics and PPWR Rules Raising Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Processing and manufacturing held 46.88% of the Europe food contract manufacturing and packaging market share in 2025, underscoring its role as the volume backbone for private-label staples. Its scale benefits allow contractors to leverage bulk ingredient procurement and continuous-flow machinery, keeping unit costs competitive for branded and retailer customers. Simultaneously, the custom formulation and R&D segment is forecast to grow at a 10.18% CAGR through 2031, signaling brand owner urgency to commercialize differentiated concepts without building in-house pilot plants. The Europe food contract manufacturing and packaging market size for custom formulation services is thus expected to swell as clinical-substantiated nutraceuticals and clean-label emulsions move from lab to shelf within a single quarterly cycle.
Advances in micro-batch encapsulation, such as ACG's personalized capsule platform, illustrate how contractors monetize formulation IP through premium fee structures. Warehousing and fulfillment services benefit from rising direct-to-consumer flows, but pricing remains volume-linked, placing a strategic emphasis on real-time inventory visibility to optimize cube utilization. Packaging services face margin uplift as EU recyclability mandates require continuous redesign and regulatory validation, a complexity most brand owners prefer to outsource. Overall, the Europea food contract manufacturing and packaging market continues to tilt toward contractors capable of bundling formulation, processing, and compliant packaging into a single turnkey proposition..
Complete Report Scope:
- By Service Type
- Processing and Manufacturing
- Packaging
- Warehousing and Fulfilment
- Custom Formulation and R&D
- By End-Use Industry
- Bakery and Confectionery
- Dairy Products
- Convenience and Ready Meals
- Functional and Nutraceutical Products
- Other End-Use Industries
- By Packaging Format
- Flexible
- Pouches and Sachets
- Bags
- Other Flexible Packaging
- Rigid
- Bottles and Jars
- Cans
- Pallets
- Cartons
- Other Rigid Packaging
- Flexible
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Romix Foods Limited
- Aimia Foods Ltd
- Norvik Foods Limited
- A and S Packing Company Limited
- Alexir Co-Packers Limited
- Alphapak International Ltd
- Agilery GmbH
- SternMaid GmbH and Co. KG
- Hearthside Food Solutions Europe B.V.
- STOCKMEIER Food GmbH and Co. KG
- Budelpack Poortvliet B.V.
- Complete Co-Packing Services Ltd
- Marvinpac SA
- Marsden Packaging Ltd
- HACO Holding AG
- ID Logistics SE
- PacMoore Europe B.V.
- Thrive Foods Europe Ltd
- Kilfera Food Manufacturers Limited
- Prima Foods UK Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Contract-manufacturers investing in allergen-free and plant-based lines
- 4.2.2 Retail private-label expansion seeking flexible capacity
- 4.2.3 Digitalisation and cloud-connected factories improving line-changeover speeds
- 4.2.4 E-commerce meal-kit boom demanding fulfilment-ready packaging
- 4.2.5 EU Green Deal incentives for low-carbon packaging operations
- 4.2.6 Commercialisation of upcycled ingredients supplying new value streams
- 4.3 Market Restraints
- 4.3.1 Compression of brand owner price margins passed to contractors
- 4.3.2 Tightening EU Single-Use Plastics and PPWR rules raising compliance costs
- 4.3.3 Heightened food-safety liability driven by Listeria/Allergen recalls
- 4.3.4 Volatile energy and logistics prices disrupting production planning
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
- 4.6 Impact of Macroeconomic Factors on the Market
- 4.7 Regulatory Landscape
- 4.8 Technological Outlook
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Processing and Manufacturing
- 5.1.2 Packaging
- 5.1.3 Warehousing and Fulfilment
- 5.1.4 Custom Formulation and R&D
- 5.2 By End-Use Industry
- 5.2.1 Bakery and Confectionery
- 5.2.2 Dairy Products
- 5.2.3 Convenience and Ready Meals
- 5.2.4 Functional and Nutraceutical Products
- 5.2.5 Other End-Use Industries
- 5.3 By Packaging Format
- 5.3.1 Flexible
- 5.3.1.1 Pouches and Sachets
- 5.3.1.2 Bags
- 5.3.1.3 Other Flexible Packaging
- 5.3.2 Rigid
- 5.3.2.1 Bottles and Jars
- 5.3.2.2 Cans
- 5.3.2.3 Pallets
- 5.3.2.4 Cartons
- 5.3.2.5 Other Rigid Packaging
- 5.3.1 Flexible
- 5.4 By Country
- 5.4.1 United Kingdom
- 5.4.2 Germany
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Romix Foods Limited
- 6.4.2 Aimia Foods Ltd
- 6.4.3 Norvik Foods Limited
- 6.4.4 A and S Packing Company Limited
- 6.4.5 Alexir Co-Packers Limited
- 6.4.6 Alphapak International Ltd
- 6.4.7 Agilery GmbH
- 6.4.8 SternMaid GmbH and Co. KG
- 6.4.9 Hearthside Food Solutions Europe B.V.
- 6.4.10 STOCKMEIER Food GmbH and Co. KG
- 6.4.11 Budelpack Poortvliet B.V.
- 6.4.12 Complete Co-Packing Services Ltd
- 6.4.13 Marvinpac SA
- 6.4.14 Marsden Packaging Ltd
- 6.4.15 HACO Holding AG
- 6.4.16 ID Logistics SE
- 6.4.17 PacMoore Europe B.V.
- 6.4.18 Thrive Foods Europe Ltd
- 6.4.19 Kilfera Food Manufacturers Limited
- 6.4.20 Prima Foods UK Ltd
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment