|
시장보고서
상품코드
2125304
유럽의 IP 텔레포니 및 UCAaS(Unified Communications As-a-service) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe IP Telephony And Unified Communications As-a-service - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
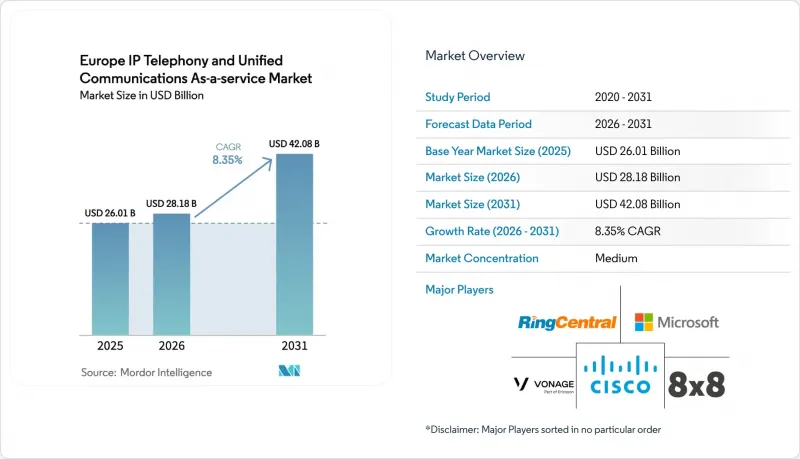
에 의하면, 2026년 유럽의 IP 텔레포니 및 UCAaS(Unified Communications As-a-service) 시장 규모는 281억 8,000만 달러로 추정되고 2025년 260억 1,000만 달러에서 성장하여 2031년에는 420억 8,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 8.35%를 나타낼 전망입니다.
본 보고서는 솔루션별(하드웨어·소프트웨어), 유형별(통합 액세스-SIP 트렁킹, 매니지드 IP PBX, 호스티드 IP PBX, 클라우드 콜 컨트롤, CPaas), 조직 규모별(대기업·중소기업), 최종 사용자별(의료, 소매, IT 및 통신,정부, 제조, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽의 IP 텔레포니 및 UCAaS(Unified Communications As-a-service) 시장 동향 및 인사이트
5G 구축 가속화로 저지연 UCAaS 실현
현재 독일과 영국의 대부분의 도시권에서 독립형 5G 네트워크가 구축되어 있으며, 기업에는 회선 교환형 음성 통신에 필적하는 10밀리초 미만의 안정적인 지연 시간이 제공되고 있습니다. 통신 사업자들은 네트워크 기능 가상화(NFV)를 통해 음성 처리 기능을 네트워크 에지에 배치하고 있으며, 이를 통해 중앙 집중형 데이터센터에 대한 의존도가 낮아지고, 컨택 센터 환경에서의 통화 품질이 향상되고 있습니다. 이러한 아키텍처의 장점은 언어 번역이나 AI를 활용한 통화 분석과 같은 실시간 기능 지원으로 이어지고 있습니다. 이러한 변화로 인해 지연에 민감한 워크로드 분야에서 유럽의 제공업체들은 세계 하이퍼스케일러와의 차별화를 꾀하며, 레거시 PBX 시스템 마이그레이션을 가속화하고 있습니다.
유럽 전역의 하이브리드 근무 정책으로의 전환
프랑스와 네덜란드에서는 팬데믹 이후의 노동 규제에 따라 유연한 근무 방식에 대한 권리가 법제화되어, 모바일 우선 협업 스위트에 대한 장기적인 수요가 확고해지고 있습니다. 북유럽의 고용주들은 기존의 하드웨어 PBX 시스템을 클라우드 도구로 대체함으로써 직원 만족도가 높아졌습니다고 보고하고 있으며, 이에 따라 프레즌스, 메시징, 화상 회의 기능의 도입이 더욱 확대되고 있습니다. 일과 삶의 균형을 중시하는 방침에 따라, 근무 시간 외 소통을 제한하는 AI 기반 회의 요약 기능의 도입이 진행되고 있습니다. 공공 부문 기관들은 유럽연합 집행위원회의 디지털 업무 환경 지침을 준수하고 있어, 정부 기관으로부터 안정적인 수요가 확보되고 있습니다.
분산된 국경을 초월한 데이터 주권 규제
GDPR(EU 개인정보보호규정)이 존재함에도 불구하고, 프랑스, 이탈리아, 독일에서는 병행된 현지화 체계가 유지되고 있어 UCAaS 공급업체는 인프라를 이중으로 구축해야 합니다. 이로 인해 규정 준수 비용이 증가하고, 유럽 전역에서의 확장이 복잡해지고 있습니다. 다국적 기업은 각 관할 구역으로의 트래픽 흐름을 파악하고 개별 재해 복구 구역을 유지해야 하므로 규모의 경제 효과가 제한됩니다. 제안된 ‘데이터 거버넌스법’은 규제 조화를 목표로 하고 있지만, 2027년까지는 시행되지 않을 것으로 예상되어 향후 플랫폼 아키텍처에 대한 불확실성이 남아 있습니다.
부문별 분석
2025년, 기존 워크플로우에 통합될 수 있는 확장 가능한 클라우드 네이티브 플랫폼에 대한 수요로 인해 소프트웨어 솔루션은 유럽의 IP 텔레포니 및 UCAaS(Unified Communications As-a-service) 시장 점유율의 61.45%를 차지했습니다. 기업들이 하드웨어 교체 주기보다 API 오케스트레이션을 선호하는 경향이 있어, 이 부문은 2031년까지 연평균 성장률(CAGR) 10.03%를 나타낼 것으로 예측됩니다. 통화 제어 및 PBX 소프트웨어는 IP 긴급 서비스에 관한 규제 의무화로 인해 직접적인 혜택을 받고 있는 반면, 통합 메시징 및 팀 협업 도구는 정착된 하이브리드 근무 방식의 흐름에 편승하고 있습니다. 각 벤더사는 AI 기반 텍스트 변환 및 감정 분석 기능을 통합하여 추가 하드웨어 없이도 부가가치를 높이고 있습니다.
국방 및 유틸리티 등 인증된 보안을 갖춘 물리적 엔드포인트가 필요한 분야에서는 하드웨어가 여전히 필수적입니다. IP 데스크폰은 촉각 인터페이스와 안정적인 서비스 품질이 요구되는 트레이딩 플로어에서 계속해서 활용되고 있습니다. VoIP 게이트웨이는 ISDN의 단계적 폐지에 따른 전환을 원활하게 하고 있지만, 광섬유가 지역 허브에 보급됨에 따라 그 중요성은 낮아지고 있습니다. 비디오 엔드포인트는 소프트웨어 정의 회의실로 전환되고 있지만, 보장된 통신 품질이 중요한 상황에서는 여전히 우선적으로 사용되고 있습니다. 전반적으로 하드웨어의 성장세는 소프트웨어에 뒤처지고 있지만, 규정 준수를 보장하기 위한 안전 장치로서의 역할을 수행하고 있습니다.
호스팅형 IP-PBX는 2025년 매출의 41.92%를 차지하며, On-Premise 레거시 시스템을 클라우드에서 직접 대체하는 역할을 수행했습니다. 이 모델은 익숙한 PBX 기능에 클라우드의 확장성을 결합함으로써 긴급 신고 기준 준수를 용이하게 합니다. 통합 SIP 트렁킹은 여전히 핵심 서비스이지만, 비디오 및 메시징을 포함한 종합적인 UCAaS 제품군에 시장 점유율을 빼앗기고 있습니다.
CPaaS는 규모는 작지만, 2031년까지 연평균 성장률(CAGR)이 8.58%로 가장 빠르게 성장하는 유형입니다. 개발자들은 CPaaS의 API를 활용하여 음성 및 영상 기능을 고객 용도에 통합함으로써 독립형 인터페이스를 불필요하게 만들고, 수직적 혁신을 촉진하고 있습니다. 매니지드 IP-PBX는 운영 업무의 아웃소싱을 원하면서도 기밀성이 높은 워크플로우에 대해서는 온사이트 관리를 유지하고자 하는 기업에게 매력적입니다. 클라우드 콜 컨트롤은 시그널링을 하드웨어에서 분리함으로써 중간적인 대안을 제공하며, 기업이 이미 투자한 자산을 효과적으로 활용할 수 있도록 합니다. 이러한 유형들은 디지털 전환을 뒷받침하는 ‘프로그래밍 가능한 통신’으로의 전환이 지속적으로 이루어지고 있음을 보여줍니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the Europe IP telephony and Unified Communications As-A-Service market size in 2026 is estimated at USD 28.18 billion, growing from 2025 value of USD 26.01 billion with 2031 projections showing USD 42.08 billion, growing at 8.35% CAGR over 2026-2031.

This report is Segmented by Solution (Hardware, and Software), Type (Integrated Access - SIP Trunking, Managed IP PBX, Hosted IP PBX, Cloud Call Control, Cpaas), Organization Size (Large Enterprises, and SMEs), End User (Healthcare, Retail, IT and Telecom, Government, Manufacturing, and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Europe IP Telephony And Unified Communications As-a-service Market Trends and Insights
Accelerated 5G Rollouts Enabling Low-Latency UCaaS
Standalone 5G coverage now blankets most metropolitan areas in Germany and the UK, giving enterprises consistent sub-10 millisecond latency that rivals circuit-switched voice. Operators have placed voice processing functions at the network edge through Network Function Virtualization (NFV), which reduces dependence on centralized data centers and improves call quality in contact center scenarios. These architecture gains support real-time capabilities such as language translation and AI call analytics. The shift differentiates European providers from global hyperscalers in terms of latency-sensitive workloads and accelerates the migration from legacy PBX systems.
Shift Toward Hybrid Work Policies Across Europe
Post-pandemic labor regulations in France and the Netherlands now codify flexible work rights, cementing long-term demand for mobile-first collaboration suites. Nordic employers report high employee satisfaction when cloud tools replace traditional hardware PBX systems, leading to broader rollouts of presence, messaging, and video functions. A policy emphasis on work-life balance drives the uptake of AI-powered meeting summaries that limit after-hours interactions. Public-sector agencies follow the European Commission's own digital workplace guidelines, ensuring steady demand from government accounts.
Fragmented Cross-Border Data-Sovereignty Regulations
Despite the GDPR, France, Italy, and Germany maintain parallel localization frameworks that require UCaaS vendors to duplicate infrastructure, thereby increasing compliance costs and complicating pan-European rollouts. Multinational firms must map traffic flows to each jurisdiction and maintain separate disaster recovery zones, limiting economies of scale. The proposed Data Governance Act aims for harmonization, yet enforcement is not expected to be implemented until 2027, leaving uncertainty over future platform architecture.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Migration From ISDN to All-IP Networks
- Growing SMB Demand For OpEx-Friendly Subscription Models
- Heightened Cyber-Attack Surface in Cloud Telephony
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software solutions held 61.45% of the Europe IP Telephony and Unified Communications As-A-Service market share in 2025 due to demand for scalable cloud-native platforms that embed into existing workflows. The category is projected to post a 10.03% CAGR to 2031 as enterprises favor API orchestration over hardware refresh cycles. Call control and PBX software benefit directly from IP emergency service mandates, while unified messaging and team collaboration tools ride the wave of established hybrid work practices. Vendors integrate AI-based transcription and sentiment analytics, boosting value without additional hardware.
Hardware remains essential for sectors that need physical endpoints with certified security, including defense and utilities. IP desk phones continue to serve trading floors that require tactile interfaces and a fixed quality of service. VoIP gateways ease transitional scenarios during the ISDN phase-out, although their relevance declines as fiber reaches regional hubs. Video endpoints are pivoting toward software-defined meeting rooms, but continue to prioritize where guaranteed optics matter. Overall, hardware growth lags behind software, yet it acts as a compliance safeguard.
Hosted IP PBX contributed 41.92% of 2025 revenue, reflecting its role as a direct cloud replacement for on-premises legacy systems. The model delivers familiar PBX features with cloud scalability, easing compliance with emergency calling standards. Integrated SIP trunking remains a backbone service but loses market share to comprehensive UCaaS suites that include video and messaging.
Communication Platform as a Service (CPaaS), although smaller, is the fastest-growing type, with an 8.58% CAGR through 2031. Developers utilize CPaaS APIs to integrate voice and video capabilities into customer applications, thereby eliminating the need for standalone interfaces and promoting vertical innovation. Managed IP PBX appeals to enterprises that want operational outsourcing but still retain on-site control for sensitive workflows. Cloud call control offers a middle path by decoupling signaling from hardware, allowing firms to preserve their sunk investments. Together, these types illustrate a migration continuum toward programmable communications that underpin digital transformation.
Complete Report Scope:
- By Solution
- Hardware
- IP Desk Phones
- VoIP Gateways
- Video Conferencing Endpoints
- Other Hardwares
- Software
- Call Control and PBX Software
- Unified Messaging
- Team Collaboration Platforms
- Contact Center Applications
- Other Softwares
- Hardware
- By Type
- Integrated Access - SIP Trunking
- Managed IP PBX
- Hosted IP PBX
- Cloud Call Control
- Communication Platform as a Service (CPaaS)
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises
- By End User
- Banking, Financial Services and Insurance
- Healthcare
- Retail and E-Commerce
- Information Technology and Telecom
- Government and Public Sector
- Manufacturing and Industrial
- Education
- Hospitality
- Other End Users
- By Geography
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Rest of Europe
List of Companies Covered in this Report:
- Microsoft Corporation
- Cisco Systems Inc.
- RingCentral Inc.
- 8x8 Inc.
- Vonage Holdings Corp.
- Zoom Video Communications Inc.
- Avaya Holdings Corp.
- Mitel Networks Corporation
- Alcatel-Lucent Enterprise International SAS
- Unify Software and Solutions GmbH and Co. KG
- Wildix Srl
- NFON AG
- Vodafone Group Plc
- BT Group plc
- Orange Business Services SA
- Telefonica SA
- Intermedia Cloud Communications Inc.
- Freshworks Inc.
- Dialpad Inc.
- Ooma Inc.
- Grandstream Networks Inc.
- Ascom Holding AG
- NEC Corporation
- Panasonic Corporation
- Ziff Davis Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated 5G Rollouts Enabling Low-Latency UCaaS
- 4.2.2 Shift Toward Hybrid Work Policies Across Europe
- 4.2.3 Rapid Migration From ISDN to All-IP Networks
- 4.2.4 Growing SMB Demand For OpEx-Friendly Subscription Models
- 4.2.5 Integration With Vertical-Specific SaaS Workflows
- 4.2.6 Edge Computing Adoption For Real-Time Voice Processing
- 4.3 Market Restraints
- 4.3.1 Fragmented Cross-Border Data-Sovereignty Regulations
- 4.3.2 Heightened Cyber-attack Surface In Cloud Telephony
- 4.3.3 Vendor Lock-In Concerns Hindering Long-Term Contracts
- 4.3.4 Skills Gap In SIP and VoIP Network Management
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution
- 5.1.1 Hardware
- 5.1.1.1 IP Desk Phones
- 5.1.1.2 VoIP Gateways
- 5.1.1.3 Video Conferencing Endpoints
- 5.1.1.4 Other Hardwares
- 5.1.2 Software
- 5.1.2.1 Call Control and PBX Software
- 5.1.2.2 Unified Messaging
- 5.1.2.3 Team Collaboration Platforms
- 5.1.2.4 Contact Center Applications
- 5.1.2.5 Other Softwares
- 5.1.1 Hardware
- 5.2 By Type
- 5.2.1 Integrated Access - SIP Trunking
- 5.2.2 Managed IP PBX
- 5.2.3 Hosted IP PBX
- 5.2.4 Cloud Call Control
- 5.2.5 Communication Platform as a Service (CPaaS)
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises
- 5.4 By End User
- 5.4.1 Banking, Financial Services and Insurance
- 5.4.2 Healthcare
- 5.4.3 Retail and E-Commerce
- 5.4.4 Information Technology and Telecom
- 5.4.5 Government and Public Sector
- 5.4.6 Manufacturing and Industrial
- 5.4.7 Education
- 5.4.8 Hospitality
- 5.4.9 Other End Users
- 5.5 By Geography
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Netherlands
- 5.5.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 Cisco Systems Inc.
- 6.4.3 RingCentral Inc.
- 6.4.4 8x8 Inc.
- 6.4.5 Vonage Holdings Corp.
- 6.4.6 Zoom Video Communications Inc.
- 6.4.7 Avaya Holdings Corp.
- 6.4.8 Mitel Networks Corporation
- 6.4.9 Alcatel-Lucent Enterprise International SAS
- 6.4.10 Unify Software and Solutions GmbH and Co. KG
- 6.4.11 Wildix Srl
- 6.4.12 NFON AG
- 6.4.13 Vodafone Group Plc
- 6.4.14 BT Group plc
- 6.4.15 Orange Business Services SA
- 6.4.16 Telefonica SA
- 6.4.17 Intermedia Cloud Communications Inc.
- 6.4.18 Freshworks Inc.
- 6.4.19 Dialpad Inc.
- 6.4.20 Ooma Inc.
- 6.4.21 Grandstream Networks Inc.
- 6.4.22 Ascom Holding AG
- 6.4.23 NEC Corporation
- 6.4.24 Panasonic Corporation
- 6.4.25 Ziff Davis Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment