

|
시장보고서
상품코드
2125306
산소 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Oxygen - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
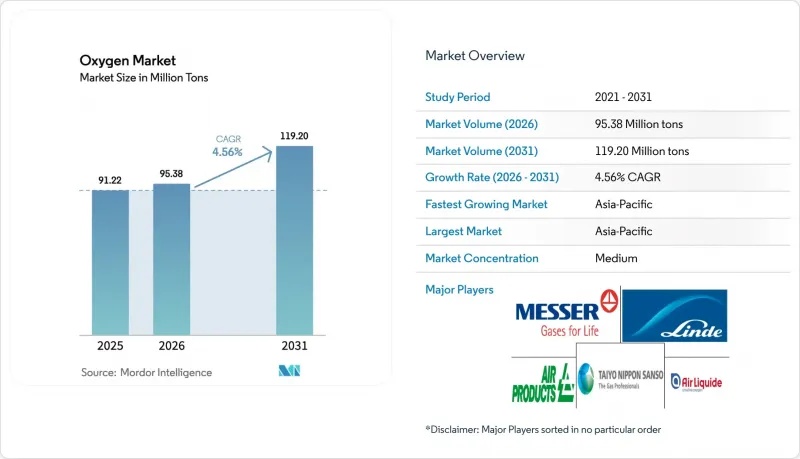
에 의하면, 산소 시장 규모는 2025년 9,122만 톤으로 평가되었습니다. 2026년에는 9,538만 톤으로 확대되어 2031년까지 1억 1,920만 톤에 이를 것으로 예상되고 2026년부터 2031년에 걸쳐 CAGR 4.56%로 성장할 전망입니다.
본 보고서는 형태(기체, 액체, 고체), 유형(산업용·의료용), 용도(금속 및 광업, 화학 산업, 석유 및 가스, 헬스케어, 제약, 기타 용도), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 수량(톤) 단위로 제시되어 있습니다.
세계의 산소 시장 동향 및 인사이트
급성 및 만성 호흡기 질환 유병률 증가
만성 폐쇄성 폐질환(COPD) 및 천식의 전 세계 환자 수는 2023년에 5억 4,500만 명에 달했으며, 대기 질 악화와 흡연이 여전히 지속되고 있는 저·중소득 국가에서는 연간 3.2%의 속도로 증가하고 있습니다. 호흡기 질환으로 인한 장애 조정 생명 연수(DALY)는 남아시아에서 총 부담의 7.8%를 차지할 정도로 증가했으며, 인도, 방글라데시, 파키스탄의 병원들은 의료용 가스 시스템의 신속한 확충을 요구받고 있습니다. 미국의 응급실에서는 2020년부터 2024년에 걸쳐 산소 의존 사례 수가 18% 급증했으며, 이러한 변화에 따라 주요 도시 지역에서는 산소 실린더 묶음에서 대용량 액체 저장 방식으로의 전환이 진행되었습니다. WHO의 최신 치료 지침에서는 호흡기 치료 시설을 갖춘 모든 입원 병동에서 고유량 산소의 지속적인 공급을 확보할 것을 의무화하고 있으며, 이에 따라 저소득 지역 전반에 걸쳐 압력 스윙 흡착(PSA) 플랜트 및 가스통 충전 거점의 도입이 가속화되고 있습니다. 이러한 요인들이 복합적으로 작용하여, 공공 및 민간 의료 네트워크 모두에서 산소 시장에 대한 직접적인 수요 증가와 지속적인 수요가 확보되고 있습니다.
아시아의 철강·비철금속 생산 증가
2024년, 중국의 조강 생산량은 10억 2,000만 톤에 달하고, 세계 점유율의 53%를 차지했습니다. 한편, 인도의 생산량은 전년 대비 7.4% 증가한 1억 4,400만 톤을 기록했습니다. 고로에 산소를 주입하여 유입 농도를 21%에서 28%로 높임으로써, 용선 1톤당 코크스 소비량이 12% 감소했으며, 중국의 제철소에서는 비용 곡선이 낮아지고 배출 상한선이 엄격해졌습니다. 인도네시아와 베트남에서는 제품 1톤당 최대 1.2톤의 산소를 소비하는 니켈 선철 제련소가 가동을 시작하여 술라웨시 섬 콴가이 주에서 안정적인 수요를 창출하고 있습니다. 한국 포항의 수소 직접 환원 시범 프로젝트는 산소를 많이 사용하는 하류 용해 공정으로의 전환을 시사하며, 동아시아 산소 시장에 미래의 강세를 가져다주고 있습니다. 따라서 견조한 철강 및 비철금속 생산은 예측 기간을 훨씬 넘어 장기적인 산업용 가스 수요를 든든히 뒷받침하고 있습니다.
대체 절단·연료 가스(LPG, 아세틸렌)의 이용 가능성
소형 용접의 경우, 휴대성이 순수한 화염 온도보다 더 중요시되기 때문에 액화석유 및 가스(LPG)나 아세틸렌이 산소·연료 조합을 대체하는 경향이 강해지고 있습니다. 2024년 미국 용접 협회(AWS)의 조사에 따르면, 미국과 멕시코 작업장의 38%가 두께 25mm 이하의 강재 절단에 LPG·공기 토치로 전환하여, 이를 통해 실린더 임대료를 월 120달러 절감하고 있습니다. 인도의 조선소나 건설 현장에서는 프로판·산소 하이브리드 방식의 도입으로 절단 1회당 산소 소비량이 전체적으로 15% 감소하는 동시에 물류도 간소화되고 있습니다. 또한 유럽에서는 압축 공기나 질소를 동력원으로 하는 플라즈마 아크 시스템이 장비 비용의 하락에 따라 절단 시장의 22%를 차지하게 되면서, 제조 분야의 산소 시장 점유율을 서서히 낮추고 있습니다. 이러한 대체 수단에는 절단 품질이나 속도 측면에서 타협점이 있지만, 취급 위험이 낮고 비용 면에서 이점이 있어 특정 사용자층에서 산소의 보급 속도를 늦추고 있습니다.
부문별 분석
2025년 시점에서 기체 공급은 산소 시장 점유율의 87.68%를 차지했으며, 현장의 공기 분리 장치에서 5-40바의 유량이 제강로, 화학 반응기, 반도체 제조 공장에 직접 공급되고 있습니다. 액체 산소는 파이프라인 부설이 경제적으로 부적합한 칠레의 아타카마 구리 광대, 호주의 필바라 광산, LNG 발전을 하는 섬들로 극저온 운송 트럭을 통해 안정적으로 공급되고 있어 연평균 성장률(CAGR) 4.55%로 확대되고 있습니다. 고체 산소에 기인한 산소 시장 규모는 항공우주 분야나 실험실에서의 이용이 제한적이기 때문에 여전히 극히 미미합니다.
새로운 동향으로, 기존 네트워크에 전해조에서 생성된 산소가 추가되고 있으며, 티센크루프사와 에어 리퀴드사가 주도하는 독일 루르 계곡의 시범 사업에서는 혼합 비용이 8% 절감되었습니다. 엑슨모빌(ExxonMobil)의 베이트운 릴라이언스(Baytown Reliance)가 자무나가르에 운영하는 LNG 발전 복합 시설에서는 플랜트의 비상 사태에 대비해 액체 산소를 극저온 탱크에 저장하고 있으며, 이는 액체 물류가 회복탄력성을 어떻게 뒷받침하고 있는지를 보여줍니다. 규제 체계(용기 설계에 관한 ISO 21969 및 고압 산소 배관에 관한 ASME 규격)에 따라 검사 주기가 단축되어, 엔지니어링 및 규정 준수를 장기 계약에 포함시킬 수 있는 대형 공급업체에 유리하게 작용하고 있습니다. 이러한 메커니즘이 결합되어 산소 시장에서 기체 산소의 주도적 지위를 강화하는 동시에, 액체 산소를 위한 명확한 성장 경로를 개척하고 있습니다.
지역별 분석
아시아태평양은 2025년에 산소 시장 점유율 41.52%로 1위를 차지했으며, 2031년까지 연평균 성장률(CAGR) 5.45%를 기록할 전망입니다. 중국의 철강 생산량 10억 2,000만 톤과 인도의 1억 4,400만 톤이 지역 수요를 뒷받침하는 한편, 인도네시아의 니켈 제련소와 베트남의 전자 산업 집적지가 수요 집중 지역으로 부상하고 있습니다. 한국에서는 삼성과 SK하이닉스가 3nm 이하 노드로 전환함에 따라 고순도 산소 수요가 급증하고 있습니다. 아시아개발은행(ADB)을 통한 아세안(ASEAN)에 대한 자금 지원으로 420기의 PSA(압력 스윙 흡착) 장치 도입이 지원되어, 인도네시아, 필리핀, 미얀마의 농촌 지역에서 가스통에 대한 의존도가 낮아지고 있습니다.
북미에서는 수소 허브, 산소 연료로의 설비 교체, 병원 설비 개보수가 주요 축을 이루고 있습니다. 국내 7개 허브는 본격 가동 후 연간 80만 톤의 산소 생산을 목표로 하고 있으며, 그중 40%는 이미 멕시코만 연안의 석유화학 계약을 통해 확보되었습니다. 캐나다는 온타리오주에서 수소 제철 시범 운영을 진행 중이며, 멕시코의 자동차 산업 회랑은 몬테레이와 과나후아토 지역의 용접 수요를 끌어올리고 있습니다. 유럽에서는 탄소 포집 인센티브와 엄격한 MDR 순도 규제가 결합되면서 의료용품 공급업체의 자본 집약도가 높아지고 있습니다.
남미, 중동 및 아프리카의 합산 점유율은 작지만, 성숙한 경제권을 능가하는 성장세를 보이고 있습니다. 브라질에서는 그린 수소 시범 사업과 전기 아크로(EAF)를 이용한 제철 확대가 수요를 견인하고 있으며, 아르헨티나에서는 리튬 추출에 산소 첨가 침출법이 채택되고 있습니다. 사우디아라비아의 네옴 복합 시설은 연간 120만 톤의 생산량 대부분을 내부에서 흡수하기 때문에 시장으로의 유출은 제한적이지만, 현지 네트워크가 성숙해지면 향후 판매 확대 가능성을 시사하고 있습니다. 남아프리카의 백금 제련소 및 PSA(압축 흡착법) 도입은 코로나19 대유행 당시공급 부족에서 얻은 교훈에 부응하는 조치입니다. 브라질의 ANVISA(국가위생감독청)부터 남아프리카공화국의 필수 의약품 목록에 이르기까지 각국의 규제는 시장 진입 요건을 강화하고 있으며, 이는 산소 시장의 지속적인 성장을 공고히 하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the oxygen market size is expected to increase from 91.22 Million tons in 2025 to 95.38 Million tons in 2026 and reach 119.20 Million tons by 2031, growing at a CAGR of 4.56% over 2026-2031.
This report is Segmented by Form (Gas, Liquid, and Solid), Type (Industrial and Medical), Application (Metals and Mining, Chemical Industry, Oil and Gas, Healthcare, Pharmaceutical, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Oxygen Market Trends and Insights
Rising Incidence of Acute and Chronic Respiratory Disorders
Global prevalence of chronic obstructive pulmonary disease and asthma reached 545 million in 2023, climbing 3.2% annually in low- and middle-income nations where air-quality deterioration and tobacco use persist. Disability-adjusted life years tied to respiratory illness rose to 7.8% of the total burden in South Asia, pushing hospitals in India, Bangladesh, and Pakistan to scale medical-gas systems quickly. Emergency departments in the United States logged an 18% jump in oxygen-dependent episodes between 2020 and 2024, a shift that triggered upgrades from cylinder bundles to bulk liquid storage in major urban centers. WHO's updated treatment guidelines now require that every inpatient ward equipped for respiratory care maintain continuous high-flow oxygen availability, ensuring that procurement of pressure-swing-adsorption (PSA) plants and cylinder-filling hubs accelerates across lower-income regions. Collectively, these factors add direct volume and ensure recurring demand for the oxygen market across both public and private healthcare networks.
Steel and Non-Ferrous Metal Production Growth in Asia
China produced 1.02 billion tons of crude steel in 2024, capturing a 53% global share, while India's output reached 144 million tons on a 7.4% year-on-year rise. Blast-furnace oxygen enrichment that lifts inlet concentration from 21% to 28% is trimming furnace coke consumption by 12% per ton of hot metal, lowering cost curves and tightening emission caps at Chinese mills. Indonesia and Vietnam commissioned nickel-pig-iron smelters that each consume up to 1.2 tons of oxygen per ton of product, generating steady offtake in Sulawesi and Quang Ngai. South Korea's hydrogen direct-reduction pilot at Pohang signals a pivot to oxygen-intensive downstream melting, adding future strength to the oxygen market in East Asia. Robust ferrous and non-ferrous production therefore anchors long-run industrial gas demand well beyond the forecast window.
Availability of Alternate Cutting/Fuel Gases (LPG, Acetylene)
Liquefied petroleum gas and acetylene increasingly displace oxygen-fuel pairs in small-scale welding where portability outweighs pure flame temperature. A 2024 American Welding Society survey showed 38% of workshops in the United States and Mexico moved to LPG-air torches for steel up to 25 mm thick, saving USD 120 per month on cylinder rental. Propane-oxygen hybrids in Indian shipyards and construction sites reduce overall oxygen draw per cut by 15% while simplifying logistics. Plasma-arc systems based on compressed air or nitrogen capture 22% cutting share in Europe on falling equipment costs, nudging down oxygen market volumes in fabrication. Although these alternatives carry trade-offs in cut quality and speed, their lower handling risks and cost advantages slow oxygen penetration in selected user segments.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of On-Purpose Hydrogen and Oxy-Fuel Projects
- Hospital Shift to PSA Micro-Plants in Emerging Markets
- Trace-Contaminant Limits for EU MDR Oxygen APIs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Gaseous supply held 87.68% oxygen market share in 2025 as on-site air-separation units dispatch flows at 5-40 bar straight into steel furnaces, chemical reactors, and chip fabs. Liquid oxygen expands at a 4.55% CAGR because cryogenic trucks deliver steady volumes to Chile's Atacama copper belt, Australia's Pilbara mines, and LNG-to-power islands where pipelines prove uneconomical. The oxygen market size attributable to solid oxygen remains marginal because of limited aerospace and laboratory usage.
Emerging trends add electrolyzer-generated oxygen to existing networks, cutting blended costs by 8% in Germany's Ruhr Valley pilot led by ThyssenKrupp and Air Liquide. LNG power complexes at ExxonMobil's Baytown and Reliance Jamnagar now store liquid oxygen in cryogenic tanks to cushion plant upsets, illustrating how liquid logistics underpin resiliency. Regulatory frameworks-ISO 21969 for vessel design and ASME codes for high-pressure oxygen piping-tighten inspection intervals, favoring large suppliers that can bundle engineering and compliance into long-term contracts. Collectively, these mechanics reinforce gaseous leadership while carving a distinct growth lane for liquid in the oxygen market.
Complete Report Scope:
- By Form
- Gas
- Liquid
- Solid
- By Type
- Industrial
- Medical
- By Application
- Metals and Mining
- Chemical Industry
- Oil and Gas
- Healthcare
- Pharmaceutical
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific led with a 41.52% oxygen market share in 2025 and is on track for a 5.45% CAGR through 2031. China's 1.02 billion-ton steel output and India's 144 million tons anchor regional volume, while Indonesia's nickel smelters and Vietnam's electronics corridors add pockets of intensity. South Korea contributes high-purity spikes as Samsung and SK Hynix move to sub-3 nm nodes. ASEAN financing through the Asian Development Bank supported 420 PSA installations that shrink rural cylinder dependence in Indonesia, the Philippines, and Myanmar.
North America is anchored by hydrogen hubs, oxy-fuel retrofits, and hospital upgrades. Seven domestic hubs aim to yield 800,000 tons of co-product oxygen yearly once fully operational, with 40% already tied up in Gulf Coast petrochemical contracts. Canada pilots hydrogen iron-making in Ontario, and Mexico's automotive corridor lifts welding demand in Monterrey and Guanajuato. In Europe, mixing carbon-capture incentives with stringent MDR purity rules raises capital intensity for medical suppliers.
South America and the Middle East and Africa collectively weigh in a smaller share but outpace mature economies. Brazil's green-hydrogen pilots and EAF steel expansions shape demand, while Argentina's lithium extraction relies on oxygenated leaching . Saudi Arabia's Neom complex will internally absorb most of its 1.2 million-ton output, limiting merchant spillover yet signaling potential for future offtake if local networks mature. South Africa's platinum smelters and PSA deployments respond to lessons from COVID-19-era shortages. National regulations, from Brazil's ANVISA to South Africa's Essential Medicines List, reinforce market access requirements that cement sustained oxygen market growth.
- Air Liquide
- Air Products and Chemicals, Inc.
- AIR WATER INC
- Axcel Gases
- Gruppo SIAD
- Guangdong Huate Gas Co., Ltd.
- Gulfcryo
- Hangzhou Oxygen Group Co., Ltd.
- INOX-Air Products Inc.
- International Industrial Gases Ltd
- Iwatani Corporation
- Linde PLC
- Messer SE & Co. KGaA
- NIPPON SANSO HOLDINGS CORPORATION
- Sauerstoffwerk Friedrichshafen GmbH
- SOL Spa
- Steelman Gases Pvt. Ltd.
- Yingde Gas Shanghai
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Incidence of Acute and Chronic Respiratory Disorders
- 4.2.2 Steel and Non-Ferrous Metal Production Growth in Asia
- 4.2.3 Expansion of On-Purpose Hydrogen and Oxy-Fuel Projects
- 4.2.4 Hospital Shift to PSA Micro-Plants in Emerging Markets
- 4.2.5 Ultra-High-Purity O2 Demand from Advanced-Node Semiconductors
- 4.3 Market Restraints
- 4.3.1 Availability of Alternate Cutting/Fuel Gases (LPG, Acetylene)
- 4.3.2 Global Shortage of Large-Bore Cryogenic Iso-Tankers
- 4.3.3 Trace-Contaminant Limits for EU MDR Oxygen Apis
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Form
- 5.1.1 Gas
- 5.1.2 Liquid
- 5.1.3 Solid
- 5.2 By Type
- 5.2.1 Industrial
- 5.2.2 Medical
- 5.3 By Application
- 5.3.1 Metals and Mining
- 5.3.2 Chemical Industry
- 5.3.3 Oil and Gas
- 5.3.4 Healthcare
- 5.3.5 Pharmaceutical
- 5.3.6 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Air Liquide
- 6.4.2 Air Products and Chemicals, Inc.
- 6.4.3 AIR WATER INC
- 6.4.4 Axcel Gases
- 6.4.5 Gruppo SIAD
- 6.4.6 Guangdong Huate Gas Co., Ltd.
- 6.4.7 Gulfcryo
- 6.4.8 Hangzhou Oxygen Group Co., Ltd.
- 6.4.9 INOX-Air Products Inc.
- 6.4.10 International Industrial Gases Ltd
- 6.4.11 Iwatani Corporation
- 6.4.12 Linde PLC
- 6.4.13 Messer SE & Co. KGaA
- 6.4.14 NIPPON SANSO HOLDINGS CORPORATION
- 6.4.15 Sauerstoffwerk Friedrichshafen GmbH
- 6.4.16 SOL Spa
- 6.4.17 Steelman Gases Pvt. Ltd.
- 6.4.18 Yingde Gas Shanghai
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


