|
시장보고서
상품코드
2125333
산업용 수중 펌프 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Industrial Submersible Pumps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
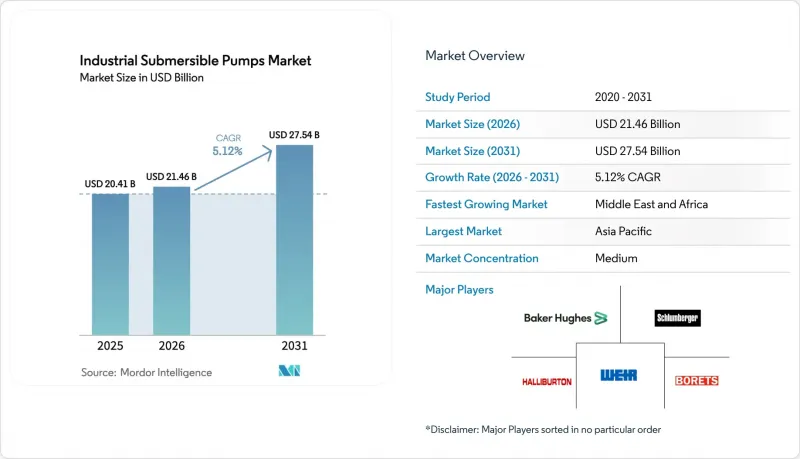
에 의하면, 산업용 수중 펌프 시장 규모는 2025년에 204억 1,000만 달러로 평가되었고, 2026년 214억 6,000만 달러에서 2031년까지 275억 4,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.12%를 나타낼 전망입니다.
본 보고서는 구동 방식별(전기식, 유압식 등), 펌프 유형별(심정용, 얕은 우물용, 오물·오수용 등), 최종 사용자 산업별(상하수도, 광업 및 건설 등), 정격 출력별(저출력(15kW 미만), 중출력(15-100kW) 등), 양정별(50m 미만, 50-100m), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 산업용 수중 펌프 시장 동향 및 인사이트
전 세계 상하수도 인프라의 확대
세계 지방 자치 단체들은 누수를 막고 새로운 처리 용량 기준을 충족하기 위해 펌프장 개보수를 추진하고 있습니다. 텍사스주는 2025년, 수중 펌프 개보수를 포함한 정수 사업에 4억 8,100만 달러를 배정했습니다. 푸에르토리코의 42억 달러 규모의 재건 사업은 1,267곳의 펌프 설비를 대상으로 하고 있으며, 기후 변화의 영향을 받기 쉬운 지역 수요 규모를 여실히 보여주고 있습니다. 인구 밀도가 높은 도시에서는 소규모 분산형 처리 시설이 증가하고 있으며, 기존의 중앙 집중형 시설에 비해 처리 용량 1메가리터당 더 많은 펌프가 필요합니다. 또한 상수도 유틸리티 사업자들은 펌프의 수명 주기 비용의 80%를 초과하기도 하는 전기 요금을 절감하기 위해 IE5 등급 모터를 요구하고 있습니다. 에너지 절감 효과를 입증할 수 있는 공급업체는 현재 수년에 걸친 기본 계약을 체결하고 있으며, 이를 통해 상품 가격 변동으로부터 수익을 보호할 수 있게 되었습니다.
전 세계적으로 진행되는 급속한 도시화와 건설 프로젝트
아시아에서는 새로운 도시 개발의 최대 물결이 일어나고 있으며, 아시아개발은행(ADB)은 2030년까지 연간 1조 7,000억 달러 규모의 인프라 수요가 있을 것으로 추산하고 있습니다. 지하철 터널, 지하실, 송전용 터널의 심부 굴착 작업에서는 소형 수중 배수 장치가 선호됩니다. 이는 지상 설치형 대체 제품이 소음의 원인이 되고, 제한된 현장 공간을 차지하기 때문입니다. 2024년, 아세안(ASEAN)에 대한 외국인 직접 투자액은 2,300억 달러에 달했으며, 그 대부분은 공정용수 순환을 위해 내식성 펌프가 필요한 재생에너지 단지에 투자되었습니다. 빌딩 정보 모델링(BIM) 소프트웨어를 통해 펌프 용량 선정이 정확하게 이루어지게 되어, 과잉 사양의 감축과 고정밀 수력 유닛에 대한 수요 증가로 이어지고 있습니다. 이러한 추세로 인해 일반 산업의 설비 투자가 둔화되더라도, 프로젝트 주도형 펌프 수주에 대해서는 안정적인 발주 일정이 유지되고 있습니다.
전체 수명 주기에 걸친 높은 유지보수 비용 및 철거 비용
심정용·해양용 펌프는 회수할 때마다 며칠간의 생산 중단을 피할 수 없기 때문에 막대한 개보수 비용이 소요되는 경우가 적지 않습니다. 전기적 고장은 ESP(전동 펌프) 고장 원인의 61%를 차지하며, 우물의 노후화에 따라 평균 고장 간격(MTBF)이 단축됨에 따라 현장 운영자의 운영 예산은 늘어나고 있습니다. 싱글 탱크, 듀얼 펌프 어레이 등의 기술 혁신은 가동 중단 시간을 단축하는 한편, 설비 투자 비용을 상승시켜 비용에 민감한 생산 사업자에게는 도입을 지연시키는 상충 효과를 낳고 있습니다. 지상 설치형 세트로 양정 요건을 충족할 수 있는 경우, 자산 소유자는 수중 펌프로의 업그레이드를 보류할 수 있으며, 이는 시장 규모 확대를 저해하고 있습니다. 공급업체들은 완전한 인양 작업 없이 모터나 씰 섹션을 교체할 수 있는 모듈식 ESP로 대응하고 있지만, 이러한 설계는 여전히 가격이 비싸 모든 구매자가 그 비용을 감당할 수 있는 것은 아닙니다.
부문 분석
2025년, 산업용 수중 펌프 시장에서 전동 부문은 33.45%의 점유율을 차지했습니다. 이는 안정적인 전력 공급을 중시하는 송전망에 연결된 지자체 및 산업 시설에 의해 뒷받침된 결과입니다. IE5 영구 자석 모터가 널리 이용 가능해짐에 따라 사업자는 배관을 재설계하지 않고도 전기 요금을 절감할 수 있게 되어, 전동 부문의 우위가 더욱 강화되고 있습니다. 가변 주파수 구동 장치는 현재 표준 사양으로 출하되고 있어, 플랜트는 유량을 실시간 수요에 맞추어 조정함으로써 스로틀링으로 인한 손실을 방지할 수 있습니다. 유압 구동 시스템은 시장 규모는 작지만, 심층 우물 시추나 해양 시추 설비에서 극한의 압력 하에서 정밀한 속도 제어가 요구되기 때문에 2031년까지 연평균 성장률(CAGR) 5.43%가 예상됩니다. 컴팩트한 파워팩과 새로운 유체 조절 회로로 인해 누설이 감소하여, 전기 절연이 어려운 장소에서도 유압 구동이 실용화되고 있습니다. 공기 구동 및 디젤 구동 펌프는 재난 대응이나 전력망이 정비되지 않은 외딴 지역의 건설 현장에서 틈새 수요를 유지하고 있습니다. 모든 형태에서 디지털 인터페이스를 통한 원격 계측이 표준화되어, 운영자는 상태 데이터의 가시성을 저해하지 않으면서 서로 다른 유형의 펌프를 혼합하여 운용할 수 있게 되었습니다.
산업용 수중 펌프 시장에서는 용도별 위험 프로파일에 맞추어 구동 시스템을 맞춤화하는 공급업체가 계속해서 우위를 점하고 있습니다. 상수도 유틸리티에서는 수명 주기 비용 측면에서 전기 시스템이 우위를 차지하지만, 마모성이 높은 슬러리를 다루는 고양정 광산에서는 유압 시스템이 더 높은 수익률을 가져다주고 있습니다. 또한, 홍수 피해가 잦은 도시에서는 자립적인 내장애성을 요구하기 때문에 디젤식 패키지가 여전히 긴급 계약을 수주하고 있습니다. 각국 정부가 탄소세를 도입하는 가운데, 일부 광산에서는 현장의 태양광 발전 설비를 동력원으로 하는 하이브리드 방식(전기·유압 병용) 세트의 도입이 검토되고 있어, 구동 방식의 선택이 단순한 기술적 판단이 아니라 에너지 전략상의 결정 사항이 되어가고 있음이 부각되고 있습니다. 여러 구동 방식을 아우르는 제품 라인업을 유지하는 공급업체는 수요 변화에 대응하는 동시에 데이터 스트림을 단일 대시보드로 통합함으로써 애프터서비스 수익을 확보하고 있습니다.
2025년, 시추 우물용 펌프는 적당한 유량으로 높은 양정을 필요로 하는 심층 농업용 및 도시용 우물에 대응함으로써 산업용 수중 펌프 시장의 40.15% 점유율을 차지했습니다. 다단 원심 펌프의 설계에는 현재 내식성 임펠러가 채택되어 있어, 기수대의 대수층에서도 유지보수 주기를 연장하고 있습니다. 막힘 방지형 하수 펌프는 이물질 혼입으로 인해 개방형 우물형 유닛이 막힐 우려가 있는 하수 처리장에서 채택되고 있으며, 그 와류 임펠러를 통해 유지보수 시간을 단축하고 있습니다. 슬러리·탈수 펌프는 고밀도의 광미(광석 찌꺼기)를 다루는 구리, 리튬,철광석 프로젝트의 확대로 인해 2031년까지 연평균 성장률(CAGR) 6.18%를 기록할 전망입니다. 내마모성 코팅과 조절 가능한 마모 링을 통해 수명이 연장되어, 외딴 지역의 채굴 현장에서 발생하는 가동 중단 시간이 줄어듭니다.
운영자가 센서를 도입하여 고형물 부하와 가동 주기를 기록하게 됨에 따라, 펌프 모델 선정은 점점 더 데이터에 기반하게 되고 있습니다. 이러한 변화로 인해 마모 패턴을 시뮬레이션하고 적절한 크기의 모델을 추천할 수 있는 용도 엔지니어링 팀을 보유한 공급업체가 유리해지며, 설비 투자(CAPEX)와 예비 부품 재고를 모두 절감할 수 있습니다. 산업용 수중 펌프 시장에서는 모래 혼입과 유량 변동이라는 두 가지 문제를 모두 겪는 지자체 프로젝트를 위한 우물용 및 슬러리용 하이브리드 설계와 같은 크로스오버 장비도 등장하고 있습니다. 식품 공장에서는 위생 기준에 따라 도장 표면이 금지된 장소에서 스테인리스 재질의 위생 펌프가 점차 보급되고 있습니다. NSF에서 ATEX에 이르기까지 업계 고유의 기준 준수를 입증할 수 있는 제조업체에게 각 틈새 시장은 이익률 향상을 가져다줍니다.
지역별 분석
아시아태평양은 계속해서 시장의 중심지이며, 2025년에는 산업용 수중 펌프 시장 가치의 44.05%를 차지한 것으로 평가되었으며, 시장 전체의 연평균 성장률(CAGR)인 5.12%에 부합하는 성장이 전망됩니다. 중국의 노후화된 도시 상수도 시설 교체, 인도의 ‘잘 지반 미션’, 아세안(ASEAN) 국가들로의 제조업 유입이 견조한 수주 잔고를 뒷받침하고 있으며, 한편 국내 공급업체들은 가격에 민감한 농촌 지역 수요에 부응하기 위해 생산 규모를 확대되고 있습니다. 일본과 한국의 기업들은 효율성의 한계를 넓히며, 향후 지역 전체로 확산될 IoT 시범 프로젝트를 추진하고 있습니다.
중동 및 아프리카은 규모는 작지만, 해수 담수화, 지역 냉방, 대규모 인프라 프로젝트가 급증함에 따라 2031년까지 연평균 성장률(CAGR) 6.03%를 나타낼 것으로 예측됩니다. 사우디아라비아는 2025년에 2억 9,300만 달러 규모의 하수 처리 및 파이프라인 계약을 발주했으며, 모로코는 219km에 달하는 담수화 파이프라인 건설을 위해 1억 유로의 IFC 대출을 확보했습니다(ifc.org). NEOM의 넷 제로(Net Zero) 물 네트워크는 이 지역이 태양광 발전을 동력원으로 하고 디지털 기술로 제어되는 양수 플랫폼으로 비약적으로 전환되고 있음을 보여줍니다.
북미와 유럽에서는 유틸리티자들이 전후에 구축된 자산을 갱신하고 더욱 엄격한 효율화 요건을 준수함에 따라, 성숙기에 접어들었음에도 불구하고 견조한 성장이 나타나고 있습니다. 2025년 5월에 발효되는 미국 에너지부(DOE) 기준에 따라, 산업 단지는 펌프 효율 보고서를 제출해야 할 의무가 있으며, IE4 및 IE5 규격의 시스템 구매가 촉진되고 있습니다. 텍사스주 수자원 위원회의 4억 8,100만 달러 자금 지원과 푸에르토리코의 기후 변화에 강한 재건 사업은 선진국 시장에서도 수중 펌프 공급업체에게 여전히 상당한 규모의 잠재 시장이 존재함을 뒷받침하고 있습니다. 남미에서는 칠레의 새로운 리튬 염수 프로젝트와 브라질 세라두 지역에서의 태양광 발전을 활용한 관개 시스템 도입으로 인해 긍정적인 성장세가 예상되며, 이는 전 세계 매출 기준을 확대되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the industrial submersible pumps market size was valued at USD 20.41 billion in 2025 and estimated to grow from USD 21.46 billion in 2026 to reach USD 27.54 billion by 2031, at a CAGR of 5.12% during the forecast period (2026-2031).
This report is Segmented by Drive Type (Electric, Hydraulic, and More), Pump Type (Borewell, Open-Well, Non-Clog Sewage, and More), End-User Industry (Water and Wastewater, Mining and Construction, and More), Power Rating (Low (Less Than15 KW), Medium (15-100 KW), and More), Head Depth (Below 50 M, 50 - 100 M), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Submersible Pumps Market Trends and Insights
Expanding Global Water and Wastewater Infrastructure
Municipal utilities worldwide upgrade pump stations to stem leakage and meet new capacity standards. Texas allocated USD 481 million in 2025 for clean-water schemes that include submersible pump retrofits. Puerto Rico's USD 4.2 billion rebuild covers 1,267 pumping assets, illustrating the scale of demand in climate-exposed regions. Smaller, distributed treatment plants proliferate in dense cities, requiring more pumps per megaliter of capacity than legacy centralized plants. Utilities also seek IE5-class motors to curb electricity bills, a cost line that can exceed 80% of lifetime pump spending. Suppliers able to certify energy savings now win multi-year framework contracts that insulate revenues from commodity-price swings.
Rapid Urbanization and Construction Projects Across the Globe
Asia hosts the biggest wave of new urban developments, with the Asian Development Bank estimating USD 1.7 trillion in yearly infrastructure needs to 2030. Deep excavation for metro tunnels, basements, and power tunnels favors compact submersible dewatering sets because surface-mounted alternatives cause noise and block limited site space. Foreign direct investment into ASEAN hit USD 230 billion in 2024, much of it channeled to renewable-energy parks that rely on corrosion-resistant pumps for process water circulation. Building-information-modeling software now sizes pumps accurately, trimming overspecification and reinforcing demand for high-precision hydraulic units. These trends sustain a steady call-off schedule for project-driven pump orders even when general industrial capex softens.
High Lifecycle Maintenance and Pull-Out Costs
Deep-well and offshore pumps often require costly workovers because each retrieval can halt production for days. Electrical faults account for 61% of ESP failures, and mean time between failures shortens as wells age, inflating operating budgets for field operators. Innovations such as single-tank dual-pump arrays reduce downtime yet push capital costs higher, creating a trade-off that slows adoption for cost-sensitive producers. Where surface-mounted sets can meet head requirements, asset owners sometimes shelve submersible upgrades, holding back market volume growth. Suppliers respond with modular ESPs that allow motor or seal section swaps without full pull-out, but these designs still command a premium that not all buyers can absorb.
Other drivers and restraints analyzed in the detailed report include:
- Recovery in Upstream Oil and Gas Drilling (ESP Adoption)
- Government Push for Industrial Energy-Efficiency Retrofits
- Volatility in Stainless-Steel and Rare-Earth Motor Materials
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The electric segment accounted for 33.45% of industrial submersible pumps market share in 2025, supported by grid-connected municipal and industrial sites that prize predictable power supply. Widespread availability of IE5 permanent-magnet motors lets operators trim electricity bills without redesigning piping, reinforcing electric leadership. Variable-frequency drives now ship as standard, letting plants match flow to real-time demand and avoiding throttling losses. Hydraulic drive systems, though a smaller base, are slated for a 5.43% CAGR through 2031 as deep-well mining and offshore rigs need precise speed control under extreme pressure. Compact power packs and new fluid-conditioning circuits reduce leakage, making hydraulics viable where electric insulation is difficult. Air and diesel sets keep niche relevance for disaster response and remote construction where grid power is absent. Across all formats, digital interfaces standardize telemetry, letting operators mix fleets without losing visibility into condition data.
The industrial submersible pumps market continues to reward suppliers that tailor drive offerings to application risk profiles. Electric systems win on life-cycle cost in water utilities, but hydraulics attract premium margins in high-head mines that face abrasive slurries. Diesel packages still secure emergency contracts from flood-prone cities wanting standalone resilience. As governments add carbon taxes, some mineshafts consider hybrid electric-hydraulic sets powered by onsite solar arrays, underscoring how drive choice is becoming an energy-strategy decision rather than a pure engineering call. Suppliers that maintain multi-drive catalogs hedge demand shifts and capture back-end service revenue by unifying data streams onto single dashboards.
Borewell pumps captured 40.15% share of the industrial submersible pumps market in 2025 by catering to deep agricultural and municipal wells that demand high head at modest flow. Multistage centrifugal designs now feature corrosion-resistant impellers that stretch service intervals even in brackish aquifers. Non-clog sewage pumps occupy wastewater plants where ragging can choke open-well units; their vortex impellers lower maintenance hours. Slurry and dewatering pumps will deliver a 6.18% CAGR into 2031 thanks to expanded copper, lithium, and iron-ore projects that handle dense tailings. Abrasion-resistant coatings and adjustable wear rings extend life, reducing downtime in remote pits.
Pump-type selection is increasingly data-driven as operators deploy sensors to log solids loading and duty cycles. This shift favors vendors with application engineering teams that can simulate wear patterns and recommend right-sized models, reducing both capex and spares inventory. The industrial submersible pumps market also sees crossover equipment such as hybrid borewell-slurry designs for municipal projects that face both sand ingress and variable flow. In food factories, stainless sanitary pumps gain traction where hygiene codes ban painted surfaces. Each niche offers margin uplift for manufacturers that can certify compliance with sector-specific standards, from NSF to ATEX.
Complete Report Scope:
- By Drive Type
- Electric
- Hydraulic
- Air- and Diesel-Driven
- By Pump Type
- Borewell
- Open-well
- Non-clog Sewage
- Slurry and Dewatering
- By End-user Industry
- Water and Wastewater
- Oil and Gas
- Mining and Construction
- Power Generation
- Food and Beverage
- Agriculture and Irrigation
- By Power Rating
- Low (Less than 15 kW)
- Medium (15-100 kW)
- High (Higher than 100 kW)
- By Head Depth
- Below 50 m
- 50 - 100 m
- Above 100 m
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Gulf Cooperation Council Countries
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific remained the epicenter, holding 44.05% of industrial submersible pumps market value in 2025, and is forecast to track the overall 5.12% CAGR. China's replacement of aging city mains, India's Jal Jeevan Mission, and ASEAN manufacturing inflows underpin steady order books, while domestic suppliers scale up to meet price-sensitive rural demand. Japanese and South Korean firms push efficiency frontiers, seeding IoT pilot projects that later diffuse across the region.
The Middle East and Africa, although smaller, is expected to log a 6.03% CAGR through 2031 as desalination, district cooling, and mega-infrastructure projects proliferate. Saudi Arabia launched USD 293 million of sewage and pipeline contracts in 2025, and Morocco secured a EUR 100 million IFC loan for a 219 km desalinated-water pipeline ifc.org. NEOM's net-zero water network illustrates how the region leapfrogs to solar-powered, digitally orchestrated pumping platforms.
North America and Europe show mature yet resilient growth as utilities replace post-war assets and comply with tighter efficiency mandates. The U.S. DOE standard effective May 2025 forces industrial campuses to file pump-efficiency reports, steering purchases toward IE4 and IE5 systems. Texas water-board funding of USD 481 million and Puerto Rico's climate-proof rebuild confirm that even developed markets still offer sizeable addressable pockets for submersible suppliers. South America contributes opportunistic upside via new lithium brine projects in Chile and solar-irrigation rollouts in Brazil's cerrado, broadening the global revenue footprint.
- Grundfos Group
- Xylem Inc.
- Sulzer Ltd
- KSB SE and Co. KGaA
- Weir Group PLC
- Franklin Electric Co. Inc.
- Baker Hughes Co.
- Schlumberger Ltd
- Halliburton Co.
- Atlas Copco AB
- Ebara Corporation
- Tsurumi Manufacturing
- Flowserve Corporation
- Wilo SE
- Kirloskar Brothers Ltd
- Pentair PLC
- Gorman-Rupp Company
- Borets International
- Shakti Pumps (India) Ltd
- WEG Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding global water and wastewater infrastructure
- 4.2.2 Rapid urbanization and ongoing construction projects across the globe
- 4.2.3 Recovery in upstream oil and gas drilling (ESP adoption)
- 4.2.4 Government push for industrial energy efficiency retrofits
- 4.2.5 Surge in solar-powered submersible pump subsidies for agriculture
- 4.2.6 Rapid digitalisation: IoT-enabled condition-monitoring pumps
- 4.3 Market Restraints
- 4.3.1 High lifecycle maintenance and pull-out costs
- 4.3.2 Volatility in stainless-steel and rare-earth motor materials
- 4.3.3 Absence of IE3 efficiency mandates delays procurement cycles
- 4.3.4 Motor Failure results in operations bottleneck in critocal infrastructure sector
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Buyers
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Drive Type
- 5.1.1 Electric
- 5.1.2 Hydraulic
- 5.1.3 Air- and Diesel-Driven
- 5.2 By Pump Type
- 5.2.1 Borewell
- 5.2.2 Open-well
- 5.2.3 Non-clog Sewage
- 5.2.4 Slurry and Dewatering
- 5.3 By End-user Industry
- 5.3.1 Water and Wastewater
- 5.3.2 Oil and Gas
- 5.3.3 Mining and Construction
- 5.3.4 Power Generation
- 5.3.5 Food and Beverage
- 5.3.6 Agriculture and Irrigation
- 5.4 By Power Rating
- 5.4.1 Low (Less than 15 kW)
- 5.4.2 Medium (15-100 kW)
- 5.4.3 High (Higher than 100 kW)
- 5.5 By Head Depth
- 5.5.1 Below 50 m
- 5.5.2 50 - 100 m
- 5.5.3 Above 100 m
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Gulf Cooperation Council Countries
- 5.6.5.2 Turkey
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Grundfos Group
- 6.4.2 Xylem Inc.
- 6.4.3 Sulzer Ltd
- 6.4.4 KSB SE and Co. KGaA
- 6.4.5 Weir Group PLC
- 6.4.6 Franklin Electric Co. Inc.
- 6.4.7 Baker Hughes Co.
- 6.4.8 Schlumberger Ltd
- 6.4.9 Halliburton Co.
- 6.4.10 Atlas Copco AB
- 6.4.11 Ebara Corporation
- 6.4.12 Tsurumi Manufacturing
- 6.4.13 Flowserve Corporation
- 6.4.14 Wilo SE
- 6.4.15 Kirloskar Brothers Ltd
- 6.4.16 Pentair PLC
- 6.4.17 Gorman-Rupp Company
- 6.4.18 Borets International
- 6.4.19 Shakti Pumps (India) Ltd
- 6.4.20 WEG Industries
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment