|
시장보고서
상품코드
2125337
침전 실리카 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Precipitated Silica - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
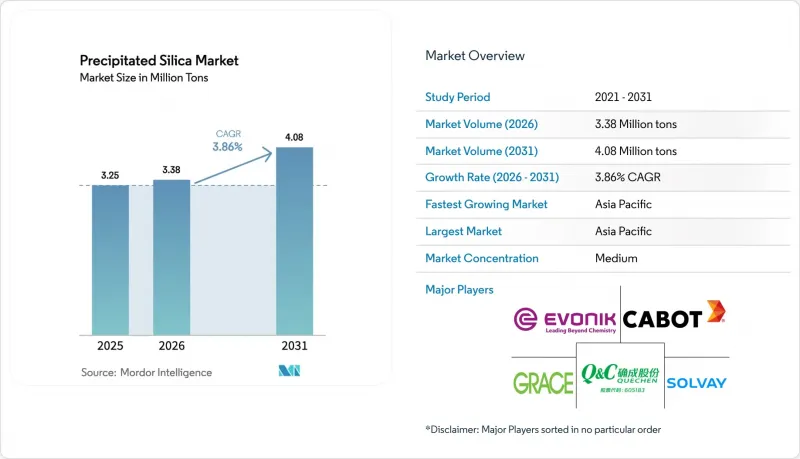
에 따르면 침전 실리카 시장 규모는 2025년 325만 톤에서 2026년에는 338만 톤으로 확대하며, 2031년까지 408만 톤에 달할 것으로 예상되고 있으며, 2026-2031년에 CAGR 3.86%로 성장할 것으로 전망되고 있습니다.
이 보고서는 등급(고무, 식품, 사료, 기타), 형태(분말, 비드, 마이크로펄, 과립),제조 공정(습식 및 건식), 최종 용도 산업(농업, 구강 관리·화장품, 타이어, 전자제품 등) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 톤 기준으로 제시되어 있습니다.
전 세계 침강성 실리카 시장의 동향 및 인사이트
전동화에 힘입은 실리카 강화 전기자동차(EV)용 타이어 수요
순간 토크와 무거워진 배터리 팩의 영향으로 전기자동차용 타이어의 마모는 가속화되고 있지만, 주행 거리 목표 달성을 위해 자동차 제조사들은 구름 저항을 줄여야 하는 상황에 직면해 있습니다. 침전 실리카의 배합량을 10-15 phr에서 20-30 phr로 늘림으로써, 그립력을 유지하면서 히스테리시스를 최대 25%까지 줄일 수 있습니다. 중국에서는 2025년에 950만 대의 배터리식 전기자동차 및 플러그인 하이브리드차가 생산될 예정이며, 차량당 4-5개의 타이어가 소비될 것입니다. 이 타이어들의 실리카 함유량은 내연기관 차량 모델보다 40-60% 더 높으며, 이로 인해 현지 연간 수요 증가량은 약 5만-7만 톤에 달합니다. 2024년 중반에 시행된 EU 타이어 라벨 표시 기준의 강화가 이러한 전환을 지원하고 있으며, 북미 자동차 제조사들도 유사한 조달 사양을 채택하여 원유 가격 변동과 관계없이 기본 타이어 설계에 실리카를 포함시키고 있습니다. 이러한 동향으로 인해 침전 실리카 시장의 구조적 성장이 확실해졌으며, 각 지역의 생산자들이 전기자동차용 등급의 전용 생산 능력에 대한 투자를 추진하도록 촉진하고 있습니다.
저회전저항 친환경 타이어에 대한 규제 추진
미국에서는 기업 평균 연비(CAFE) 규제에 따라 2026년형 승용차에 대해 49 mpg의 목표가 설정되어 있으며, 자동차 제조사는 3-5%의 연비 개선을 실현할 수 있는 저회전저항 타이어의 채택이 의무화되어 있습니다. ASTM F2493 시험 절차와 ISO 28580의 조화를 통해 타이어 제조업체는 전 세계에서 일관되게 실리카 배합을 검증할 수 있게 되었습니다. 일본과 한국에서는 구름 저항 계수가 9.0 미만인 경우에만 타이어 라벨의 최고 등급이 부여되지만, 이 수준은 실리카를 통한 보강 없이는 거의 달성할 수 없습니다. 또한 두 시장 모두 2025년에는 승용차용 타이어에서 실리카의 보급률이 70%를 넘어섰습니다. 이러한 협력적인 정책은 침전 실리카 시장을 단기적인 가격 변동으로부터 보호하는 최소 준수 기준을 형성하고 있으며, 이를 통해 생산 능력 확대 계획이 유지되고 있습니다.
황산 공급 부족이 비용을 상승시켜
침전 실리카의 합성에는 제품 1톤당 0.3-0.4톤의 황산이 필요합니다. 2024년 미국의 원소 황 생산량은 5% 감소한 820만 톤을 기록했으며, 이로 인해 탬파의 계약 황산 가격은 2024년 1분기 69달러/톤에서 연말에는 116달러/톤으로 68% 급등했습니다. 중국에서는 제련소의 가동 중단과 수출 규제로 인해 현물 가격이 더욱 급등했습니다. 각 생산사는 유황 회수를 위한 수직 통합을 검토하고 있지만, 재생 플랜트 건설 비용은 5,000만 달러 이상 소요되며 투자 회수에는 5년 이상이 걸립니다. 이러한 높은 비용은 특히 범용 분말 등급에서 매출 총이익률을 압박하고 있으며, 침전 실리카 시장에서의 단기적인 투자 의욕을 위축시키고 있습니다.
부문별 분석
2025년, 고무용 실리카는 판매량의 55.12%를 차지하며, 저회전저항 타이어 트레드에서의 확고한 용도를 반영하고 있습니다. 식품용 실리카의 판매량은 규모는 작지만, 전 세계 브랜드 소유주들이 클린 라벨의 고결 방지제를 채택하고 있으며, 2031년까지 연평균 성장률(CAGR) 4.56%로 성장하고 있으며, 이는 모든 등급 중 가장 빠른 속도입니다. 치과용 실리카 연마재는 신흥 국가에서의 치약 보급률 상승에 힘입어 2025년에는 약 5억 달러에 달했습니다. 이러한 추세로 인해 고무용 등급의 판매량은 높은 수준을 유지하고 있지만, 추가적인 성장은 식품 및 구강 관리와 같은 틈새 시장에서 점점 더 많이 발생하고 있으며, 침전 실리카 시장 내의 수입원이 다양화되고 있습니다.
안정적인 규제 체계, 즉 FDA의 GRAS 규정(21 CFR 172.480) 및 EFSA의 2018년 견해에 따라 식품 가공업체의 배합 변경 위험이 감소하여 이 등급의 확장을 지원하고 있습니다. 한편, 왕겨재를 원료로 사용하는 사례는 바이오매스 유래 제조 공정에서도 타이어용 등급의 비표면적을 실현할 수 있음을 보여주고 있으며, 습식 공정을 통한 기존 제품과의 비용 격차를 좁히고 있습니다. 2031년까지 식품 및 구강 관리용 등급을 합치면 특수 용도용 침전 실리카 시장 규모의 3분의 1에 육박할 가능성이 있으며, 고무 컴파운드 분야에서 기존에 누려왔던 우위성에 도전장을 내밀게 될 것입니다.
분말은 고무나 플라스틱에 분산되기 쉬워 2025년 출하량의 48.31%를 차지했습니다. 반면, 비드는 균일한 구형 모양이 거칠어짐을 방지하고 유동성을 유지할 수 있으므로 치약 및 화장품용 젤에 대한 수요를 배경으로 연평균 성장률(CAGR) 6.34%로 성장하고 있습니다. 라인당 500만-1,000만 달러 규모의 분무 건조 설비 투자를 통해 대만, 일본, 인도의 비드 생산 능력이 확대되고, 공급망 리드타임이 단축되고 있습니다. 분말은 계속해서 주력 제품으로 남을 것이지만, 무기 실리카가 폴리머 규제 대상에서 제외된 마이크로플라스틱 규제의 지원을 받아 비즈는 침전 실리카 시장의 프리미엄 하위 부문을 개발할 전망입니다.
균일한 입자 형태로 인해 비드는 유럽의 마이크로비드 대체재 요건을 충족하고 있으며, 구강 관리 브랜드들은 빠른 용해 속도를 내세운 마케팅 전략을 적극적으로 전개하고 있습니다. 과립은 계속해서 농업용 블렌드에 활용되고 있으며, 마이크로펄은 화장품 및 코팅 분야의 틈새 시장에서 입지를 다지고 있습니다. 그 결과, 2031년까지 비즈가 형태별 매출의 20%를 초과할 가능성이 있으며, 이에 따라 매출 구성이 변화하고 침전 실리카 시장 전체의 평균 판매 가격이 상승할 것으로 전망됩니다.
지역별 분석
아시아태평양은 2025년 판매량의 50.24%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 3.95%를 기록할 것으로 전망됩니다. 2025년 중국의 전기자동차(EV) 생산 대수 950만 대가 이 지역의 타이어용 실리카 수요를 지원하는 한편, 중국, 인도, 태국의 왕겨재 프로젝트가 저비용 공급원을 개발하고 있습니다. 일본과 한국에서는 실리카를 이용한 보강을 의무화하는 엄격한 타이어 라벨 규정이 시행되고 있으며, 해당 지역의 실리카 보급률은 70%를 초과하고 있습니다. 에보닉(Evonik)의 맵 타 푸트(Map Ta Put) 사업 등 태국내 바이오매스 관련 제휴는 원료의 안정적인 공급과 탄소 중립을 향한 노력을 강화하고 있습니다. 이러한 기세에 힘입어 아시아는 침강성 실리카 시장의 투자 사이클에서 계속해서 핵심적인 위치를 차지하고 있습니다.
북미 및 유럽에서는 2026년 1월에 가동을 시작하는 에보닉사의 찰스턴 공장 확장으로 습식 공정의 생산 능력이 50% 증대되어, 증가하는 전기자동차용 타이어 수주에 대응할 수 있게 되었습니다. 한편, 케메티카(Kemetica)가 PPG의 자산을 인수함에 따라 레이크찰스와 델프자일 거점에서 연간 20만 톤의 생산 능력이 추가되었습니다. EU의 타이어 라벨 규제 강화 및 미세 플라스틱 금지 조치로 인해 자동차 및 퍼스널 케어 분야 모두에서 실리카 대체가 가속화되고 있습니다. 그러나 황산 가격의 급등이 유럽 및 미국의 생산자들에게 큰 부담으로 작용하고 있으며, 침전 실리카 시장 전체의 비용 구조 격차가 두드러지고 있습니다.
남미, 중동 및 아프리카에서는 국지적인 성장이 관찰됩니다. 브라질의 타이어 산업은 2024년 자동차 판매 대수 210만 대를 배경으로 회복세를 보이며, 현지 수요를 지원하고 있습니다. 아르헨티나의 비료 혼합 업체들은 유동제로 실리카를 채택하고 있는 반면, 걸프협력회의(GCC) 회원국들은 특수 실리카를 하류 석유화학 클러스터로 후방 통합하는 것을 목표로 하고 있습니다. 아시아에서 발생하는 물류 비용은 대개 톤당 100-150달러의 추가 비용으로 작용하여, 기존 습식 공정 공급업체를 보호하는 요인이 되고 있습니다. 따라서 이러한 지역들은 침전 실리카 시장의 동향에서 전략적인 제2의 성장 기회로 자리매김하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.08According to Mordor Intelligence, the precipitated silica market size is expected to increase from 3.25 Million tons in 2025 to 3.38 Million tons in 2026 and reach 4.08 Million tons by 2031, growing at a CAGR of 3.86% over 2026-2031.
This report is Segmented by Grade (Rubber, Food, Feed, and Others), Form (Powder, Beads, Micro-Pearls, and Granules), Production Process (Wet and Dry), End-Use Industry (Agriculture, Oral Care and Cosmetics, Tire, Electronics, and More), and Geography (Asia-Pacific, North America, Europe, South America, and the Middle East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Precipitated Silica Market Trends and Insights
Electrification-Driven Demand for Silica-Enhanced EV Tires
Instant torque and heavier battery packs make EV tires wear faster, yet range targets force automakers to curb rolling resistance. Raising precipitated silica loadings from 10-15 phr to 20-30 phr cuts hysteresis by up to 25% while preserving grip. China built 9.5 million battery-electric and plug-in hybrid vehicles in 2025, each consuming four to five tires with silica content 40-60% higher than combustion models, equating to roughly 50,000-70,000 t of incremental annual demand locally. Tightened EU tire-labeling thresholds that took effect mid-2024 reinforce the shift, and North American OEMs have adopted similar procurement specs, embedding silica into baseline tire designs irrespective of oil-price swings. The trend locks in structural growth for the precipitated silica market, encouraging producers to invest in dedicated EV-grade capacity across all regions.
Regulatory Push for Low-Rolling-Resistance Green Tires
Corporate Average Fuel Economy rules set 49 mpg targets for model-year 2026 passenger cars in the United States, compelling automakers to mandate low-rolling-resistance tires that can deliver 3-5% fuel savings. ASTM F2493 test procedures and ISO 28580 harmonization let tire makers validate silica formulations consistently worldwide. Japan and South Korea award top tire-label grades only for rolling-resistance coefficients under 9.0, a level nearly unreachable without silica reinforcement, and both markets exceeded 70% silica penetration in passenger-car tires during 2025. These synchronized policies form a compliance floor that shields the precipitated silica market from short-term price cycles, thereby sustaining capacity-expansion pipelines.
Tight Sulfuric-Acid Supply Inflating Costs
Precipitated silica synthesis needs 0.3-0.4 t of sulfuric acid per tonne of product. US elemental sulfur output slid 5% to 8.2 million t in 2024, driving Tampa contract acid prices from USD 69/t in Q1 2024 to USD 116/t by year-end, a 68% surge. Chinese spot prices climbed even faster due to smelter shutdowns and export curbs. Producers weigh backward integration into sulfur recovery, yet regeneration plants cost more than USD 50 million, and paybacks stretch past five years. These cost spikes compress gross margins, particularly for commodity powder grades, and temper near-term investment appetite in the precipitated silica market.
Other drivers and restraints analyzed in the detailed report include:
- Food-Grade Silica Uptake in Clean-Label Formulations
- Rice-Husk-Ash Circular-Economy Silica Scale-Up
- Automotive OEM Production-Cycle Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rubber-grade silica held 55.12% of volume in 2025, reflecting entrenched use in low-rolling-resistance tire tread. Food-grade volumes, though smaller, are growing at 4.56% CAGR through 2031, the fastest among all grades, as global brand owners adopt clean-label anti-caking agents. Dental-silica abrasives reached about USD 500 million in 2025, backed by rising toothpaste penetration in emerging economies. These dynamics keep rubber volumes high, yet incremental growth increasingly stems from food and oral-care niches, diversifying revenue streams inside the precipitated silica market.
Steady regulatory frameworks, the FDA's GRAS rule 21 CFR 172.480, and EFSA's 2018 opinion, lower reformulation risk for food processors, underpinning the grade's expansion. Meanwhile, rice-husk-ash feedstock demonstrates that biomass routes can deliver tire-grade surface areas, narrowing cost gaps with wet-process incumbents. By 2031, food and oral-care grades together could approach one-third of the precipitated silica market size for specialty applications, challenging the traditional dominance of rubber compounds.
Powder accounted for 48.31% of 2025 shipments because it disperses easily into rubber and plastics. Beads, however, are advancing at 6.34% CAGR on the back of toothpaste and cosmetic gel demand, where uniform spheres prevent grit and maintain flow. Spray-drying investments of USD 5-10 million per line have lifted bead capacity across Taiwan, Japan, and India, trimming supply-chain lead times. Powder will remain the workhorse, yet beads are set to carve a premium sub-segment of the precipitated silica market, bolstered by microplastics regulations that exclude inorganic silica from polymer restrictions.
Consistent particle morphology allows beads to meet European microbead replacements, and oral-care brands capitalize on marketing claims around faster dissolution. Granules continue serving agricultural blends, while micro-pearls hold niche cosmetic and coating positions. As a result, beads could exceed 20% of form sales by 2031, shifting revenue mix and raising average selling prices across the precipitated silica market.
Complete Report Scope:
- By Grade
- Rubber Grade
- Food Grade
- Dental/Oral-Care Grade
- Feed Grade
- Others (Battery-Separator Grade and Technical/Industrial Grade)
- By Form
- Powder
- Beads
- Micro-pearls
- Granules
- By Production Process
- Wet Process
- Dry Process
- By End-use Industry
- Agriculture
- Oral Care and Cosmetics
- Tire
- Electronics
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific retained 50.24% of 2025 volume and is set for 3.95% CAGR through 2031. China's 9.5 million EV output in 2025 underpins local tire-grade silica demand, while rice-husk-ash projects across China, India, and Thailand unlock low-cost supply. Japan and South Korea enforce stringent tire-label grades that require silica reinforcement, pushing regional penetration above 70%. Thai biomass tie-ups, such as Evonik's Map Ta Phut venture, enhance feedstock security and carbon credentials. This momentum keeps Asia at the core of the precipitated silica market investment cycle.
In North America and Europe, Evonik's Charleston expansion, operational in January 2026, boosts wet-process capacity by 50% to serve rising EV-tire orders, while Qemetica's purchase of PPG's assets added 200,000 t pa across Lake Charles and Delfzijl. EU tire-label tightening and microplastics bans accelerate silica substitution in both automotive and personal-care channels. However, sulfuric-acid price inflation weighs on European and US producers, highlighting cost-structure disparities across the precipitated silica market.
South America and the Middle East & Africa show selective growth pockets. Brazil's tire industry recovered alongside 2.1 million vehicle sales in 2024, spurring local demand. Argentina's fertilizer blenders employ silica as a flow agent, while Gulf Cooperation Council nations aim to backward-integrate specialty silica into downstream petrochemicals clusters. Logistics costs from Asia often add USD 100-150/t, protecting entrenched wet-process suppliers. These regions thus remain strategic second-tier opportunities within the precipitated silica market landscape.
- Antenchem
- Cabot Corporation
- Denka Company Limited
- Evonik Industries AG
- FUJI SILYSIA CHEMICAL LTD.
- Huber Engineered Materials
- Jinsha Precipitated Silica Manufacturing Co., Ltd.
- Kadvani Chemicals Pvt. Ltd.
- Madhu Silica Pvt. Ltd.
- Oriental Silicas Corporation
- Qemetica
- Quechen Silicon Chemical
- Solvay
- Sunshine Industries
- Tata Chemicals Ltd.
- Tokuyama Corporation
- Tosoh Silica Corporation
- W. R. Grace & Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Electrification-driven demand for silica-enhanced EV tyres
- 4.2.2 Regulatory push for low-rolling-resistance "green" tyres
- 4.2.3 Food-grade silica uptake in clean-label formulations
- 4.2.4 Rice-husk-ash circular-economy silica scale-up (Asia)
- 4.2.5 High-purity silica for Li-ion battery separators
- 4.3 Market Restraints
- 4.3.1 Tight sulphuric-acid supply inflating costs
- 4.3.2 Automotive OEM production-cycle volatility
- 4.3.3 Consumer backlash on silica micro-plastics (personal care)
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Grade
- 5.1.1 Rubber Grade
- 5.1.2 Food Grade
- 5.1.3 Dental/Oral-Care Grade
- 5.1.4 Feed Grade
- 5.1.5 Others (Battery-Separator Grade and Technical/Industrial Grade)
- 5.2 By Form
- 5.2.1 Powder
- 5.2.2 Beads
- 5.2.3 Micro-pearls
- 5.2.4 Granules
- 5.3 By Production Process
- 5.3.1 Wet Process
- 5.3.2 Dry Process
- 5.4 By End-use Industry
- 5.4.1 Agriculture
- 5.4.2 Oral Care and Cosmetics
- 5.4.3 Tire
- 5.4.4 Electronics
- 5.4.5 Other End-user Industries
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 Italy
- 5.5.3.4 France
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Antenchem
- 6.4.2 Cabot Corporation
- 6.4.3 Denka Company Limited
- 6.4.4 Evonik Industries AG
- 6.4.5 FUJI SILYSIA CHEMICAL LTD.
- 6.4.6 Huber Engineered Materials
- 6.4.7 Jinsha Precipitated Silica Manufacturing Co., Ltd.
- 6.4.8 Kadvani Chemicals Pvt. Ltd.
- 6.4.9 Madhu Silica Pvt. Ltd.
- 6.4.10 Oriental Silicas Corporation
- 6.4.11 Qemetica
- 6.4.12 Quechen Silicon Chemical
- 6.4.13 Solvay
- 6.4.14 Sunshine Industries
- 6.4.15 Tata Chemicals Ltd.
- 6.4.16 Tokuyama Corporation
- 6.4.17 Tosoh Silica Corporation
- 6.4.18 W. R. Grace & Co.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment