|
시장보고서
상품코드
2125338
미국의 밸브 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Valves - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
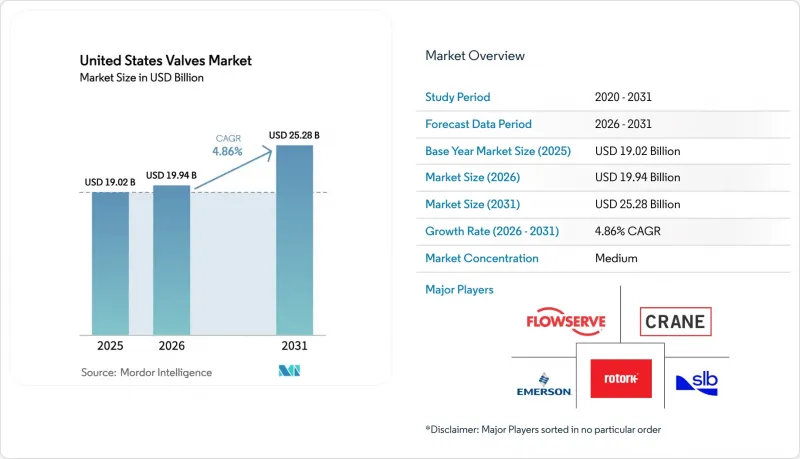
에 의하면, 미국의 밸브 시장 규모는 2025년 190억 2,000만 달러로 평가되었고, 2026년에는 199억 4,000만 달러로 추정되고, 2026-2031년 CAGR 4.86%로 성장을 지속할 전망이며, 2031년에는 252억 8,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 유형별(볼 밸브, 버터플라이 밸브, 게이트 밸브, 글로브 밸브, 체크 밸브, 플러그 밸브, 제어 밸브 등), 재질별(강, 주철, 합금계, 플라스틱 등), 작동 방식별(수동, 공압, 전동, 유압 등), 최종 사용자 산업별(석유 및 가스, 발전 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
미국의 밸브 시장 동향 및 인사이트
셰일 오일 재파쇄 활동의 급속한 확대가 밸브 교체 수요를 견인
재파쇄 작업으로 인해 밸브의 수명이 18-24개월에서 12-15개월로 단축되면서, 퍼미안 분지 및 기타 셰일 자원의 주요 산지에서 애프터마켓 수요가 꾸준히 증가하고 있습니다. 10,000 psi를 초과하는 압력 사이클에는 밀봉 성능과 내식성이 강화된 고성능 설계가 필수적입니다. 애프터마켓 공급업체는 교체 빈도 증가로 혜택을 보는 한편, OEM 업체들은 소재 등급 향상 및 서비스 계약을 통해 부가가치를 창출하고 있습니다. 재주입 빈도가 높아짐에 따라, 다단계 처리 과정에서 유량을 조절할 수 있는 제어 밸브에 대한 수요도 증가하고 있습니다. 신속한 도입을 위한 제품 인증을 획득할 수 있는 공급업체는 시간적 제약이 엄격한 이 환경에서 경쟁 우위를 확보하게 됩니다.
상수도 인프라 현대화를 위한 연방 자금 투입 가속화
‘인프라 투자 및 고용법’에서는 상수도 시스템에 550억 달러가 배정되었으며, 그 대부분은 30-50년 전에 가동을 시작한 노후화된 밸브의 교체를 대상으로 하고 있습니다. 지자체는 누수 감지 효율화와 규제 준수를 철저히 하기 위해 스마트하고 무연이며 원격 조정이 가능한 밸브를 우선적으로 도입하고 있습니다. EPA(미국 환경보호청)의 회전 기금이 연방 정부의 보조금을 보완하여 2030년까지 안정적인 프로젝트 공급을 보장하고 있습니다. 밸브, 액추에이터, 모니터링 소프트웨어를 포함한 턴키 패키지를 제공하는 공급업체는 특히 교체가 시급한 북동부 및 중서부 지역에서 더 높은 이익률을 확보하고 있습니다. 조달 주기가 장기화됨에 따라, 지자체에서 실적이 입증된 공급업체가 유리한 입장에 있습니다.
철강·합금 가격 변동이 OEM의 이익률을 압박
2024년, 철강 현물 가격은 40-60% 변동하여 장기 계약을 체결한 밸브 제조업체의 이익률을 압박했습니다. 헤지 프로그램이 없는 중소기업은 수익 변동에 취약하며, 경우에 따라 대체 재료를 사용한 제품 재설계를 강요당하기도 합니다. 추가 요금 조항이나 지수 연동형 가격 책정은 대기업이 가격 변동의 영향을 상쇄하는 데 도움이 되지만, 이를 도입하려면 고객과의 협상이나 시스템 업데이트가 필요합니다. 가격 변동은 재고 계획도 복잡하게 만들고, 운전 자본 수요를 높이며, 혁신에 대한 투자를 지연시킬 가능성도 있습니다.
부문 분석
2025년, 게이트 밸브는 미국 밸브 시장 점유율의 27.24%를 차지했습니다. 이는 완전한 차단이 필수적인 파이프라인이나 상수도망에서 그 사용이 정착되어 있음을 반영합니다. 확립된 사양 덕분에 많은 엔지니어링 표준에서 기본 선택지로 자리 잡고 있으며, 이는 교체 수요의 안정성을 뒷받침하고 있습니다. 버터플라이 밸브는 연평균 성장률(CAGR) 5.05%로 성장세를 보이고 있으며, HVAC(난방·환기·공조) 및 자동화된 공정 라인에서 컴팩트한 설치 면적과 신속한 쿼터턴 작동이 높이 평가되고 있습니다. 시설 소유자들이 에너지 효율과 원격 제어를 우선시함에 따라, 미국 내 버터플라이 밸브 시장 규모는 확대되고 있습니다. 글로브 밸브와 체크 밸브는 유량 조절 및 역류 방지의 대표 제품으로 자리 잡은 반면, 제어 밸브는 정밀도 요구 사항에 힘입어 고부가가치의 틈새 시장을 차지하고 있습니다. 적층 가공를 통한 시제품 제작이 보편화되면서 신속한 맞춤 제작이 가능해졌지만, 비용과 내구성 측면에서 대규모 생산에는 여전히 기존의 주조 방식이 선호되고 있습니다.
엔지니어링 팀은 구매 가격보다 총 설치 비용을 중시하는 경향이 강해지고 있어, 경량화를 통해 구조 비용과 작동 비용을 절감할 수 있는 버터플라이 밸브가 혜택을 보고 있습니다. 한편, 게이트 밸브는 견고한 웨지 씰과 풀 보어 유로를 갖추고 있어 부식성 또는 마모성이 강한 환경에서 여전히 우위를 유지하고 있습니다. 디지털 위치 피드백을 통한 개조를 통해 기존 게이트 밸브를 플랜트의 DCS 플랫폼에 통합할 수 있게 되어, 수명이 연장될 뿐만 아니라 최신 모니터링 전략에도 대응할 수 있게 됩니다. 통합된 자산 관리 소프트웨어를 통해 게이트 밸브와 버터플라이 밸브가 혼재된 설비군을 지원할 수 있는 공급업체는 유지보수 계약을 수주함으로써 미국 밸브 시장에서 고객 충성도를 높이고 있습니다.
2025년에는 철강 제품이 40.88%의 시장 점유율을 차지했습니다. 이는 업스트림 에너지 및 화학 처리 용도에 필수적인 높은 인장 강도와 내열성에 의해 뒷받침되고 있습니다. 야금 기술과 코팅 기술의 향상으로 고장 간격(MTBF)이 연장되어, 중요한 용도에서 강재의 역할이 확보되고 있습니다. 플라스틱 밸브는 내식성과 설치 시의 경량성을 바탕으로 수처리 및 특정 화학 공정 분야에서 수요가 확대되고 있으며, 연평균 성장률(CAGR) 4.92%라는 가장 높은 성장률을 보이고 있습니다. 유틸리티자가 납 배관 교체 의무를 이행함에 따라 미국의 플라스틱 밸브 시장 규모는 더욱 확대될 것으로 예측됩니다.
유틸리티 사업자는 수명 주기 비용을 신중하게 검토하고 있으며, 부식으로 인해 강철 배관을 빈번하게 교체해야 하는 저압 배관의 경우, 많은 경우 플라스틱 제품을 선택하고 있습니다. 플라스틱 라이닝을 적용한 강철 본체와 같은 하이브리드 솔루션은 강도와 내화학성의 균형을 맞추어 중압 범위에서 시장 점유율을 확보하고 있습니다. 합금계 소재는 원자력 및 항공우주 분야와 같은 가혹한 환경에서 여전히 우위를 유지하고 있지만, 생산량이 제한적이어서 시장 점유율은 제한적입니다. 주철은 기존의 도시 인프라 시스템에서 계속 사용되고 있지만, 무게나 부식 등의 단점으로 인해 사용량은 점차 감소하고 있습니다. 특히 수소 서비스 도입에 따라 새로운 적합성 문제가 대두되고 있는 만큼, 점점 더 엄격해지는 환경 기준 및 성능 기준을 충족하기 위해서는 소재 혁신이 여전히 매우 중요합니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJYAccording to Mordor Intelligence, the US valves market size is expected to grow from USD 19.02 billion in 2025 to USD 19.94 billion in 2026 and is forecast to reach USD 25.28 billion by 2031 at 4.86% CAGR over 2026-2031.
This report is Segmented by Type (Ball Valve, Butterfly Valve, Gate Valve, Globe Valve, Check Valve, Plug Valve, Control Valve, and More), Material (Steel, Cast Iron, Alloy-Based, Plastic, and More), Actuation Method (Manual, Pneumatic, Electric, Hydraulic, and More), End-User Industry (Oil and Gas, Power Generation, and More), and Region. The Market Forecasts are Provided in Terms of Value (USD).
United States Valves Market Trends and Insights
Rapid Shale-Oil Refracturing Activity Boosting Valve Replacements
Refracturing campaigns shorten valve lifecycles from 18-24 months to 12-15 months, driving steady aftermarket demand in Permian and other shale hotspots. Pressure cycling above 10,000 psi necessitates premium designs with enhanced sealing and corrosion resistance. Aftermarket providers benefit from higher replacement frequency, while OEMs capture value through upgraded materials and service agreements. Rising refracturing intensity also spurs demand for control valves that can modulate flow during multi-stage treatments. Suppliers able to certify products for rapid deployment gain a competitive edge in this time-sensitive environment.
Accelerating Federal Funding for Water Infrastructure Modernization
The Infrastructure Investment and Jobs Act allocates USD 55 billion for water systems, much of which targets aging valves that entered service 30-50 years ago. Municipalities prioritize smart, lead-free, and remotely actuated valves to increase leak detection efficiency and regulatory compliance. EPA revolving funds supplement federal grants, ensuring a steady pipeline of projects through 2030. Suppliers offering turnkey packages, including valves, actuators, and monitoring software, capture higher margins, especially in the Northeast and Midwest, where replacement urgency is acute. Long procurement cycles favor vendors with proven municipal references.
Steel and Alloy Price Volatility Squeezing OEM Margins
Spot steel prices fluctuated 40-60% in 2024, compressing margins for valve makers locked into long-term contracts. Smaller companies lacking hedging programs face greater earnings swings, sometimes redesigning products with alternative materials. Surcharge clauses and index-based pricing help larger firms offset volatility, but implementation requires customer negotiation and system updates. Volatility also complicates inventory planning, raising working capital requirements and potentially delaying innovation spending.
Other drivers and restraints analyzed in the detailed report include:
- Industrial IoT-Enabled Predictive Maintenance Adoption
- Hydrogen-Ready Valve Design Standards Emerging
- Skills Gap in Smart-Valve Commissioning and Maintenance
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Gate valves held 27.24% of the U.S. valve market share in 2025, reflecting their entrenched use in pipelines and water networks, where tight shut-off is mandatory. Their established specifications make them the default choice in many engineering standards, supporting steady demand for replacement. Butterfly valves gain momentum with a 5.05% CAGR, prized for compact footprints and fast quarter-turn operation in HVAC and automated process lines. The U.S. valves market size for butterfly designs grows as facility owners prioritize energy efficiency and remote control. Globe and check valves remain staples for throttling and backflow prevention, while control valves occupy higher-value niches driven by precision requirements. Growth in additive manufacturing prototypes enables rapid customization; however, large-scale production still favors traditional casting due to cost and durability considerations.
Engineering teams are increasingly evaluating total installed cost rather than purchase price, benefiting butterfly valves where weight savings reduce structural and actuation expenses. Conversely, gate valves maintain dominance in corrosive or abrasive services by offering robust wedge seals and full-bore flow paths. Digital position feedback retrofits allow legacy gate valves to integrate with plant DCS platforms, extending service life and aligning with modern monitoring strategies. Vendors that can support mixed fleets of gate and butterfly valves through unified asset-management software win maintenance contracts, thereby deepening customer stickiness in the U.S. valves market.
Steel products held a 40.88% market share in 2025, underpinned by their high tensile strength and temperature tolerance, which are essential for upstream energy and chemical processing applications. Improved metallurgy and coatings extend mean time between failure, safeguarding steel's role in critical services. Plastic valves grow at the fastest rate, with a 4.92% CAGR, driven by their corrosion resistance and lower installation weight in water treatment and certain chemical processes. The U.S. valves market size for plastics is expected to expand further as utilities address lead-replacement mandates.
Utilities weigh lifecycle costs, often selecting plastic for low-pressure lines where corrosion drives frequent steel replacement. Hybrid solutions, such as plastic-lined steel bodies, strike a balance between strength and chemical resistance, capturing a share of the mid-pressure range. Alloy-based materials maintain a premium position in extreme environments, such as nuclear and aerospace applications, although limited volumes restrict their market share. Cast iron continues to serve legacy municipal systems, but its use is slowly declining due to its weight and corrosion drawbacks. Material innovations remain pivotal to meeting increasingly stringent environmental and performance standards, especially as the introduction of hydrogen services presents new compatibility challenges.
Complete Report Scope:
- By Type
- Ball Valve
- Butterfly Valve
- Gate Valve
- Globe Valve
- Check Valve
- Plug Valve
- Control Valve
- Other Types
- By Material
- Steel
- Cast Iron
- Alloy-Based
- Plastic
- Other Materials
- By Actuation Method
- Manual
- Pneumatic
- Electric
- Hydraulic
- Other Actuation Methods
- By End-User Industry
- Oil and Gas
- Power Generation
- Chemical
- Water and Wastewater
- Mining
- Food and Beverage
- Pharmaceuticals
- Other End-User Industries
- By Region
- Northeast
- Midwest
- South
- West
List of Companies Covered in this Report:
- Emerson Electric Co.
- Schlumberger Limited
- Flowserve Corporation
- Crane Company
- Rotork plc
- Bray International, Inc.
- KITZ Corporation
- Parker-Hannifin Corporation
- Curtiss-Wright Corporation
- Watts Water Technologies, Inc.
- AVK Holding A/S
- Velan Inc.
- Johnson Controls International plc
- Honeywell International Inc.
- Spirax-Sarco Engineering plc
- Pentair plc
- Cameron (SLB)
- AUMA Riester GmbH and Co. KG
- Samson Aktiengesellschaft
- Swagelok Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Shale-Oil Refracturing Activity Boosting Valve Replacements
- 4.2.2 Accelerating Federal Funding for Water Infrastructure Modernization
- 4.2.3 Industrial IoT-Enabled Predictive Maintenance Adoption
- 4.2.4 Hydrogen-Ready Valve Design Standards Emerging
- 4.2.5 Federal Investment Tax Credits for Carbon-Capture Projects
- 4.2.6 Growth of Modular Data Centers Requiring Precision Cooling Valves
- 4.3 Market Restraints
- 4.3.1 Steel and Alloy Price Volatility Squeezing OEM Margins
- 4.3.2 Skills Gap in Smart-Valve Commissioning and Maintenance
- 4.3.3 Import Tariffs on Specialty Valve Castings
- 4.3.4 Cybersecurity Concerns Slowing Connected-Valve Deployments
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Assessment of Impact of COVID-19
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Ball Valve
- 5.1.2 Butterfly Valve
- 5.1.3 Gate Valve
- 5.1.4 Globe Valve
- 5.1.5 Check Valve
- 5.1.6 Plug Valve
- 5.1.7 Control Valve
- 5.1.8 Other Types
- 5.2 By Material
- 5.2.1 Steel
- 5.2.2 Cast Iron
- 5.2.3 Alloy-Based
- 5.2.4 Plastic
- 5.2.5 Other Materials
- 5.3 By Actuation Method
- 5.3.1 Manual
- 5.3.2 Pneumatic
- 5.3.3 Electric
- 5.3.4 Hydraulic
- 5.3.5 Other Actuation Methods
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Power Generation
- 5.4.3 Chemical
- 5.4.4 Water and Wastewater
- 5.4.5 Mining
- 5.4.6 Food and Beverage
- 5.4.7 Pharmaceuticals
- 5.4.8 Other End-User Industries
- 5.5 By Region
- 5.5.1 Northeast
- 5.5.2 Midwest
- 5.5.3 South
- 5.5.4 West
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Emerson Electric Co.
- 6.4.2 Schlumberger Limited
- 6.4.3 Flowserve Corporation
- 6.4.4 Crane Company
- 6.4.5 Rotork plc
- 6.4.6 Bray International, Inc.
- 6.4.7 KITZ Corporation
- 6.4.8 Parker-Hannifin Corporation
- 6.4.9 Curtiss-Wright Corporation
- 6.4.10 Watts Water Technologies, Inc.
- 6.4.11 AVK Holding A/S
- 6.4.12 Velan Inc.
- 6.4.13 Johnson Controls International plc
- 6.4.14 Honeywell International Inc.
- 6.4.15 Spirax-Sarco Engineering plc
- 6.4.16 Pentair plc
- 6.4.17 Cameron (SLB)
- 6.4.18 AUMA Riester GmbH and Co. KG
- 6.4.19 Samson Aktiengesellschaft
- 6.4.20 Swagelok Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment