|
시장보고서
상품코드
2125342
기업용 증강현실 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Enterprise Augmented Reality - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
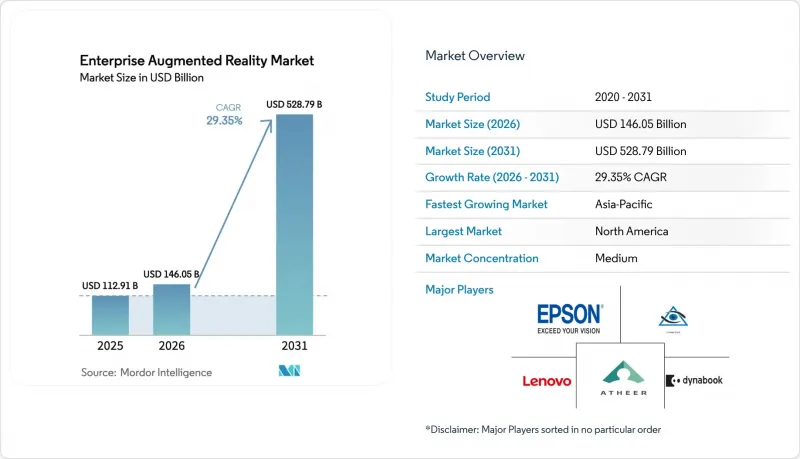
에 의하면, 기업용 증강현실 시장 규모는 2025년에 1,129억 1,000만 달러로 평가되었고, 2026년 1,460억 5,000만 달러에서 2031년까지 5,287억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 29.35%를 나타낼 전망입니다.
본 보고서는 구성 요소별(하드웨어, 소프트웨어, 서비스), 배포별(온프레미스, 클라우드/ARaaS), 기기별(헤드마운트형/스마트 글래스, 기타), 용도별(원격 지원·협업, 교육·시뮬레이션, 기타), 최종 사용자별(산업 제조, 자동차 및 항공우주, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 기업용 증강현실 시장 동향 및 인사이트
신속한 ROI 입증이 가능한 산업용 파일럿 프로그램
파일럿 프로젝트가 꾸준한 비용 절감과 생산성 향상을 가져오기 때문에 기업들은 개념 증명(PoC) 단계를 넘어섰습니다. 포드사의 디어본 엔진 공장에서는 기술자에게 HoloLens 2를 배치하여, 당초 25명의 직원을 교육한 후 연말까지 100명으로 확대할 계획을 추진하고 있으며, 측정 가능한 품질 향상을 기록했습니다. 이와 유사한 창고 프로그램을 통해 코카콜라의 사업장에서는 주문 피킹 정확도가 99.9%까지 향상되었습니다. 이러한 공개된 성공 사례는 사내 승인 주기를 단축하고 여러 사업장으로의 확장을 정당화하며, 엔터프라이즈용 AR 시장의 보급 곡선을 가속화하고 있습니다.
스마트폰 수준의 RISC-V 프로세서가 기기의 BOM을 대폭 절감
오픈소스 RISC-V 칩셋은 스마트폰 수준의 연산 능력을 훨씬 저렴한 부품 원가로 제공합니다. XREAL사의 X1 프로세서 덕분에 유선 연결이 필요한 기기가 불필요해졌으며, 이로 인해 XREAL사는 스마트글래스 가격을 499-599달러로 책정하면서도 매출 총이익률을 유지할 수 있게 되었습니다. 비용 절감으로 인해 대상 사용자층이 확대되고 대량 조달이 가능해집니다. 이는 비용에 민감한 산업 분야에서 기업용 증강현실 시장을 확대하기 위한 중요한 요인이 됩니다.
엣지 컴퓨팅의 보안 취약점
헤드셋, 온프레미스 게이트웨이, 클라우드 노드에 처리를 분산함으로써 공격 표면이 확대됩니다. 이는 독자적인 공정이나 위험 물질을 취급하는 공장에 있어 우려 사항이 됩니다. 많은 IT 팀에는 AR에 특화된 보안 대책 매뉴얼이 부족하며, 그 결과 제로 트러스트 아키텍처의 유효성이 입증될 때까지 도입이 지연되고 있습니다. 규정 준수 감사는 추가적인 부담을 초래하여, 기업용 증강현실 시장의 일부 수요 곡선을 일시적으로 둔화시키고 있습니다.
부문 분석
서비스 부문은 2026-2031년 연평균 성장률(CAGR) 33.20%로 확대될 것으로 예상되며, 기업이 도입, 사용자 교육, 가동 시간에 관한 SLA(서비스 수준 계약)를 통합 업체에 의존함에 따라 순수 제품 매출을 상회할 것으로 전망됩니다. 서비스 파트너들은 초기 하드웨어 시범 운영을 공장 전체로 확대하고 있으며, 이러한 추세가 엔터프라이즈 AR 시장에서 성과 기반 계약으로의 전환을 촉진하고 있습니다. AI를 활용한 작업 지시서 생성 등의 혁신을 통해 컨텐츠 제작이 자동화되고 도입 주기가 단축됩니다.
구성 요소의 변화는 시장의 성숙을 나타냅니다. 헤드셋 도입이 완료되면, 가치는 분석, 업데이트 주기, 지속적인 개선에 관한 컨설팅으로 이동합니다. 각 벤더는 소프트웨어 구독과 현장 변경 관리를 결합함으로써 지속적인 수익을 확보하고, 고객과의 관계를 심화하며, 엔터프라이즈 AR 시장 전체에서 장기적인 고객 유지율을 높이고 있습니다.
2025년에는 헤드마운트형 디바이스가 51.85%의 점유율을 유지했지만, 공장에서 협업을 위해 공유 3D 작업 공간을 도입함에 따라 프로젝션 및 공간 디스플레이 시스템은 연평균 성장률(CAGR) 36.10%라는 급속한 성장을 이루고 있습니다. 프로젝션은 착용감에 대한 우려를 해소하기 때문에 작업자 훈련 구역, 적층 가공 셀, 팀이 공통의 참조 대상을 둘러싸고 모이는 품질 검사실 등에서 선호되고 있습니다. 인더스트리 4.0 시범 프로젝트에서는 공간형 설정을 통해 설계 검토 시간이 단축되고 수정 루프가 감소하는 것이 확인되었습니다.
동시에 경량 광학 기술 연구로 헤드셋의 무게가 200g 미만으로 줄어들어, 1교대 근무 동안의 사용 적응 범위가 넓어지고 있습니다. 그 결과, 기업들은 다중 모드 툴킷을 채택하고 있습니다. 개별 기술자는 헤드 마운트 디스플레이를 착용하고, 감독자는 대규모 프로젝션을 활용함으로써, 기업용 증강현실 시장 전체에서 기기의 다양화가 집단적으로 가속화되고 있습니다.
지역별 분석
북미는 성숙한 IT 예산, 국방 수준의 규제 요건, OSHA에 의한 UL 8400 AR/VR 기기 안전 기준 채택을 배경으로 2025년 매출의 35.75%를 차지했습니다. 마이크로소프트와 앤드릴(Anduril)의 ‘통합 시각 증강 시스템(Integrated Visual Augmentation System)’ 공동 개발은 정부 주도로 상업 분야로 파급되고 있음을 보여줍니다. 이 지역의 견고한 개발자 생태계는 맞춤형 애플리케이션 개발을 가속화하여 기업용 증강현실 시장 전체에서 리더십을 강화하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 31.10%를 기록하며 가장 빠르게 성장하는 지역입니다. 중국에서만 2025년에 275만 대의 스마트 글라스가 출하된 것으로 평가되었으며, 이는 전년 대비 2배 이상 증가한 수치입니다. XREAL이 전 세계 AR 아이웨어 출하량의 51%를 차지하고 있다는 사실은 광학 제조 분야에서 이 지역의 부상을 여실히 보여줍니다. 공장 디지털화 및 5G 보급과 관련된 정부의 인센티브가 산업 회랑 전체로 확산되면서, 현지 시스템 통합사업자 및 하이퍼스케일 클라우드 제공업체와의 긴밀한 협력을 촉진하고 있습니다.
유럽에서는 ‘인더스트리 4.0’ 로드맵, ESG 관련 설비 투자, 엄격한 근로자 안전 지침에 힘입어 꾸준한 성장을 이루고 있습니다. 독일과 프랑스의 자동차 산업 클러스터에서는 모델 전환에 따른 위험을 완화하기 위해 협업형 AR이 채택되고 있으며, 해상 풍력 발전소에서는 유지보수 순서를 결정하기 위해 스페이셜 트윈이 도입되고 있습니다. 유럽 대륙에서는 상호 운용성 기준이 중시되고 있으며, 이에 따라 세계 프레임워크를 형성하고 기업용 증강현실 시장 전체의 조달에 영향을 미칠 가능성이 있는 벤더 간 컨소시엄이 부상하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the enterprise augmented reality market size was valued at USD 112.91 billion in 2025 and estimated to grow from USD 146.05 billion in 2026 to reach USD 528.79 billion by 2031, at a CAGR of 29.35% during the forecast period (2026-2031).
This report is Segmented by Component (Hardware, Software, and Services), Deployment (On-Premise, and Cloud/AR-as-a-Service), Device (Head-mounted/Smart-glasses, and More), Application (Remote Assistance and Collaboration, Training and Simulation, and More), End-User (Industrial Manufacturing, Automotive and Aerospace, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Enterprise Augmented Reality Market Trends and Insights
Rapid ROI-proof Industrial Pilot Programs
Enterprises move beyond proofs of concept because pilot projects consistently deliver hard savings and productivity lifts. Ford's Dearborn engine plant documented measurable quality gains after equipping technicians with HoloLens 2, training 25 workers initially and planning to scale to 100 by year-end. Similar warehouse programs pushed order-picking accuracy to 99.9% at Coca-Cola operations. These publicly reported successes shorten internal approval cycles and justify multi-site roll-outs, accelerating the enterprise augmented reality market's penetration curve.
Smartphone-class RISC-V Processors Slashing Device BOM
Open-source RISC-V chipsets provide smartphone-level compute at materially lower bill-of-materials. XREAL's X1 processor removed the need for tethered devices, letting the firm price its smart glasses at USD 499-599 and still sustain gross margins. Lower costs broaden the addressable user base and allow fleet-sized procurements, a critical lever for scaling the enterprise augmented reality market in cost-sensitive industrial segments.
Edge-compute Security Gaps
Distributing processing across headsets, on-premise gateways, and cloud nodes widens the attack surface, a concern for plants handling proprietary processes or hazardous materials. Many IT teams lack AR-specific security playbooks, resulting in delayed roll-outs until zero-trust architectures are proven. Compliance audits add further overhead, temporarily dampening some demand curves within the enterprise augmented reality market.
Other drivers and restraints analyzed in the detailed report include:
- Mainstream Shift to Head-mounted AR for Frontline Work
- 5G/Private-LTE Enabling Ultra-low-latency AR Streaming
- Legacy MES/PLM Integration Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The Services segment is projected to expand at 33.20% CAGR from 2026-2031, overtaking pure product revenue as firms lean on integrators for rollout, user training, and uptime SLAs. Services partners convert early hardware pilots into plant-wide deployments, a trend that underpins the enterprise augmented reality market's shift toward outcome-based contracting. Innovations such as AI-generated work instructions automate content creation and cut deployment cycles.
The component mix evolution signals maturation: once fleets of headsets are installed, value migrates to analytics, refresh cycles, and continuous improvement consulting. Vendors are bundling software subscriptions with on-site change-management to lock in recurring revenue and deepen client intimacy, reinforcing long-run stickiness across the enterprise augmented reality market.
Head-mounted units retained 51.85% share in 2025, but projection and spatial systems are sprinting at 36.10% CAGR as factories deploy shared 3D workspaces for collaborative tasks. Projection eliminates wearability concerns and is favored for operator training bays, additive-manufacturing cells, and quality cabins where teams gather around a common reference. Industry 4.0 pilots confirm that spatial setups shorten design reviews and cut rework loops.
Lightweight optics research is simultaneously reducing headset weight to under 200 g, widening suitability for shift-long use. Enterprises therefore adopt a multimodal toolkit: individual technicians wear head-mounted displays, while supervisors engage with large-scale projection, collectively accelerating device diversity across the enterprise augmented reality market.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Device Type
- Head-mounted / Smart-glasses
- Handheld / Mobile AR
- Projection / Spatial
- Others (HUD, Helmet-mounted)
- By Application
- Remote Assistance and Collaboration
- Training and Simulation
- Maintenance and Inspection
- Design and Visualization
- Sales and Marketing
- Workflow and Quality Control
- By End-User Industry
- Industrial Manufacturing
- Automotive and Aerospace
- Energy and Utilities
- Healthcare
- Retail and E-commerce
- Logistics and Warehousing
- Other End-user Industries (Public Safety, Agriculture)
- By Deployment
- On-premise
- Cloud / AR-as-a-Service
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Southeast Asia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America delivered 35.75% of 2025 revenue on the back of mature IT budgets, defense-grade mandates, and OSHA's inclusion of UL 8400 AR/VR equipment safety standards. Microsoft's collaboration with Anduril on the Integrated Visual Augmentation System illustrates government pull-through into commercial sectors. The region's robust developer ecosystem accelerates bespoke application creation, reinforcing leadership across the enterprise augmented reality market.
Asia-Pacific is the fastest-growing theatre at 31.10% CAGR. China alone is expected to ship 2.75 million smart-glasses units in 2025, more than doubling year on year. XREAL's 51% share of global AR eyewear shipments highlights regional ascendancy in optics manufacturing. Government incentives tied to factory digitalization and 5G coverage blanket industrial corridors, pulling local integrators and hyperscale cloud providers into tight alignment.
Europe posts steady gains, anchored by Industry 4.0 roadmaps, ESG-linked capex, and stringent worker-safety directives. Automotive clusters in Germany and France adopt collaborative AR to de-risk model transitions, while offshore wind farms deploy spatial twins for maintenance sequencing. The continent emphasizes interoperability standards, giving rise to cross-vendor consortia that could shape global frameworks and influence procurement across the enterprise augmented reality market.
- Microsoft Corporation
- PTC Inc. (Vuforia)
- Magic Leap Inc.
- Vuzix Corporation
- Lenovo Group Ltd.
- Google LLC (Glass Enterprise)
- Epson Corporation
- RealWear Inc.
- Rokid Inc.
- ThirdEye Gen Inc.
- Dynabook Americas Inc.
- Nextech AR Solutions Corp.
- Librestream Technologies Inc.
- TeamViewer AG (Frontline)
- Scope AR
- Trimble Inc.
- Qualcomm Technologies Inc.
- Zebra Technologies Corp.
- Apple Inc. (visionOS enterprise SDK)
- Atheer Inc.
- Plutomen Technologies Pvt Ltd.
- Dalux A/S
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid ROI-proof industrial pilot programs
- 4.2.2 Smartphone-class RISC-V processors slashing device BOM
- 4.2.3 Mainstream shift to head-mounted AR for frontline work
- 4.2.4 5G/Private-LTE enabling ultra-low-latency AR streaming
- 4.2.5 Under-the-radar: ESG-linked capex credits for AR training gear
- 4.2.6 Under-the-radar: OSHA digital-twin mandates for high-risk plants
- 4.3 Market Restraints
- 4.3.1 Edge-compute security gaps
- 4.3.2 Legacy MES/PLM integration costs
- 4.3.3 Under-the-radar: Short-staffed optical-waveguide supply chain
- 4.3.4 Under-the-radar: Growing patent-troll litigation on SLAM IP
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (AR-Cloud, Spatial-AI)
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Assessment of Macro Economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Device Type
- 5.2.1 Head-mounted / Smart-glasses
- 5.2.2 Handheld / Mobile AR
- 5.2.3 Projection / Spatial
- 5.2.4 Others (HUD, Helmet-mounted)
- 5.3 By Application
- 5.3.1 Remote Assistance and Collaboration
- 5.3.2 Training and Simulation
- 5.3.3 Maintenance and Inspection
- 5.3.4 Design and Visualization
- 5.3.5 Sales and Marketing
- 5.3.6 Workflow and Quality Control
- 5.4 By End-User Industry
- 5.4.1 Industrial Manufacturing
- 5.4.2 Automotive and Aerospace
- 5.4.3 Energy and Utilities
- 5.4.4 Healthcare
- 5.4.5 Retail and E-commerce
- 5.4.6 Logistics and Warehousing
- 5.4.7 Other End-user Industries (Public Safety, Agriculture)
- 5.5 By Deployment
- 5.5.1 On-premise
- 5.5.2 Cloud / AR-as-a-Service
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Russia
- 5.6.2.7 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia and New Zealand
- 5.6.3.6 Southeast Asia
- 5.6.3.7 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Chile
- 5.6.4.4 Rest of South America
- 5.6.5 Middle East
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 Israel
- 5.6.5.5 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Egypt
- 5.6.6.3 Nigeria
- 5.6.6.4 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 PTC Inc. (Vuforia)
- 6.4.3 Magic Leap Inc.
- 6.4.4 Vuzix Corporation
- 6.4.5 Lenovo Group Ltd.
- 6.4.6 Google LLC (Glass Enterprise)
- 6.4.7 Epson Corporation
- 6.4.8 RealWear Inc.
- 6.4.9 Rokid Inc.
- 6.4.10 ThirdEye Gen Inc.
- 6.4.11 Dynabook Americas Inc.
- 6.4.12 Nextech AR Solutions Corp.
- 6.4.13 Librestream Technologies Inc.
- 6.4.14 TeamViewer AG (Frontline)
- 6.4.15 Scope AR
- 6.4.16 Trimble Inc.
- 6.4.17 Qualcomm Technologies Inc.
- 6.4.18 Zebra Technologies Corp.
- 6.4.19 Apple Inc. (visionOS enterprise SDK)
- 6.4.20 Atheer Inc.
- 6.4.21 Plutomen Technologies Pvt Ltd.
- 6.4.22 Dalux A/S
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment