

|
시장보고서
상품코드
2125563
미국의 수소 생산 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United States Hydrogen Generation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
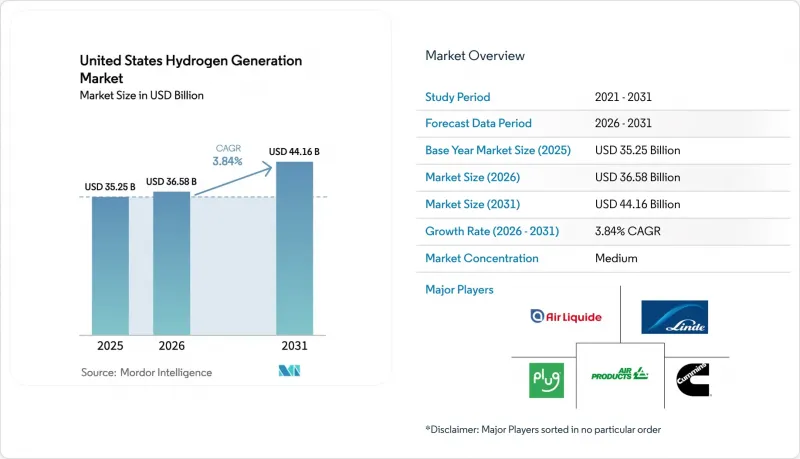
에 의하면, 미국 수소 생산 시장 규모는 2025년 352억 5,000만 달러, 2026년 365억 8,000만 달러에서 2031년까지 441억 6,000만 달러로 확대한다고 예측되고 있어 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 3.84%를 나타낼 전망입니다.

본 보고서는 원료별(그레이 수소, 블루 수소, 그린 수소, 터콰이즈 수소, 핑크 수소), 기술별(수증기 메탄 개질, 석탄 가스화, 자가열 개질, 부분 산화, 전기분해),용도별(석유 정제, 화학 처리, 철강, 운송용 연료, 전력 및 에너지 저장, 주거용·상업용 난방)로 분류되어 있습니다.
미국 수소 생산 시장 동향 및 인사이트
인플레이션 감축법(IRA)의 생산 세액 공제
2025년 1월에 시행되는 제45V조에서는 GREET 모델을 통해 검증된 수명 주기 배출량이 수소 1kg당 0.45kg CO2e 미만인 수소에 대해, 1kg당 최대 3달러의 세액 공제가 제공됩니다. 이 세액 공제는 10년간 양도 가능하며, 프로젝트의 가중 평균 자본 비용을 약 150 베이시스 포인트 절감합니다. 이 제도의 대상이 되려면 개발 사업자는 전해 장치를 신규 재생에너지 자산과 동일한 부지 내에 설치하고, 전력 공급을 1시간 단위로 일치시켜야 합니다. 이 요건으로 인해 자본 비용은 20-30% 증가하지만, 탄소 강도 기준치가 확실히 충족된다는 점이 보장됩니다. 이 인센티브 덕분에 수십 기가와트 규모의 전해 설비 도입 계획이 잇달아 발표되고 있지만, 개발 사업자가 조달상의 병목 현상이나 긴 계통 연계 대기 기간이라는 과제를 해결하고 있는 상황이라, 최종 투자 결정에 이르기까지의 진전은 여전히 제한적입니다. 이 크레딧의 확실성 덕분에, 비피크 시간대의 풍력 및 태양광 발전 전력을 송전망에 잉여 전력으로 방출하는 대신, 저탄소 연료로서 수익화할 수 있는 구조화된 전력 구매 계약이 가능해졌습니다.
배출 감축이 어려운 부문에 대한 미국의 탈탄소화 의무
캘리포니아주의 2024년 ‘저탄소 연료 기준(LCFS)’ 개정안 등의 주 정책에서는 대형 운송 분야의 그린 수소에 대해 1kg당 1.20-1.50달러 상당의 컴플라이언스 크레딧이 부여됩니다. 각 철강 제조업체는 고로에 수소를 주입하는 시험을 실시하여, 코크스용 석탄의 최대 30%를 수소로 대체하는 것을 목표로 하고 있습니다. 클리블랜드 클리프스(Cleveland Cliffs)사는 1억 5,000만 달러를 투자해 설비를 개조한 후, 2026년에 인디애나 하버에서 시범 사업을 시작할 전망입니다. 시멘트 및 유리 업계에서도 유사한 시험이 진행되고 있으며, 전기화가 현실적으로 어려운 분야에서 수소의 역할이 강화되고 있습니다. 2026년에 최종 확정될 연방 정부의 조달 지침은 저탄소 원자재를 우선적으로 고려하게 되어, 공공 공사 도급업체에 대해 인증된 수소 사용을 촉진하게 될 것입니다. 전국적인 탄소 가격이 도입되지 않은 상황에서는 재생에너지의 과잉 공급과 명확한 탄소 강도 목표를 결합한 연안 지역이나 오대호 주변 주에서 수소 도입이 집중되고 있습니다.
높은 LCOH 대 기존의 ‘회색 수소’
배출 감축 조치가 적용되지 않은 SMR(소규모 수소 생산 장치)은 멕시코만 연안의 구매자에게 1kg당 1.00-1.50달러의 수소를 공급하고 있는 반면, 송전망에 연결된 전해 방식의 경우 인센티브 적용 전 비용이 1kg당 4.00-6달러가 듭니다. 3달러의 크레딧을 전액 적용하더라도 공급되는 그린 수소의 가격은 1kg당 1.50-2.50달러에 그치는 경우가 많은데, 이는 50-100%의 프리미엄에 해당하며, 명확한 탄소 가격 책정이 없다면 대부분의 암모니아 및 정유시설 구매자는 이를 감당할 수 없습니다. 블루 수소는 세액 공제 전 가격으로 1kg당 2.00-2.50달러로 가격 차이를 좁히고 있지만, 이용 가능한 이산화탄소 격리 장소와 장기적인 CO2 인수 계약이 필요합니다. 전해조 설비 투자 비용은 현재 PEM 방식의 경우 1kW당 800-900달러까지 낮아졌으며, 이 격차는 더욱 줄어들 것으로 예상되지만, 추가적인 정책 지원이 없는 한 그레이 수소와의 가격 평준화는 대략 2030년경이 되어야 달성될 것으로 전망됩니다.
부문별 분석
그레이 수소는 멕시코만 연안의 정유시설 및 중서부 암모니아 플랜트 주변에 밀집해 있는 100곳 이상의 노후된 SMR 시설을 통해 2025년 생산량의 77.5%를 차지하고 있습니다. 이러한 설비의 대부분은 이미 감가상각이 완료된 상태이며, 천연가스 가격이 1MMBtu당 3달러 전후로 유지될 경우 1kg당 1달러 미만으로 제품을 공급할 수 있으므로, 연방 정부의 탄소세가 부과되지 않는 한 수익성을 유지하고 있습니다. 블루 수소 생산 능력은 사업자가 기존 개질기에 탄소 포집 장치를 추가함으로써 증가하고 있습니다. 엑슨모빌의 베이타운 공장 개조를 통해 2026년부터 연간 130만 톤의 CO₂를 격리할 예정이며, CF 인더스트리즈의 도널드슨빌 프로젝트에서는 2028년까지 연간 200만 톤을 목표로 하고 있습니다. 메탄 열분해를 통한 터콰이즈 수소는 여전히 틈새 시장 수준이지만, 모노리스 머티리얼즈의 네브래스카주 시설에서는 연간 1만 4,000톤을 생산하고 있으며, 제품군 중 하나인 고체 카본블랙이 타이어 업계와 장기 계약을 체결할 수 있다면 생산 규모를 확대할 가능성이 있습니다. 엑셀론(Exelon)과 콘스텔레이션(Constellation)이 진행하는 핑크 수소 시범 사업은 원자력 발전을 활용한 전해 수소 생산의 가능성을 보여주고 있으나, 원자력 발전소와 수소 인수 계약을 연결하기 위한 라이선싱 체계는 여전히 정비 중인 단계입니다.
그린 수소는 2025년 생산량의 불과 3-4%에 불과하지만, 연평균 성장률(CAGR) 32.9%라는 수치를 고려할 때 2031년까지 시장 점유율 15-20%에 도달할 전망입니다. 플러그 파워(Plug Power)사가 로체스터에 건설하여 2025년 12월부터 가동 중인 수력발전을 전원으로 하는 120MW 규모의 플랜트는 하루 50t을 생산하고 있으며, 크레딧 적용 전 비용은 1kg당 약 2.50달러입니다. 캘리포니아주가 2035년까지 트럭 운송의 100% 무공해화를 의무화하겠다는 방침을 내건 데 따라, 에어 리퀴드(Air Liquide)와 쉘(Shell)은 로스앤젤레스 분지 주변에 12곳의 수소 충전소 건설을 계획하고 있습니다. 전반적으로, 발표된 프로젝트가 정격 용량에 도달할 경우, 미국의 그린 수소 생산 시장 규모는 2031년까지 90억 달러를 넘어설 가능성이 있으나, 공시 규제가 강화됨에 따라 그레이 수소의 수익은 정점을 찍을 것으로 예측됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.17According to Mordor Intelligence, the United States hydrogen generation market size is projected to expand from USD 35.25 billion in 2025 and USD 36.58 billion in 2026 to USD 44.16 billion by 2031, registering a CAGR of 3.84% between 2026 to 2031.
This report is Segmented by Source (Grey Hydrogen, Blue Hydrogen, Green Hydrogen, Turquoise Hydrogen, and Pink Hydrogen), Technology (Steam Methane Reforming, Coal Gasification, Auto-Thermal Reforming, Partial Oxidation, and Electrolysis), and Application (Oil Refining, Chemical Processing, Iron and Steel, Transportation Fuel, Power and Energy Storage, and Residential and Commercial Heating).
United States Hydrogen Generation Market Trends and Insights
Inflation Reduction Act Production Tax Credits
Section 45V, effective January 2025, offers up to USD 3 per kg for hydrogen with lifecycle emissions below 0.45 kg CO2e per kg H2, verified through the GREET model. The credit is transferable for 10 years, cutting the project's weighted-average cost of capital by roughly 150 basis points. To qualify, developers must co-locate electrolyzers with new renewable assets and match electricity hourly, a requirement that raises capital by 20-30% but guarantees the carbon-intensity threshold. The incentive has prompted dozens of gigawatt-scale electrolyzer announcements, yet progress to final investment decision remains selective as developers navigate procurement bottlenecks and long interconnection queues. The credit's certainty is enabling structured power-purchase agreements where off-peak wind and solar are monetized into low-carbon fuel rather than spilled on the grid.
U.S. Decarbonization Mandates Across Hard-to-Abate Sectors
State policies such as California's 2024 Low Carbon Fuel Standard amendment award compliance credits worth USD 1.20-1.50 per kg for green hydrogen in heavy-duty transport. Steelmakers are testing hydrogen injection in blast furnaces to replace up to 30% of coking coal; Cleveland-Cliffs expects its Indiana Harbor pilot to start in 2026 under a USD 150 million retrofit. Similar trials are underway in cement and glass, reinforcing hydrogen's role where electrification is impractical. Federal procurement guidelines finalized in 2026 now favor low-carbon inputs, nudging public-works contractors toward certified hydrogen. Absent a nationwide carbon price, adoption clusters in coastal and Great Lakes states that combine renewable overbuild with explicit carbon-intensity targets.
High LCOH Versus Incumbent Gray Hydrogen
Unabated SMR delivers hydrogen to Gulf Coast buyers at USD 1.00-1.50 per kg, whereas grid-connected electrolysis costs USD 4.00-6.00 per kg prior to incentives. Even with the full USD 3 credit, delivered green hydrogen often sits at USD 1.50-2.50 per kg, a 50-100% premium that most ammonia and refinery offtakers cannot absorb without explicit carbon pricing. Blue hydrogen narrows the gap at USD 2.00-2.50 per kg before credits but requires available sequestration sites and durable CO2 offtake contracts. Declining electrolyzer capex, now USD 800-900 per kW for PEM, will compress the delta, yet parity with grey hydrogen is generally expected closer to 2030, absent further policy support.
Other drivers and restraints analyzed in the detailed report include:
- Rising Refinery & Ammonia Retrofit Demand for Blue Hydrogen
- DOE Hydrogen Hub Funding Unlocking Regional Projects
- Sparse Hydrogen Pipeline & Storage Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Grey hydrogen controlled 77.5% of 2025 output due to more than 100 aging SMR facilities clustered around Gulf Coast refineries and Midwest ammonia plants. These units, many long since depreciated, deliver product below USD 1 per kg when natural gas remains near USD 3 per MMBtu, maintaining viability absent federal carbon fees. Blue hydrogen capacity is rising as operators bolt carbon capture onto existing reformers; ExxonMobil's Baytown upgrade will sequester 1.3 million t/yr CO2 from 2026, and CF Industries' Donaldsonville scheme targets 2 million t/yr by 2028. Turquoise hydrogen via methane pyrolysis remains niche, Monolith Materials' Nebraska facility produces 14,000 t/yr, but could scale if the solid carbon black by-product wins long-term tire-industry contracts. Pink hydrogen pilots from Exelon and Constellation illustrate nuclear-powered electrolysis potential, yet licensing frameworks for coupling nuclear plants and hydrogen offtake are still evolving.
Green hydrogen occupied only 3-4% of 2025 volumes, yet its 32.9% CAGR positions it to reach 15-20% penetration by 2031. Plug Power's 120 MW hydropower-backed plant in Rochester, online since December 2025, produces 50 t/day at roughly USD 2.50 per kg pre-credit. California's mandate for 100% zero-emission drayage trucks by 2035 underpins a dozen refueling stations planned by Air Liquide and Shell around the Los Angeles basin. Overall, the United States hydrogen generation market size for green pathways could exceed USD 9 billion by 2031 if announced projects reach nameplate capacity, while grey revenues plateau amid tightening disclosure rules.
Complete Report Scope:
- By Source
- Grey Hydrogen
- Blue Hydrogen
- Green Hydrogen
- Turquoise Hydrogen
- Pink Hydrogen
- By Technology
- Steam Methane Reforming (SMR)
- Coal Gasification
- Auto-Thermal Reforming (ATR)
- Partial Oxidation (POX)
- Electrolysis (Alkaline Electrolysis, Proton Exchange Membrane (PEM), Solid Oxide Electrolysis (SOE))
- By Application
- Oil Refining
- Chemical Processing (Ammonia, Methanol)
- Iron and Steel (DRI, H2-BF)
- Transportation Fuel (FCEV, Marine, Aviation)
- Power and Energy Storage
- Residential and Commercial Heating
List of Companies Covered in this Report:
- Air Products and Chemicals Inc.
- Linde plc
- Air Liquide SA
- Plug Power Inc.
- Cummins Inc.
- Engie SA
- FuelCell Energy Inc.
- Messer Group GmbH
- Bloom Energy Corp.
- Nikola Corp.
- Chart Industries Inc.
- Taiyo Nippon Sanso Holdings Corp.
- ITM Power plc
- McPhy Energy SA
- Enapter AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Inflation Reduction Act (IRA) production tax credits
- 4.2.2 U.S. decarbonization mandates across hard-to-abate sectors
- 4.2.3 Rising refinery & ammonia retrofit demand for blue hydrogen
- 4.2.4 DOE "Hydrogen Hub" funding unlocking regional projects
- 4.2.5 Curtailment-driven offtake for stranded renewable power
- 4.3 Market Restraints
- 4.3.1 High LCOH versus incumbent gray hydrogen
- 4.3.2 Sparse hydrogen pipeline & storage infrastructure
- 4.3.3 Volatile natural-gas input prices for SMR-based producers
- 4.3.4 Water-use permitting risks for utility-scale electrolysis
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
- 4.8 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Source
- 5.1.1 Grey Hydrogen
- 5.1.2 Blue Hydrogen
- 5.1.3 Green Hydrogen
- 5.1.4 Turquoise Hydrogen
- 5.1.5 Pink Hydrogen
- 5.2 By Technology
- 5.2.1 Steam Methane Reforming (SMR)
- 5.2.2 Coal Gasification
- 5.2.3 Auto-Thermal Reforming (ATR)
- 5.2.4 Partial Oxidation (POX)
- 5.2.5 Electrolysis (Alkaline Electrolysis, Proton Exchange Membrane (PEM), Solid Oxide Electrolysis (SOE))
- 5.3 By Application
- 5.3.1 Oil Refining
- 5.3.2 Chemical Processing (Ammonia, Methanol)
- 5.3.3 Iron and Steel (DRI, H2-BF)
- 5.3.4 Transportation Fuel (FCEV, Marine, Aviation)
- 5.3.5 Power and Energy Storage
- 5.3.6 Residential and Commercial Heating
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Air Products and Chemicals Inc.
- 6.4.2 Linde plc
- 6.4.3 Air Liquide SA
- 6.4.4 Plug Power Inc.
- 6.4.5 Cummins Inc.
- 6.4.6 Engie SA
- 6.4.7 FuelCell Energy Inc.
- 6.4.8 Messer Group GmbH
- 6.4.9 Bloom Energy Corp.
- 6.4.10 Nikola Corp.
- 6.4.11 Chart Industries Inc.
- 6.4.12 Taiyo Nippon Sanso Holdings Corp.
- 6.4.13 ITM Power plc
- 6.4.14 McPhy Energy SA
- 6.4.15 Enapter AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


