|
시장보고서
상품코드
2125628
증기 터빈 MRO 시장 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Steam Turbine MRO - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
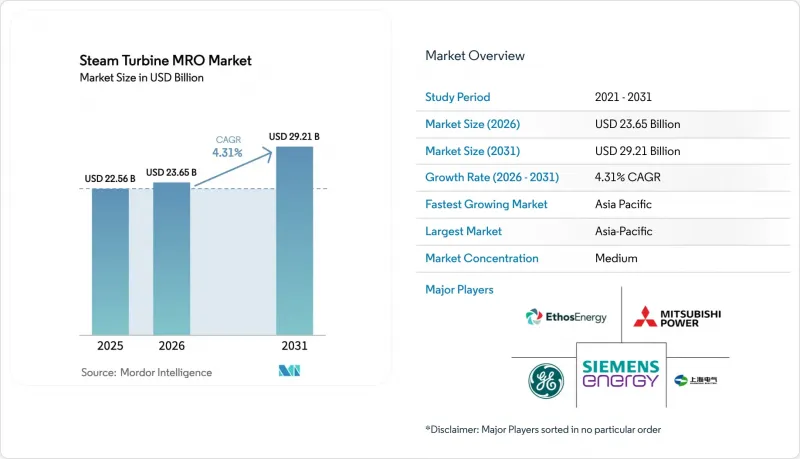
에 의하면, 증기 터빈 MRO 시장 규모는 2025년 225억 6,000만 달러로 평가되었고, 2026년에는 236억 5,000만 달러로 추정되고, 2026-2031년 CAGR 4.31%로 성장을 지속할 전망이며, 2031년에는 292억 1,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 출력별(300MW 미만, 300-600MW, 600MW 이상), 발전소용 연료별(석탄, 천연가스, 원자력, 바이오매스/폐기물 발전), 서비스 유형별(유지보수, 수리, 오버홀), 최종 사용자 산업별(발전, 석유 및 가스, 공업·기타), 그리고 지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다.
세계의 증기 터빈 MRO 시장 동향 및 인사이트
전 세계 화력 발전 설비의 노후화와 수명 주기 연장
2024년, 미국의 석탄 화력 발전 설비의 평균 가동 연수는 44년에 달했으며, 소유주들은 50-60년의 수명 연장을 선택하고 있습니다. 이를 위해서는 로터의 재보링, 크리프 평가 및 3D 공력 블레이드 개조가 필요하며, 일반적으로 신규 건설 비용의 3분의 1로 초기 효율의 80-90%를 회복할 수 있습니다. NTPC는 2025년, Bharat Heavy Electricals사와의 계약에 따라 야금 기술 업그레이드 및 첨단 씰 장치 도입을 포함한 개보수 공사를 실시하여, 인도 국내 총 3.8GW에 해당하는 15기의 가동 수명을 연장했습니다. 중국도 유사한 추세를 보이고 있으며, 2010년 이전에 건설된 아임계 발전소에 대해 2030년 탄소 집약도 목표를 달성하면서 동시에 폐쇄 조치를 연기하기 위해 씰 업그레이드 및 저압 단 교체 등의 개보수 작업을 진행하고 있습니다.
복합 사이클 발전소 및 첨단 초초임계 발전소의 확대
이러한 발전 유닛에서는 증기 온도가 600°C를 초과하기 때문에 크리프 현상이 가속화되어, 기존의 아임계 발전 설비에 비해 점검 빈도가 2배로 늘어났습니다. 일본의 J-POWER는 2024년에 650°C 대응 니켈계 블레이드를 도입했으나, 여기에는 전문적인 용접 보수가 필요하여 대부분의 독립 업체에서는 대응할 수 없습니다. 중국은 2025년에 28 GW의 초초임계 발전 용량을 추가하고, 12,000시간마다 점검을 의무화함에 따라 오버홀 발생 빈도가 높아지고 있습니다. 지멘스 에너지가 사우디아라비아에서 체결한 15년간의 크레이어 LTSA는 고효율 자산이 가동 시작 직후부터 장기간에 걸쳐 MRO 현금 흐름을 확보할 수 있음을 보여줍니다.
OECD 국가들의 석탄 자산 조기 폐지
EIA 데이터에 따르면, 2024년 미국에서 23GW 규모의 석탄 화력 발전소가 폐쇄되었으며, 2029년까지 추가로 14GW가 폐쇄될 예정이어서 대응 가능한 MRO 수요의 상당 부분이 사라지게 될 것입니다. 영국은 2024년에 마지막 석탄 화력 발전소를 폐쇄할 예정이며, 독일에서는 2038년으로 예정되었던 석탄 화력에서 철수 시기를 2030년으로 앞당길지 여부가 논의되고 있어, 유럽의 서비스 수요가 압박을 받고 있습니다. IEA는 2035년까지 OECD 국가들의 석탄 화력 발전 용량이 40% 감소할 것으로 예측하고 있으며, 이러한 축소는 가스나 원자력으로의 전환이 불가능한 독립 발전 사업자들에게 특히 큰 타격이 될 것입니다.
부문별 분석
2025년에는 1990년대에 건설된 방대한 아임계 석탄 화력 발전 설비 덕분에 300-600MW급 유닛이 증기 터빈 MRO 시장 점유율의 50.5%를 차지했습니다. 600MW를 초과하는 터빈은 2031년까지 연평균 성장률(CAGR) 5.1%를 기록할 전망이며, 중국, 인도, 일본이 니켈 합금 수리 및 위상 배열 초음파 검사가 필요한 초초임계 설계를 도입함에 따라 이 부문의 증기 터빈 MRO 시장 규모를 끌어올릴 것으로 예측됩니다.
중출력 발전 단위가 결코 시대에 뒤떨어진 것은 아닙니다. J-POWER는 2025년, 저압 단의 블레이드를 3D 블레이드로 교체함으로써 4기의 600 MW 준초임계 발전 단위의 효율을 2.3포인트 향상시켰습니다. 이는 폐로보다 개보수가 더 경제적임을 보여줍니다. 300MW 미만의 설비는 부품 부족이나 조기 폐로에 직면해 있으며, 미국에서는 설비 용량의 22%를 차지하지만 MRO 수익에서 차지하는 비중은 고작 14%에 그치고 있습니다.
2025년에는 석탄 화력 발전소가 전 세계 지출의 60.1%를 차지했으며, OECD 국가들에서 원전 폐로가 진행되고 있음에도 불구하고 증기 터빈 MRO 시장을 지탱하고 있습니다. 이는 아시아에서 1,900GW의 석탄 화력 발전 용량이 가동되고 있기 때문입니다. 원자력 분야의 공사는 NRC(미국 원자력규제위원회) 및 ASN(프랑스 원자력안전청)의 승인을 통해 미국과 프랑스의 원자로 가동 수명이 80년으로 연장됨에 따라,연평균 성장률(CAGR) 5.5%로 모든 연료 유형을 상회하는 속도로 확대될 것이며, 증기 발생기 교체 및 로터 재보링 범위가 확대됨에 따라 원자력 발전소의 증기 터빈 MRO 시장 규모를 끌어올릴 것입니다.
천연가스 복합 사이클 발전 설비는 지출의 25%를 차지하고 있으며, 중동의 메가 프로젝트에 대한 장기 서비스 계약(LTSA)에 힘입어 연평균 성장률(CAGR) 4.8%로 성장할 전망입니다. 바이오매스 및 폐기물 에너지화(WtE) 플랜트는 여전히 틈새 시장이지만, 내식성 코팅이 필요하기 때문에 전문적인 수리 기회가 될 것입니다.
지역별 분석
아시아태평양은 2025년 매출의 49.6%를 차지했으며, 중국, 인도, 동남아시아의 초초임계압 및 복합 사이클 발전 설비의 확장에 따라 2031년까지 연평균 성장률(CAGR) 5.8%를 나타낼 것으로 예측됩니다. 중국 국가전력망(State Grid)이 계약한 78 GW의 초초임계 발전 용량은 이미 니켈 합금 용접 및 위상 배열 초음파 검사(UT) 역량을 갖춘 국내 수리 업체들이 담당하고 있어, 이로 인해 외국 OEM 제조업체들 시장 점유율이 압박받고 있습니다. 인도의 NTPC가 Bharat Heavy Electricals에 3.8 GW 규모의 개보수 계약을 수주한 것은 향후 10년에 걸친 대규모 수명 연장 프로젝트의 파이프라인을 여실히 보여줍니다.
북미에서는 석탄 화력 발전소의 폐쇄가 원자력 발전소의 수명 연장에 따른 증가분을 상쇄하고 있어 성장이 둔화되고 있습니다. 그러나 250 GW의 복합 사이클 발전 용량이 견고한 장기 유지보수 계약(LTSA) 기반을 뒷받침하고 있습니다. 유럽 시장은 프랑스의 원자력 발전소 개보수 및 재생에너지의 안정적인 공급을 목적으로 한 독일의 CCGT(복합 사이클 가스터빈) 증설에 의해 주도되고 있습니다. 중동 및 아프리카 시장의 성장은 LTSA와 디지털 트윈 분석을 연계한 크레이어,알 다프라, 뉴 캐피탈의 메가 계약을 통해 뒷받침되고 있습니다. 남미의 6% 시장 점유율은 브라질의 수력·화력 하이브리드 발전소 개보수와 바카 무에르타 셰일 가스와 연계된 아르헨티나의 열병합 발전 사업 덕분에 혜택을 보고 있습니다.
기타 혜택 :
- Excel 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the steam turbine MRO market size is expected to grow from USD 22.56 billion in 2025 to USD 23.65 billion in 2026 and is forecast to reach USD 29.21 billion by 2031 at 4.31% CAGR over 2026-2031.
This report is Segmented by Capacity (Below 300 MW, 300 To 600 MW, and Above 600 MW), Plant Fuel (Coal, Natural Gas, Nuclear, and Biomass/Waste-to-Energy), Service Type (Maintenance, Repair, and Overhaul), End-User Industry (Power Generation, Oil and Gas, and Industrial and Other), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Steam Turbine MRO Market Trends and Insights
Aging Global Thermal-Power Fleet Lifecycle Extension
The median U.S. coal unit age reached 44 years in 2024, and owners are choosing 50-60 year life extensions that call for rotor re-boring, creep assessments, and 3D aerodynamic blade retrofits, typically restoring 80-90% original efficiency at one-third of new-build capital. NTPC extended fifteen Indian units totaling 3.8 GW in 2025 under a Bharat Heavy Electricals contract covering metallurgy upgrades and advanced seals. China mirrors the pattern, retrofitting pre-2010 subcritical plants with upgraded seals and low-pressure stage replacements to meet 2030 carbon-intensity targets while deferring decommissioning.
Expansion of Combined-Cycle & Advanced Ultra-Supercritical Plants
Steam temperatures above 600 °C in these units accelerate creep, doubling inspection frequency versus legacy subcritical fleets. Japan's J-POWER introduced nickel-based 650 °C blades in 2024, requiring specialist weld repair unserved by most independents. China added 28 GW of ultra-supercritical capacity in 2025, and mandated 12,000-hour inspections, raising overhaul incidence. Siemens Energy's 15-year Qurayyah LTSA in Saudi Arabia demonstrates how high-efficiency assets lock in long-duration MRO cash flows immediately after commissioning.
Accelerated Retirement of Coal Assets in OECD
EIA data show 23 GW of U.S. coal shut in 2024, with another 14 GW slated by 2029, eliminating large swaths of addressable MRO volume. The U.K. closed its last coal station in 2024, and Germany debates pulling its 2038 exit forward to 2030, squeezing European service demand. IEA forecasts a 40% decline in OECD coal capacity by 2035, a contraction that disproportionately hurts independents unable to pivot to gas or nuclear.
Other drivers and restraints analyzed in the detailed report include:
- OEM Long-Term Service Agreement Boom
- Predictive-Maintenance Digital Twins Adoption
- High Outage CAPEX & Downtime for Major Overhauls
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, 300-600 MW units accounted for 50.5% of the steam turbine MRO market share thanks to the vast 1990s subcritical coal fleet. Above-600 MW turbines will post a 5.1% CAGR to 2031, lifting the steam turbine MRO market size for this bracket as China, India, and Japan deploy ultra-supercritical designs that demand nickel-alloy repairs and phased-array ultrasonic inspections.
Mid-range units are far from obsolete; J-POWER lifted four 600 MW subcritical units' efficiency 2.3 points by swapping low-pressure stages for 3D blades in 2025, underscoring retrofit economics over retirement. Below-300 MW machines face parts shortages and early retirement, producing only 14% of MRO revenue on 22% of capacity in the United States.
Coal plants generated 60.1% of global spend in 2025 and underpin the steam turbine MRO market despite OECD retirements, because Asia runs 1,900 GW of coal capacity. Nuclear work will outpace all fuels at 5.5% CAGR after NRC and ASN approvals push U.S. and French reactors to 80-year lives, swelling steam-generator swaps and rotor re-boring scopes that expand the steam turbine MRO market size for nuclear sites.
Natural-gas combined-cycle fleets carry 25% of spending and will grow 4.8% CAGR, buoyed by Middle-East megaproject LTSAs. Biomass and WtE plants remain niche yet require corrosion-resistant coatings, a specialized repair opportunity.
Complete Report Scope:
- By Capacity
- Below 300 MW
- 300 to 600 MW
- Above 600 MW
- By Plant Fuel
- Coal
- Natural Gas
- Nuclear
- Biomass/Waste-to-Energy
- By Service Type
- Maintenance
- Repair
- Overhaul
- By End-user Industry
- Power Generation
- Oil and Gas (Up-/Mid-/Down-stream)
- Industrial and Other
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific controlled 49.6% of 2025 revenue and is projected to deliver a 5.8% CAGR to 2031 as China, India, and Southeast Asia expand ultra-supercritical and combined-cycle fleets. State Grid contracts for 78 GW of Chinese ultra-supercritical capacity already rely on domestic repair houses that possess nickel-alloy weld and phased-array UT capabilities, compressing foreign OEM share. India's 3.8 GW NTPC refurbishment award to Bharat Heavy Electricals showcases the large-scale lifecycle-extension pipeline through the next decade.
North America's growth is slowing down as coal closures offset nuclear life-extension gains; however, 250 GW of combined-cycle capacity anchors a robust LTSA base. Europe's market is propelled by French nuclear upgrades and German CCGT build-outs to firm renewables. The Middle East and Africa market growth is fueled by Qurayyah, Al Dhafra, and New Capital mega-contracts linking LTSAs with digital-twin analytics. South America's 6% slice benefits from Brazilian hydro-thermal hybrid upgrades and Argentine cogeneration tied to Vaca Muerta shale gas.
- GE Vernova
- Siemens Energy
- Mitsubishi Power
- Shanghai Electric
- Harbin Electric
- Dongfang Turbine
- Bharat Heavy Electricals
- Baker Hughes
- Sulzer
- EthosEnergy
- Elliott Group
- Triveni Turbine
- Doosan Enerbility
- MAN Energy Solutions
- Toshiba Energy Systems
- Ansaldo Energia
- Fuji Electric
- Voith Turbo
- Kessels Steam Turbines
- TMS Turbomaschinenservice
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging global thermal-power fleet lifecycle extension
- 4.2.2 Expansion of combined-cycle & advanced ultra-supercritical plants
- 4.2.3 OEM long-term service agreement (LTSA) boom
- 4.2.4 Predictive-maintenance digital twins adoption
- 4.2.5 Decarbonization retrofits incl. H2 / NH3 co-firing
- 4.2.6 Rise of industrial micro-CHP in emerging markets
- 4.3 Market Restraints
- 4.3.1 Accelerated retirement of coal assets in OECD
- 4.3.2 High outage CAPEX & downtime for major overhauls
- 4.3.3 OEM software lock-in limiting independents
- 4.3.4 Scarcity of legacy spare parts <300 MW units
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Long-Term Service Agreement (LTSA) Trend Analysis
5 Market Size & Growth Forecasts
- 5.1 By Capacity
- 5.1.1 Below 300 MW
- 5.1.2 300 to 600 MW
- 5.1.3 Above 600 MW
- 5.2 By Plant Fuel
- 5.2.1 Coal
- 5.2.2 Natural Gas
- 5.2.3 Nuclear
- 5.2.4 Biomass/Waste-to-Energy
- 5.3 By Service Type
- 5.3.1 Maintenance
- 5.3.2 Repair
- 5.3.3 Overhaul
- 5.4 By End-user Industry
- 5.4.1 Power Generation
- 5.4.2 Oil and Gas (Up-/Mid-/Down-stream)
- 5.4.3 Industrial and Other
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 NORDIC Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 GE Vernova
- 6.4.2 Siemens Energy
- 6.4.3 Mitsubishi Power
- 6.4.4 Shanghai Electric
- 6.4.5 Harbin Electric
- 6.4.6 Dongfang Turbine
- 6.4.7 Bharat Heavy Electricals
- 6.4.8 Baker Hughes
- 6.4.9 Sulzer
- 6.4.10 EthosEnergy
- 6.4.11 Elliott Group
- 6.4.12 Triveni Turbine
- 6.4.13 Doosan Enerbility
- 6.4.14 MAN Energy Solutions
- 6.4.15 Toshiba Energy Systems
- 6.4.16 Ansaldo Energia
- 6.4.17 Fuji Electric
- 6.4.18 Voith Turbo
- 6.4.19 Kessels Steam Turbines
- 6.4.20 TMS Turbomaschinenservice
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment