|
시장보고서
상품코드
2125701
유럽의 경질 플라스틱 포장 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Rigid Plastic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
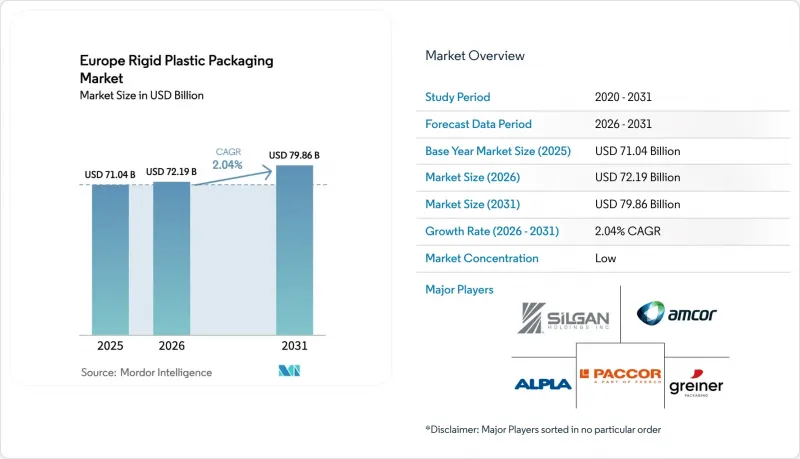
에 의하면, 유럽의 경질 플라스틱 포장 시장 규모는 2025년 710억 4,000만 달러로 평가되었고, 2026년 721억 9,000만 달러에서 2031년까지 798억 6,000만 달러로 확대될 전망이며, 2026-2031년 CAGR 2.04%를 나타낼 것으로 예측됩니다.
본 보고서는 수지 유형별(폴리에틸렌 테레프탈레이트, 폴리프로필렌, 기타), 제품 유형별(병·용기, 트레이·용기, 뚜껑 및 마개, 기타), 최종 사용자 산업별(식품, 음료, 의료 및 의약품, 기타), 제조 공정별(사출 성형, 블로우 성형, 기타), 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽의 경질 플라스틱 포장 시장 동향 및 인사이트
음료 산업에서 재활용 가능한 경질 PET 병 수요 급증
각 음료 제조업체는 2025년까지 25%, 2030년까지 30%라는 유럽연합(EU)의 재생 재료 함유율 기준을 충족하기 위해 100% 재활용 가능한 PET로의 전환을 추진하고 있으며, 이에 따라 독일, 네덜란드, 프랑스에서는 병-병 재활용에 대한 투자가 촉진되고 있습니다. 2025년, 독일의 보증금 제도 네트워크는 PET 용기의 98.5%를 회수하여 약 45만 톤의 식품 등급 rPET 원료를 공급했습니다. 서유럽의 rPET 현물 가격은 톤당 평균 1,200-1,500유로(톤당 1,356-1,695달러)였으나, 브랜드 소유주들은 가격 변동을 억제하기 위해 다년 계약을 체결하고 있습니다. 스트레치 블로우 성형 기술의 개선으로 PET 병의 평균 무게는 18g에서 15g으로 줄어들었고, 수지 사용량은 17% 감소했습니다. 지속적인 규제 압력과 투명한 지속가능성을 지향하는 소비자 성향으로 인해, 2028년까지 rPET 병 수요는 두 자릿수 성장을 보일 것으로 전망됩니다.
전자상거래의 급속한 성장에 따른 경질 포장 용기 수요 증가
서유럽에서 온라인 소매 매출이 전체 매출에서 차지하는 비중은 2023년 18%에서 2025년에는 22%로 상승할 전망이며, 도시 지역의 라스트 마일 배송에서 파손되기 쉬운 상품을 보호하기 위한 경질 트레이, 클램쉘, 재사용형 HDPE 크레이트에 대한 수요가 증가하고 있습니다. 폴란드의 풀필먼트 허브에서 채택된 반환형 운송 포장재는 50-100회의 사용 주기를 견디며, 골판지 대체품에 비해 1회당 비용을 40% 절감하고 있습니다. 스냅핏식 뚜껑이 장착된 열성형 폴리프로필렌 트레이가 온라인 식품 쇼핑의 청과물 2차 포장용 골판지를 대체하여 전체 포장 무게를 25% 줄였습니다. 화장품 브랜드는 D2C(소비자 직접 판매) 채널에서의 개봉 경험을 향상시키기 위해, 변조 방지 기능이 있는 캡이 장착된 경질 용기를 선호하여 채택하고 있습니다. 이러한 구조적 변화는 특히 당일 배송 서비스가展開되는 인구 밀집 도시 지역에서 전자상거래용 경질 포장이 기존 소매용 포장을 능가하는 성장을 지속할 것임을 시사합니다.
일회용 플라스틱 세금 및 확대 생산자 책임(EPR) 수수료
영국에서는 재생 재료 함유율이 30% 이하인 포장에 대해 1톤당 210.82파운드(1톤당 274달러)의 세금을 부과하고 있으며, 이로 인해 2025년에는 가공업체의 비용이 약 10% 증가하게 될 것입니다. 스페인에서는 2023년부터 도입된 1kg당 0.45유로(1kg당 0.51달러)의 세금이 육류 가공업체들로 하여금 폴리스티렌 트레이에서 섬유계 대체재로 전환하도록 촉진했습니다. 이탈리아의 에코모듈레이션 제도에서는 재활용 가능성에 따라 1kg당 0.05-0.80유로(1kg당 0.06-0.90달러)가 부과되며, 다층 포장에는 벌금이 부과됩니다. 그 결과, 소규모 열성형 제조업체들은 2025년 폴란드와 체코에서 잇따라 발생한 인수 사례에서 알 수 있듯이, 산업 재편의 주요 대상이 되고 있습니다. 행정 보고의 부담은 혁신에 투입될 자원을 압박하고 있으며, 수수료 통일과 관련된 논의에서 2028년까지 규제가 더욱 강화될 것임을 시사하고 있습니다.
부문 분석
2025년, 폴리에틸렌은 유제품, 세제, 운송용 크레이트용 고밀도 폴리에틸렌 병에 힘입어 28.43%의 시장 점유율을 유지했습니다. 대조적으로, 폴리에틸렌 테레프탈레이트(PET)는 rPET 원료를 확대하는 보증금 반환 제도와 2030년까지 병에 30%의 재활용 PET 사용을 의무화하는 EU 규제의 뒷받침을 받아, 2031년까지 연평균 3.12%의 성장이 예상됩니다. 병 대 병(Bottle-to-Bottle) 재활용 능력은 2025년에 280만 톤에 달했으나, 15% 공급 부족으로 인해 rPET 가격이 높은 수준을 유지하고 있으며, 이로 인해 음료 공장 인근의 세척 라인 및 플레이크 생산 라인에 대한 가공업체의 투자가 촉진되고 있습니다.
이스트만(Eastman)이 노르망디에 건설한 연간 16만 톤 규모의 글리콜 분해 플랜트와 같은 화학 재활용 시범 사업은 2027년 이후 식품 등급 원료공급을 확대할 것으로 기대됩니다. 폴리프로필렌은 총량의 약 23%를 차지하며, 내열성과 투명성이 요구되는 핫필용 트레이나 의약품 블리스터 팩에서 여전히 주요 소재로 사용되고 있습니다. 대형 소비재 제조업체들의 리필(재충전) 시범 사업에서는 10-15회의 재충전 주기를 견딜 수 있도록 설계된 내구성이 뛰어난 HDPE 병이 사용되고 있으며, 이로 인해 1회당 버진 수지 사용량을 3분의 1로 줄이고 있습니다. 프랑스와 벨기에의 발포 플라스틱 금지 조치에 따른 폴리스티렌의 감소에도 불구하고, PET의 성장세에 힘입어 2029년까지 폴리에틸렌과의 격차는 줄어들 것이며, 유럽의 경질 플라스틱 포장 시장 구성은 재활용률이 높은 제품 형태로 전환될 전망입니다.
2025년에는 병과 용기가 46.65%의 점유율을 차지하여 주도적인 위치를 차지했으며, 음료, 유제품, 개인 위생 용품에 사용되고 있습니다. 그러나 2024년 7월 ‘일회용 플라스틱 지침’의 규제를 충족하기 위해 모든 음료 제조업체가 테더가 부착된 캡 구조로 전환하고 있는 만큼, 캡 및 마개 부문은 2031년까지 연평균 성장률(CAGR) 3.37%라는 가장 높은 성장 속도를 유지할 전망입니다. 캐비티당 5만-15만 유로(5만 6,500-16만 9,500달러)에 달하는 금형 개조 비용으로 인해 소규모 성형 업체들이 시장에서 철수하고 있으며, 생산량은 대형 캡 전문 제조업체로 이동하고 있습니다.
500mL 생수병의 경우 이미 15g까지 경량화된 PET 병은 낙하 시험 성능을 저해하지 않으면서 재료 효율을 향상시킨 좋은 예입니다. 경질 폴리프로필렌 트레이는 신선 식품 및 냉장 식품 시장의 30%를 차지하고 있으며, 습기가 우려되는 부문에서는 종이 트레이의 확산을 저지하고 있습니다. 주로 HDPE 드럼으로 구성된 중간 벌크 컨테이너는 화학 및 도료 산업에서 여전히 필수적이며, 임대 모델의 도입으로 지속적인 수익원이 창출될 것으로 예측됩니다. 전반적으로, EU 지역 내에서 설계 지침이 통일됨에 따라 캡은 다른 제품군을 능가하는 성장을 유지할 전망이며, 금형 투자 및 소비자 인식 제고를 위한 지출이 더욱 강화될 것으로 보입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJYAccording to Mordor Intelligence, the Europe rigid plastic packaging market size is projected to expand from USD 71.04 billion in 2025 and USD 72.19 billion in 2026 to USD 79.86 billion by 2031, registering a CAGR of 2.04% between 2026 to 2031.

This report is Segmented by Resin Type (Polyethylene Terephthalate, Polypropylene, and More), Product Type (Bottles and Jars, Trays and Containers, Caps and Closures, and More), End-User Industry (Food, Beverage, Healthcare and Pharmaceuticals, and More), Manufacturing Process (Injection Moulding, Blow Moulding, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Rigid Plastic Packaging Market Trends and Insights
Surging Demand for Recyclable Rigid PET Bottles in Beverages
Beverage producers are shifting to 100% recyclable PET to meet the European Union's 25% recycled-content rule by 2025 and the 30% threshold by 2030, spurring investment in bottle-to-bottle recycling in Germany, the Netherlands, and France. Germany's deposit network captured 98.5% of PET containers in 2025, supplying roughly 450,000 tonnes of food-grade rPET feedstock. Spot prices for Western European rPET averaged EUR 1,200-1,500 per tonne (USD 1,356-1,695 per tonne) yet brand owners lock in multi-year contracts that mute volatility. Stretch-blow-moulding upgrades trimmed average water-bottle weight from 18 g to 15 g, cutting resin use by 17%. Continued regulatory pressure and consumer preference for transparent sustainability claims are forecast to drive double-digit rPET bottle demand through 2028.
Booming E-Commerce Boosting Protective Rigid Formats
Western Europe's online retail share rose to 22% of total sales in 2025, up from 18% in 2023, heightening demand for rigid trays, clamshells, and reusable HDPE crates that protect fragile goods during urban last-mile delivery. Returnable transport packaging adopted in Polish fulfillment hubs withstands 50-100 cycles and lowers per-trip cost by 40% relative to corrugated alternatives. Thermoformed polypropylene trays with snap-fit lids are replacing secondary cardboard for e-grocery produce, reducing overall packaging weight by 25%. Cosmetics brands favor rigid jars with tamper-evident closures to elevate unboxing experiences in direct-to-consumer channels. This structural shift suggests that e-commerce-oriented rigid formats will continue to outpace traditional retail packaging, especially in dense metro markets served by same-day couriers.
Single-Use-Plastic Taxes and Extended Producer Responsibility Fees
The United Kingdom levies GBP 210.82 per tonne (USD 274 per tonne) on packaging containing less than 30% recycled content, increasing converter costs by roughly 10% in 2025. Spain's EUR 0.45 per kg (USD 0.51 per kg) tax, in place since 2023, spurred meat processors to switch from polystyrene trays to fiber-based alternatives. Italy's eco-modulation scheme charges EUR 0.05-0.80 per kg (USD 0.06-0.90 per kg) based on recyclability, penalizing multilayer packs. Smaller thermoformers lacking scale are therefore prime consolidation targets, as seen in multiple 2025 acquisitions across Poland and the Czech Republic. Administrative reporting burdens divert resources from innovation, and fee harmonization discussions suggest further tightening through 2028.
Other drivers and restraints analyzed in the detailed report include:
- Growth of EU Deposit-Return Schemes Accelerating Collection Infrastructure
- Rapid Scale-Up of European Bioplastics Capacity
- Shift Toward Paper and Flexible Substitutes for Lightweighting
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene retained 28.43% market share in 2025, anchored by high-density bottles for dairy, detergents and transport crates. In contrast, polyethylene terephthalate is forecast to grow 3.12% annually through 2031, propelled by deposit-return schemes that widen rPET feedstock and by EU rules mandating 30% recycled PET in bottles by 2030. Bottle-to-bottle recycling capacity climbed to 2.8 million tonnes in 2025, yet a 15% shortfall keeps rPET at a premium, reinforcing converter investments in washing and flake lines close to beverage plants.
Chemical recycling pilots, such as Eastman's 160,000-tonne glycolysis unit in Normandy, are expected to boost food-grade supply beyond 2027. Polypropylene, holding roughly 23% of volume, remains a staple for hot-fill trays and pharmaceutical blister packs that demand heat resistance and clarity. Refill pilots by consumer-goods majors use durable HDPE bottles engineered for 10-15 refill cycles, trimming virgin resin per use by one-third. Despite polystyrene declines tied to French and Belgian foam bans, PET's momentum will likely narrow the gap with polyethylene before 2029, shifting the Europe rigid plastic packaging market size composition toward higher-recycled-content formats.
Bottles and jars dominated with 46.65% share in 2025, servicing beverages, dairy and personal care. However, caps and closures are on pace for the strongest 3.37% CAGR through 2031 as every beverage player converts to tethered-cap geometry to satisfy July 2024 Single-Use Plastics Directive rules. Retooling costs of EUR 50,000-150,000 (USD 56,500-169,500) per cavity have prompted exit by small moulders, shifting volume toward large closure specialists.
Lightweighted PET bottles, already down to 15 g for 500 mL water, exemplify material-efficiency gains without sacrificing drop performance. Rigid polypropylene trays capture 30% volume in produce and chilled food, resisting the creep of paper trays where moisture is a concern. Intermediate bulk containers, predominantly HDPE drums, remain indispensable for chemicals and coatings, and adoption of leasing models is expected to open recurring revenue streams. Overall, caps will likely keep outpacing other product lines as design guidelines become uniform across the bloc, reinforcing tooling investment and consumer-education spending.
Complete Report Scope:
- By Resin Type
- Polyethylene
- High-Density Polyethylene (HDPE)
- Low-Density Polyethylene (LDPE)
- Linear Low-Density Polyethylene (LLDPE)
- Polyethylene Terephthalate
- Polypropylene
- Polystyrene and EPS
- Other Resin Types
- Polyethylene
- By Product Type
- Bottles and Jars
- Trays and Containers
- Caps and Closures
- Intermediate Bulk Containers (IBCs)
- Drums
- Other Product Types
- By End-user Industry
- Food
- Candy and Confectionery
- Dairy and Frozen
- Meat, Poultry and Seafood
- Other Food Types
- Beverage
- Healthcare and Pharmaceuticals
- Cosmetics and Personal Care
- Industrial Chemicals
- Building and Construction
- Other End-user Industries
- Food
- By Manufacturing Process
- Injection Moulding
- Blow Moulding
- Thermoforming
- Compression Moulding
- Extrusion
- Other Manufacturing Process
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Poland
- Netherlands
- Rest of Europe
List of Companies Covered in this Report:
- Alpla Werke Alwin Lehner GmbH & Co KG
- Mauser Packaging Solutions Holding Company
- Amcor plc
- Greiner Packaging International GmbH
- Greif, Inc.
- PACCOR Packaging GmbH (Faerch Group)
- Plastipak Holdings, Inc.
- Schoeller Allibert Services B.V.
- Silgan Holdings Inc.
- Albea Group
- Coda Plastics Ltd.
- Frapak Packaging B.V.
- Schutz GmbH & Co. KGaA
- WERIT Kunststoffwerke W. Schneider GmbH & Co. KG
- ACTI PACK S.A.S.
- RETAL Industries Ltd.
- RIKUTEC Group
- AST Kunststoffverarbeitung GmbH
- Robinson plc
- Esterform Packaging Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Demand for Recyclable Rigid PET Bottles in Beverages
- 4.2.2 Booming E-Commerce Boosting Protective Rigid Formats
- 4.2.3 Growth of EU Deposit-Return Schemes Accelerating Collection Infrastructure
- 4.2.4 Rapid Scale-Up of European Bioplastics Capacity
- 4.2.5 Refill-and-Reuse Store Pilots Driving HDPE Bottle Redesigns
- 4.2.6 Pharma Cold-Chain Expansion Needing High-Barrier Rigid Packs
- 4.3 Market Restraints
- 4.3.1 Single-Use-Plastic Taxes and Extended Producer Responsibility Fees
- 4.3.2 Shift Toward Paper and Flexible Substitutes for Lightweighting
- 4.3.3 Energy-Price Shocks Raising Extrusion and Injection Costs
- 4.3.4 Volatile rPET and rHDPE Prices Squeezing Converter Margins
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Resin Type
- 5.1.1 Polyethylene
- 5.1.1.1 High-Density Polyethylene (HDPE)
- 5.1.1.2 Low-Density Polyethylene (LDPE)
- 5.1.1.3 Linear Low-Density Polyethylene (LLDPE)
- 5.1.2 Polyethylene Terephthalate
- 5.1.3 Polypropylene
- 5.1.4 Polystyrene and EPS
- 5.1.5 Other Resin Types
- 5.1.1 Polyethylene
- 5.2 By Product Type
- 5.2.1 Bottles and Jars
- 5.2.2 Trays and Containers
- 5.2.3 Caps and Closures
- 5.2.4 Intermediate Bulk Containers (IBCs)
- 5.2.5 Drums
- 5.2.6 Other Product Types
- 5.3 By End-user Industry
- 5.3.1 Food
- 5.3.1.1 Candy and Confectionery
- 5.3.1.2 Dairy and Frozen
- 5.3.1.3 Meat, Poultry and Seafood
- 5.3.1.4 Other Food Types
- 5.3.2 Beverage
- 5.3.3 Healthcare and Pharmaceuticals
- 5.3.4 Cosmetics and Personal Care
- 5.3.5 Industrial Chemicals
- 5.3.6 Building and Construction
- 5.3.7 Other End-user Industries
- 5.3.1 Food
- 5.4 By Manufacturing Process
- 5.4.1 Injection Moulding
- 5.4.2 Blow Moulding
- 5.4.3 Thermoforming
- 5.4.4 Compression Moulding
- 5.4.5 Extrusion
- 5.4.6 Other Manufacturing Process
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Poland
- 5.5.7 Netherlands
- 5.5.8 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Alpla Werke Alwin Lehner GmbH & Co KG
- 6.4.2 Mauser Packaging Solutions Holding Company
- 6.4.3 Amcor plc
- 6.4.4 Greiner Packaging International GmbH
- 6.4.5 Greif, Inc.
- 6.4.6 PACCOR Packaging GmbH (Faerch Group)
- 6.4.7 Plastipak Holdings, Inc.
- 6.4.8 Schoeller Allibert Services B.V.
- 6.4.9 Silgan Holdings Inc.
- 6.4.10 Albea Group
- 6.4.11 Coda Plastics Ltd.
- 6.4.12 Frapak Packaging B.V.
- 6.4.13 Schutz GmbH & Co. KGaA
- 6.4.14 WERIT Kunststoffwerke W. Schneider GmbH & Co. KG
- 6.4.15 ACTI PACK S.A.S.
- 6.4.16 RETAL Industries Ltd.
- 6.4.17 RIKUTEC Group
- 6.4.18 AST Kunststoffverarbeitung GmbH
- 6.4.19 Robinson plc
- 6.4.20 Esterform Packaging Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment